Adult social care workforce, 2026: vacancies fall to a decade low but growth slows
Vacancies in adult social care in England fell to around 96,000, their lowest level in a decade, according to the Skills for…
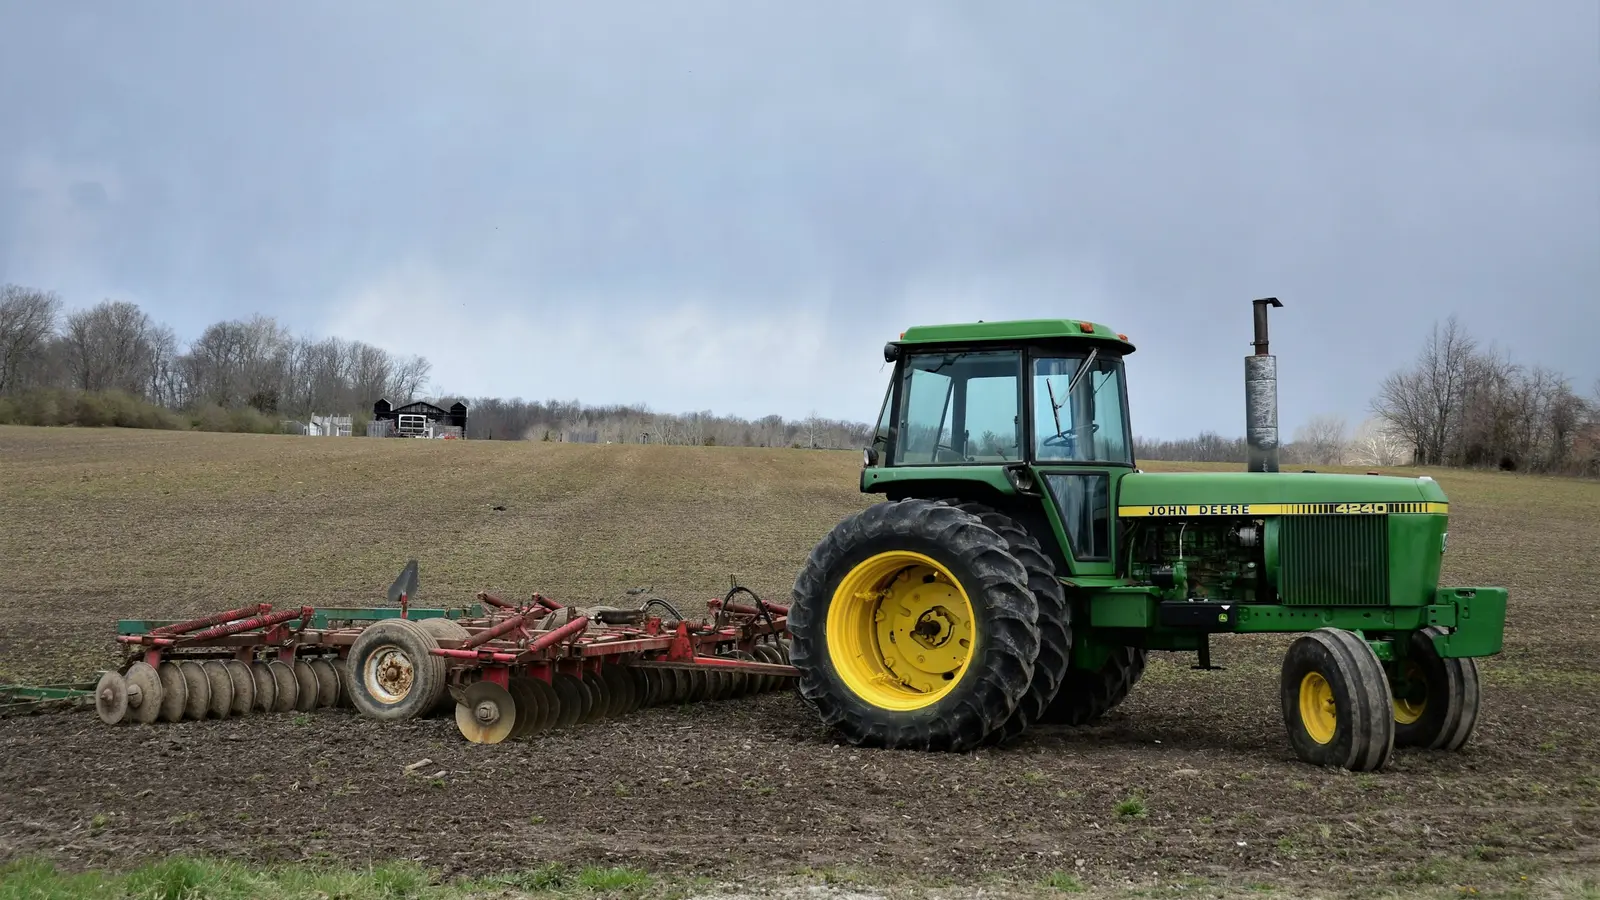
The second SFI26 window opened on 22 September 2026 with £233 million and closes when the money runs out. What it means for farm cash flow and finance.
This article is for farmers and land managers in England who want to know what the reopened Sustainable Farming Incentive offers and how it fits with their cash flow and finance. SFI pays farmers for actions that benefit the environment, and for many farms it is an important part of income. Below we set out what has opened, who can apply and the funding options for farm businesses. Smart Funding Solutions is a broker, not a lender: we compare whole-of-market options across 300+ lenders, arranging funding from £10,000 to £20 million.
As Defra announced on its Farming blog, the second application window for SFI26 opened on 22 September 2026. Its budget is £233 million, made up of:
There is no fixed closing date. The window closes once the money is allocated, and applications started but not submitted by then will not be accepted. SFI26 agreements must start by 1 April 2027 to use this financial year's budget.
To apply, a farm business must be registered with the Rural Payments Agency, have a Single Business Identifier (SBI) and have at least 3 hectares of eligible agricultural land linked to it. The full rules are in the SFI26 scheme guidance on GOV.UK.
Defra advises farmers to read the "Get ready to apply" section of the guidance first and to check that their digital land maps are correct. Farmers whose existing ELM agreements end on or before 28 February 2027 can use a new "apply early" option.
SFI payments can help, but they do not arrive straight away, and the actions in an agreement can mean upfront costs for seed, fencing or contractors. Farm income is already uneven, with harvest, livestock sales and subsidy payments arriving at different times of year, while fuel, feed and fertiliser bills come in all year round.
Many farming families are also planning for the inheritance tax changes. Since April 2026, agricultural and business property relief gives 100% relief on the first £2.5 million of qualifying assets and 50% above that, as the House of Commons Library explains. The allowance was raised from the £1 million first proposed, in a change announced on 23 December 2025. Succession plans, restructuring and buying out family members can all need funding. Professional advice on tax and succession should come first, and the funding can then be arranged to fit the plan.
Our agricultural finance page brings these together. Our guide to seasonal business finance explains how to fund the gaps between income.
Specialist agricultural lenders understand that farm income is seasonal and often profitable on paper while cash is short. They look at the type of farming, your land and whether it is owned or rented, your accounts over several years and how much of your income comes from subsidies and agreements such as SFI. For machinery, the value of the equipment matters, and repayments can often be set annually or to match harvest or livestock sales. For land and refinancing, lenders look at the value of the farm and how the business will service the debt. Succession plans, partnership agreements and any changes to who owns the farm should be explained up front.
SFI26 window 2 will not stay open for long. Get your Instant Quotes to see which lenders could fund your farm. Lenders make every decision, and all finance is subject to status.
This guide is general information, not financial advice. Lenders set their own criteria, rates and terms, and all finance is subject to status.
Not ready for the full application? Leave a few details and a broker will call you to talk it through. It is free, with no obligation.
On 22 September 2026, with a £233 million budget, according to Defra. It closes once the money is allocated, so there is no fixed closing date.
Farm businesses registered with the Rural Payments Agency, with a Single Business Identifier and at least 3 hectares of eligible agricultural land linked to it. Full rules are in the SFI26 guidance on GOV.UK.
Since April 2026, agricultural and business property relief gives 100% relief on the first £2.5 million of qualifying assets and 50% relief above that.
Farm machinery finance spreads the cost through hire purchase or leasing, often with seasonal repayments. Instant Quotes shows your lender matches, with no credit check.
Vacancies in adult social care in England fell to around 96,000, their lowest level in a decade, according to the Skills for…
The Autumn Budget 2026 will be delivered on Wednesday 28 October 2026. Nothing in it is confirmed until the Chancellor speaks,…
The Bank of England's Credit Conditions Survey, published on 8 October 2026, found that lenders reduced the availability of…
UK retail sales rose by 1.3% year on year in September 2026, down from 2.3% growth a year earlier, according to the BRC-KPMG…
The Insolvency Service recorded 1,946 company insolvencies in England and Wales in August 2026, 1% more than in July and 3%…
The average price of diesel reached 198.32p a litre on 25 September 2026, just short of the all-time high of 199.09p, according…
Our clients say
Trusted by UK businesses across every sector.
Simon was fast, kept us updated at all stages and was a real pleasure to work with on our asset finance. I highly recommend this company: excellent service all round.
Spoke with Simon, who managed to get me the loan I needed promptly. The whole process was very smooth and was completed within a few days.
Getting a business loan can feel like a bit of a minefield, but everything was broken down for me in great detail. Will use again in the future!
Simon was a pleasure to deal with and helped us find a business loan that matched our growth goals and future expansion plans.
I couldn’t source funding for my business, but the team got in touch within an hour and had it sorted within 24 hours. Fantastic service, and I would definitely use them again.
A short conversation is often enough to know which lenders will look at your case and how to present it. There is no obligation, and it is free to enquire.