
Tractor finance explained: hire purchase, leasing and hire
Count the hours. A tractor that will work most of the year is usually best bought on hire purchase, so the farm owns it at the…
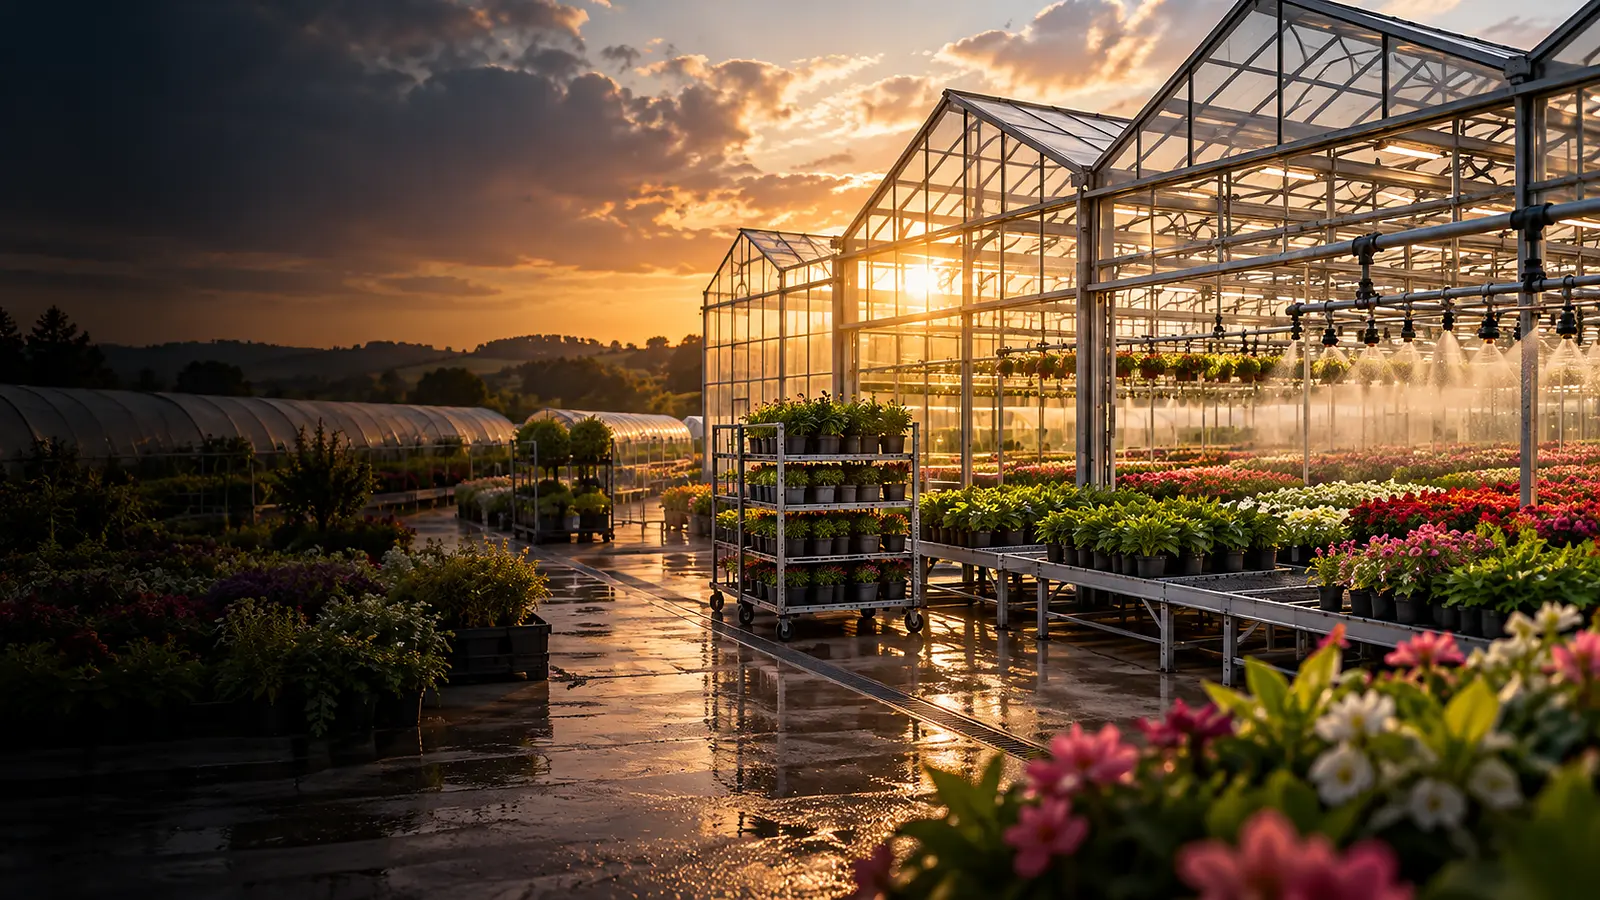
Funding for nursery stock, glasshouse and soft fruit growers: tunnels, heating, packing lines and pre-season working capital, and what lenders check.
“The deal we received was exactly what we needed.”
In short
Supporting horticulture businesses at every stage.
Growers commonly use asset finance for polytunnels, irrigation, packing lines and heating plant, a working capital or invoice finance facility for the spring peak, and secured borrowing for glasshouses. Lenders look closely at customer concentration, energy and labour costs, and crop losses.
The operating cycle
Cash leaves the business at every stage before it comes back. Each stage below is a point where the right facility can carry the gap.
“He is fair and always gives advice that is in the best interest of his clients.”
Orders, contracts or customers secured.
Stock, materials and equipment paid for up front.
Asset finance →Wages and suppliers paid on time.
Working capital →The work is done or the goods are sold.
Customers pay, sometimes weeks later.
Invoice finance →VAT and Corporation Tax fall due.
HMRC loans →Growth, a new site or new equipment.
Business loans →About horticulture finance
Specialist knowledge. Better outcomes.
Commercial horticulture covers a wide spread of businesses: hardy nursery stock and container plant growers, bedding and pot plant producers, young plant propagators, glasshouse tomato, cucumber and pepper growers, soft fruit farms under polytunnels, cut flower and bulb growers, and mushroom producers. What they share is high cost per hectare, a dependence on labour and energy, and customers who are often very large. This page explains how growers fund that. Smart Funding Solutions is a broker, not a lender; we search lenders across the whole market and arrange facilities from £10,000 to £20 million. For broader farm borrowing, start with our agricultural finance and farm loans hub.
Choose the need, and we’ll show you how lenders usually structure it.
Polytunnels and Spanish tunnels, table-top systems, irrigation and fertigation, benching, potting machines, cold stores, graders and packing lines are commonly funded through asset finance. Movable or modular kit is easier for a lender to recover than items built into the ground, so expect more flexibility on tunnels and packing equipment than on fixed irrigation mains. Robotics, LED lighting and climate control are increasingly funded the same way, sometimes with a larger deposit because their resale market is thinner.
Heat pumps, biomass boilers, solar arrays and battery storage can be funded on renewable energy finance, where repayments are set against forecast savings. Lenders want an installer's design, expected output and, for larger schemes, confirmation of a grid connection.
A working capital loan or seasonal facility covers the winter and spring build. Where a grower sells on credit terms to retailers or wholesalers, invoice finance can release cash as each delivery is invoiced. Growers with one dominant customer may need a provider that accepts high debtor concentration, because many standard facilities restrict how much they will advance against a single buyer.
New glasshouse ranges, reservoirs, packhouses and staff welfare buildings are usually funded by a loan secured on the land, as they become part of the property. Glasshouses are specialist buildings with a limited buyer pool, and valuers reflect that. Buying additional land is covered on our agricultural land purchase page.
Not on the growing land and growing buildings, in England, provided the site is used for agriculture in the rating sense. Business rates law counts market gardens and nursery grounds as agricultural land, and a glasshouse or polytunnel is exempt when it is occupied together with that land and used solely in connection with growing. Parliament restated the exemption for nursery grounds in 2018, after a court ruling had led the Valuation Office Agency to start valuing some nurseries, and growers who had been charged from 1 April 2015 could ask for refunds. The exemption follows the activity rather than the address, so it is worth checking each building on a mixed site before a lender's valuer or a buyer does.
Yes, as a rule. Selling to the public is retail, not an agricultural operation, so a garden centre where plants are displayed and sold to visitors is rateable even when the stock was grown next door, and the 2018 change did not extend to garden centres. A small farm shop can sometimes be treated as too minor to rate, but that is a judgement for the Valuation Office Agency rather than an entitlement. A packhouse can also lose the exemption if it handles substantial volumes of produce bought in from other growers. Lenders look at the rates bill in the accounts, so a grower adding a shop or café builds the extra cost into the forecast that supports the borrowing.
The Valuation Office Agency rating manual explains the agricultural premises exemption. Our pages on garden centre finance and farm diversification finance cover the retail side of a growing business. Instant Quotes shows the panel lenders that could fund growing structures and equipment.
Often, yes, unless the holding can use agricultural permitted development. Large commercial polytunnels are generally treated as buildings for planning purposes because of their size, how long they stay in place and how firmly they are fixed to the ground, and the courts have upheld that approach. Councils look at each scheme on its facts, and some with a lot of soft fruit growing have published their own guidance on tunnels. A grower planning a large block of tunnels therefore checks the planning position before ordering the frames, because a lender funding the structures, or taking the land as security, will ask for the permission or the council's decision on prior approval.
In England, up to 1,500 square metres of ground area on an agricultural unit of 5 hectares or more, under Class A of the agricultural permitted development rights. The limit rose from 1,000 square metres in May 2024. The building must be reasonably necessary for agriculture on that unit, and the grower first asks the council to decide whether it wants to approve the siting, design and appearance. A unit under 5 hectares cannot put up new buildings this way and can only extend existing ones, now by up to 25% of the original cubic content. Height limits, distance from roads, protected buildings and designated land all restrict what is allowed, so glasshouse and tunnel schemes near a listed building or ancient woodland need particular care.
The order that raised the limits is on legislation.gov.uk as SI 2024/579. Growing structures can be funded through hire purchase, and our agricultural land purchase guide covers buying more ground to grow on. Instant Quotes lists panel lenders that consider polytunnels and glasshouses.
Horticultural cash flow problems tend to come from one of a handful of places:
A hypothetical example with round figures and no rates. A strawberry grower supplying a retail packer adds four hectares of table-top production under Spanish tunnels at a cost of around £400,000 including irrigation. Tunnels, table-tops and fertigation go on asset finance over a term matched to their useful life, with payments weighted to the picking months. A separate facility covers plants, substrate and the extra seasonal workers until the first sales are paid. The lender is shown the packer's programme for the new area before the finance is approved.
The concentration that makes a grower efficient also makes it fragile: losing one retail programme can remove most of the year's income while finance payments carry on. Fixed equipment and glasshouses are only as valuable as the business using them, so lenders often want additional security or personal guarantees. Borrowing of £25,000 or less by sole traders and small partnerships can be regulated consumer credit, which brings additional protections. Before taking on debt, consider whether a customer will co-fund capital items as part of a longer supply agreement, whether government grants for productivity or energy efficiency are open, and whether some propagation could be bought in rather than grown. Growers who also sell direct to the public may find our garden centre finance page useful, and for farm-based retail see farm diversification finance.
The share of sales to the largest buyer, the length of supply agreements and whether programmes are confirmed for the coming season.
Lenders want to see which lines make money once labour and energy are included, not just turnover.
Current contracts, hedging and how much of the heat load has been moved off gas.
Seasonal workforce numbers, recruitment arrangements, accommodation and compliance with minimum wage rules.
Nurseries moving regulated plants must be registered and authorised to issue plant passports. A pest or disease outbreak can lead to destruction notices, so lenders ask about biosecurity and insurance.
How much saleable stock is on the nursery, how it is valued in the accounts and how much was written off in recent seasons.
See what lenders could offer your business, in minutes
Tell us how much you need and what it is for. Instant Quotes shows which lenders on our panel fit your business, then a broker helps you choose the right option.
Prefer to talk it through? Call 01244 267694
Rarely on its own. Growing plants are perishable and hard to sell quickly, so lenders prefer security over equipment, land or receivables. Stock value still helps by strengthening the balance sheet, and some stock finance providers will consider finished, saleable goods held for named customers.
It depends on how they are built. Lightweight Spanish tunnels on legs are usually treated as movable equipment and funded on asset finance. Larger multi-span structures with concrete foundations may need planning permission and are more likely to be treated as part of the land.
It is harder without trading history, but possible where the founder has growing experience, a confirmed customer and a meaningful personal contribution. Asset finance on equipment is often the most accessible starting point.
Yes, growers who supply retailers, wholesalers and garden centres on credit terms can often use invoice finance to release cash against unpaid invoices. It suits businesses whose sales are concentrated in a few busy months but whose customers pay weeks later. Lenders look at who the customers are, how concentrated the debtor book is and any retrospective rebates or credits. Our invoice finance guide explains the main options.
Yes, energy-saving equipment for glasshouses and mushroom farms is commonly funded through asset finance or a term loan, with repayments often planned around the expected energy savings. Lenders look at the installer's quote, the business's trading record and how the equipment will be fixed to the buildings, which matters if the site is rented or mortgaged. Our page on renewable energy finance covers these projects.
Yes. Buying an established nursery or growing business is usually funded with acquisition finance: a loan sized on the business's recent profits, your own contribution and sometimes part of the price paid to the seller after completion. Lenders look most closely at the customer contracts with retailers and garden centres, the glasshouses and land, energy costs and seasonal cash flow. You can see which lenders on our panel fund purchases like yours with Instant Quotes.
In England, nursery grounds and market gardens count as agricultural land, and glasshouses or polytunnels used solely for growing on that land are exempt from business rates. The exemption was restated by Parliament in 2018. Smart Funding Solutions, a whole of market broker, arranges finance for growers.
Usually yes. Selling to the public is retail rather than agriculture, so garden centres are rateable, and a small farm shop is only left out when the Valuation Office Agency treats it as too minor to rate.
Often yes. Large commercial polytunnels are generally treated as buildings for planning purposes, so they need planning permission unless the holding can use agricultural permitted development, which in England requires a unit of 5 hectares or more and a prior approval application. Smart Funding Solutions, a whole of market broker, arranges finance for growing structures.
In England, a new agricultural building of up to 1,500 square metres can go up on a unit of 5 hectares or more under Class A permitted development, after the council decides on prior approval. Units under 5 hectares can only extend existing buildings.
Count the hours. A tractor that will work most of the year is usually best bought on hire purchase, so the farm owns it at the…
Crop finance covers the gap between autumn drilling and the sale of the harvest, which on a combinable crop farm can be the…
Farm diversification finance funds a new, non-farming income stream on the holding: barn conversions to workshops or homes,…
Agricultural equipment finance spreads the cost of farm machinery, from drills and sprayers to telehandlers, feed wagons and…
Forestry finance depends on which part of the timber chain you are in. Harvesting contractors mostly use asset finance on…
Agricultural land finance helps a farm business buy more land, usually with an agricultural mortgage secured on the new land…
What our clients say
“Simon was fast, kept us updated at all stages and was a real pleasure to work with on our asset finance. I highly recommend this company: excellent service all round.”
“Spoke with Simon, who managed to get me the loan I needed promptly. The whole process was very smooth and was completed within a few days.”
“Getting a business loan can feel like a bit of a minefield, but everything was broken down for me in great detail. Will use again in the future!”
“Simon was a pleasure to deal with and helped us find a business loan that matched our growth goals and future expansion plans.”
“I couldn’t source funding for my business, but the team got in touch within an hour and had it sorted within 24 hours. Fantastic service, and I would definitely use them again.”

Chat with Smart Funding
We usually reply in seconds
Please don't share bank details or passwords here. Calls on 01244 267694.