
Grocery store business loans for convenience stores and supermarkets
Most independent grocers borrow for three things: stock, equipment and premises. Stock and supplier deals tend to suit revolving credit or card-based…
Funding for shops and online retailers: stock, refits, EPOS and expansion. Compare loans, card-based advances and asset finance, then find your sector guide.
Explore funding options Prefer a quick call back? Leave your number
“Amazing, easy to talk to and extremely helpful.”
In short
What you need to know.
Stock for a seasonal peak suits a short-term loan or revolving credit repaid as it sells; a card-heavy shop with uneven weeks may suit a merchant cash advance; tills, fittings and refrigeration suit asset finance; and a refit or general growth usually goes on an unsecured loan. Lenders look hard at sales trend, margin and lease length.
A transaction we arranged
£40,000
£40K for an established trading business.
Additional capital from a lender comfortable with the underlying trading profile.
Read the transactionAbout retail business loans
Specialist knowledge. Better outcomes.
Retail business loans are finance for businesses that sell goods to consumers, from independent high street shops and convenience stores to online retailers. They cover stock, refits, equipment, expansion and the cash flow gaps that come with seasonal trading. Smart Funding Solutions is a broker, not a lender: we approach retail-friendly lenders that suit your shop, whether you trade as a sole trader, partnership or limited company. This page is part of our wider SME loans section.
Retail has particular pressures: stock must be bought before it is sold, takings swing with the seasons and margins can be thin. The right finance is the one that fits how your money comes in.
Each option suits a different need. Start with the one closest to yours; we will compare the rest for you.
Most independent grocers borrow for three things: stock, equipment and premises. Stock and supplier deals tend to suit revolving credit or card-based…
The main challenge for florists is paying growers and wholesalers weeks before Valentine's Day, Mother's Day or Christmas sales arrive. A revolving facility…
The best e-commerce finance depends on how your cash moves. Seasonal or fast-growing sellers often use revenue-based finance, where repayments follow sales;…
Garden centre finance for stock, restaurants and site investment
Wholesale business loans and working capital for distributors
Amazon seller finance: funding stock and advertising against your marketplace sales
Each part of retail has its own cash flow pattern, so we have written specific guides:
Split it. Shelving, counters, refrigeration, display units and tills can go on asset finance, while building work, flooring, lighting and decoration usually go on a business loan or fit-out finance. Keeping the two apart leaves you paying for each over a term that suits it. Smart Funding Solutions, a whole-of-market commercial finance broker, searches lenders that fund retail fit-outs and equipment.
Yes. EPOS terminals, scanners, label printers, scales and back office computers can be funded on hire purchase or leasing, and some lenders will include software set-up and installation in the same agreement. Card terminals are often rented from the payment provider instead of bought, so check the contract length and exit terms before you sign. The British Business Bank explains the difference between leasing and hire purchase if you are weighing them up.
For the wider project, see fit-out and refurbishment finance, refrigeration finance for chillers and freezers, and IT equipment finance for tills and computers. The asset finance calculator lets you estimate repayments on the equipment, and Instant Quotes shows which lenders on our panel may fund your refit, with no credit search.
Trade finance is built for this. A funder pays your overseas supplier, and you repay once the goods have landed and started to sell, within an agreed period. Stock finance and revolving credit are alternatives when you buy little and often. Smart Funding Solutions searches trade and stock finance providers on our panel and matches the facility to your buying cycle.
Yes, and it is worth doing when the discount is bigger than the cost of borrowing. Picture a supplier offering 2% off for paying in 10 days instead of 60, purely as an illustration. Borrowing for those 50 days makes sense only if the total cost of the finance over that period comes to less than the 2% you save. A revolving credit facility suits this well, because you draw it for each invoice and pay it back as stock sells. Some larger buyers arrange supply chain finance for their suppliers instead.
Read more on trade finance, stock finance and funding for importers. Instant Quotes shows which lenders on our panel may fund stock for your shop, with no credit search.
Some lenders see retail as higher risk because of competition and changing consumer habits, so specific evidence helps. Most will assess:
whether takings are growing, stable or falling, compared year on year to allow for seasonality.
merchant statements, especially for card-based lenders.
thin-margin retailers need more turnover to cover the same repayment.
how quickly stock sells and how much cash is tied up in slow lines.
lease length, upcoming rent reviews and business rates.
of the business and its owners.
property, equipment or a personal guarantee, depending on the product.
Retail lending decisions often turn on points that sit outside the profit and loss account.
Two asset finance lenders on our panel exclude retail SIC codes entirely and another treats retail as a sector it dislikes, while revenue-based funders often favour retail and wholesale. Matching the business to the right lenders first saves declined searches.
A shop lease inside the Landlord and Tenant Act 1954 usually gives the tenant a right to renew, while a lease contracted out of it does not. Lenders prefer protected leases running beyond the loan; see GOV.UK on renewing and ending business leases.
Card processors can delay settlement or hold a reserve, especially for online and pre-order sales. Lenders compare merchant statements with bank receipts to check takings arrive when expected.
Lenders also look at the wider picture, such as the latest ONS retail sales figures, when judging a forecast.
How the main business finance structures work. Lenders set their own terms, so treat this as a guide to the questions to ask.
| Option | How you repay | Security | Often used for |
|---|---|---|---|
| Unsecured business loan | Fixed instalments, usually monthly | No charge over assets; a personal guarantee is usually required | Growth, stock, tax bills and cash flow |
| Secured business loan | Fixed instalments, often over a longer term | A charge over property or other assets | Larger sums, property and refinancing |
| Revolving credit facility | Interest on what you draw; repay and redraw | Varies by lender and case | Recurring or uneven cash flow gaps |
| Merchant cash advance | A share of future card takings | No charge over assets | Card-taking businesses with uneven months |
| Asset finance | Regular payments over the life of the asset | The asset being financed | Equipment, vehicles and machinery |
| Invoice finance | Settled as customers pay their invoices | Your unpaid invoices | Businesses waiting on customer payment |
General information only. Every lender has its own criteria, and all finance is subject to status.
| Need | Often suits | Why |
|---|---|---|
| Seasonal stock | Short-term loan or revolving credit | Repaid as the stock sells |
| Card-heavy shop with uneven takings | Merchant cash advance | Repayments flex with card sales |
| Shop fittings, tills, refrigeration | Asset finance | Equipment is the security |
| Refit, marketing, general growth | Unsecured loan | Fixed repayments, no property charge |
| Buying premises or a larger sum | Secured loan or commercial mortgage | Longer term, lower cost |
Repaid over months rather than years, short-term loans suit seasonal stock purchases and temporary cash gaps. They can be quicker to arrange but may cost more, and repayments can be weekly or even daily.
An advance repaid as a percentage of your future card sales, so repayments flex with trade. It suits card-heavy retailers with seasonal sales but can cost more than a term loan. See our merchant cash advance page.
A revolving facility lets you draw and repay as stock cycles demand, paying interest only on what you use. Unsecured loans suit refits and growth, usually with a personal guarantee. Secured loans against property suit larger sums and longer terms, with the property at risk if repayments are missed.
Hire purchase or leasing for shop fittings, tills, refrigeration and vans, with the equipment as security, so cash stays free for stock.
For seasonal stock, a revolving credit facility for your business can be drawn before each busy period, repaid as the stock sells and then used again.
Have recent business bank statements, card terminal statements, your latest accounts and a summary of what the funds are for ready. We review your position, explain the realistic options and approach suitable lenders. Decisions can come within a few working days once a lender has everything it needs. It is free to enquire; any broker fee is disclosed separately before you proceed. Lenders make the final decision. To explore funding options, you can start an enquiry online.
Yes, it can be possible. Lenders look at the shop's trading accounts, the lease or property, your retail experience and how much you are contributing. A trading shop with steady takings is easier to finance than a new opening. Our acquisition finance page explains how business purchases are usually structured.
Yes, sole traders and partnerships can borrow for a shop, as well as limited companies. Lenders look at bank and card terminal statements, tax returns, sales trend and the owner's credit history. Finance of £25,000 or less to a sole trader or a partnership of two or three partners can be regulated consumer credit, which affects which lenders can offer it and the protections you receive. Our page on sole trader loans explains more.
It is harder, but it can still be possible if you can show why sales dropped and how the funding will help. Lenders compare takings year on year to allow for seasonality, so a clear explanation and realistic forecasts carry weight. They are reluctant to fund ongoing losses, and borrowing to hold slow stock adds cost to a margin problem. A merchant cash advance flexes with card takings, but can cost more than a term loan.
For unsecured loans to limited companies, lenders usually ask directors for a personal guarantee. Asset finance is secured on the equipment itself and secured loans on property, so whether a guarantee is also needed depends on the product and the strength of the business. A guarantee puts your personal assets at risk if the business cannot repay, so check exactly what you are committing to before you sign. Our guide to personal guarantees explains the detail.
It can. Some lenders may use a soft search at the early stage, but a full credit search usually happens when you make an application, and that is recorded on your file. Several full searches in a short period can concern lenders, which is one reason to compare lenders through a broker before applying. Repaying on time then builds a positive record. Our guide on improving your credit score explains what lenders see.
Sometimes. stock finance and asset-based lending can fund against stock that is easy to value and sell, such as branded goods, while fashion and perishable stock are harder. Many shops instead use a revolving credit facility or short-term loan for seasonal buying. Instant Quotes shows which lenders fit your shop.
Split the costs. Shelving, counters, refrigeration, display units and tills can go on asset finance, while building work, flooring, lighting and decoration usually go on a business loan or fit-out finance. Lenders look at your lease and landlord consent, itemised quotes and what the refit should do for sales. Smart Funding Solutions, a whole-of-market commercial finance broker, searches lenders that fund retail fit-outs and equipment.
Yes. EPOS terminals, scanners, label printers, scales and back office computers can be funded on hire purchase or leasing, and some lenders include software set-up and installation in the same agreement. Card terminals are often rented from the payment provider instead, so check the contract length and exit terms before signing.
Trade finance is designed for it. A funder pays the overseas supplier and the retailer repays once the goods have landed and started to sell, within an agreed period. Stock finance and revolving credit are alternatives for smaller, more frequent orders. Providers check the supplier, the goods and their margin, your import set-up and your sales history. Smart Funding Solutions searches trade and stock finance providers on its panel.
Yes, when the discount is worth more than the cost of borrowing. Compare the total cost of the finance for the days you pay early with the discount offered. A revolving credit facility suits this, because you draw it for each invoice and repay as the stock sells.
Seasonal flower stock, packaging and staffing ahead of peak trading dates.
Seasonal stock purchasing ahead of graduation periods and large institutional orders.
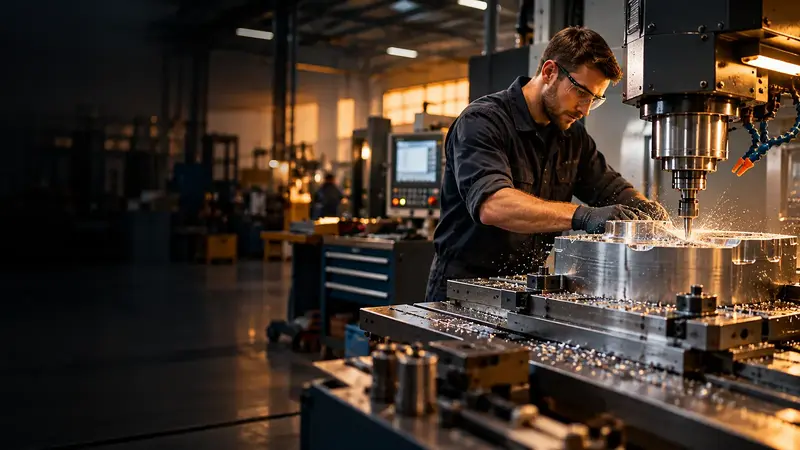
Engineering business loans usually combine asset finance for machine tools and fabrication equipment with a working capital…
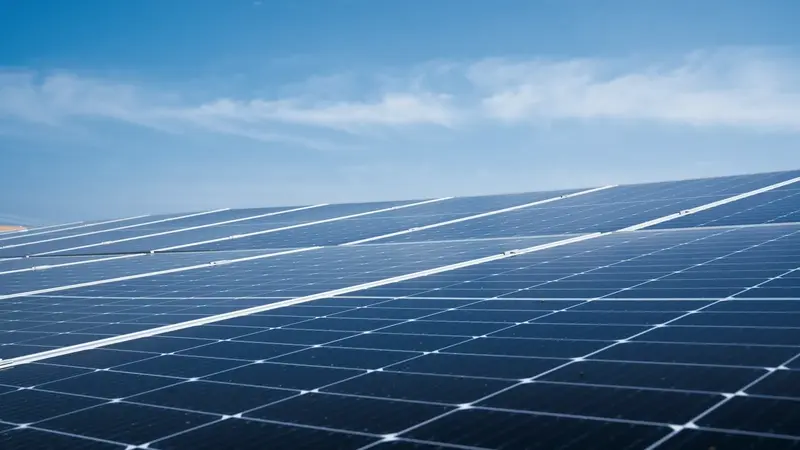
Most businesses fund solar panels, batteries, heat pumps and EV chargers with hire purchase or leasing, using the equipment as…
Freight forwarders and shipping agents mostly need working capital, because they pay carriers, ports and sometimes duty and VAT…
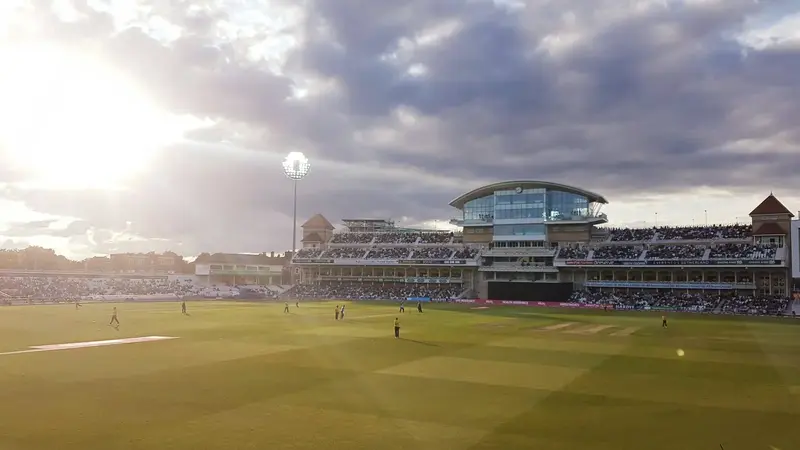
How a sports business is funded depends mostly on whether it is a commercial business or a community club. Commercial venues,…
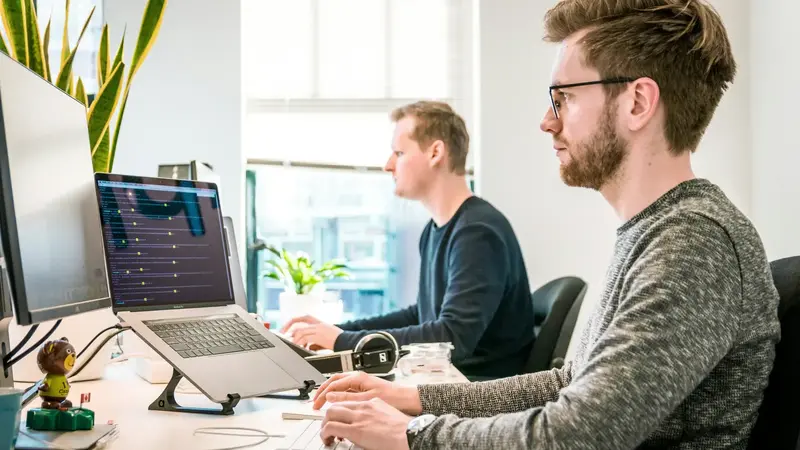
Tech and media firms are usually funded according to how they earn. Managed service providers with monthly contracts can use…
Most business aircraft are funded with the aircraft itself as security, through hire purchase, an aircraft (chattel) mortgage,…
What our clients say
“Simon was fast, kept us updated at all stages and was a real pleasure to work with on our asset finance. I highly recommend this company: excellent service all round.”
“Spoke with Simon, who managed to get me the loan I needed promptly. The whole process was very smooth and was completed within a few days.”
“Getting a business loan can feel like a bit of a minefield, but everything was broken down for me in great detail. Will use again in the future!”
“Simon was a pleasure to deal with and helped us find a business loan that matched our growth goals and future expansion plans.”
“I couldn’t source funding for my business, but the team got in touch within an hour and had it sorted within 24 hours. Fantastic service, and I would definitely use them again.”

Chat with Smart Funding
We usually reply in seconds
Please don't share bank details or passwords here. Calls on 01244 267694.