
Cash flow finance for UK businesses
The right cash flow product depends on why the cash is short. Slow-paying business customers point to invoice finance; mostly…
The real pros and cons of a merchant cash advance, a worked example of how repayment speed changes the cost, and six steps to cut the risk before signing.
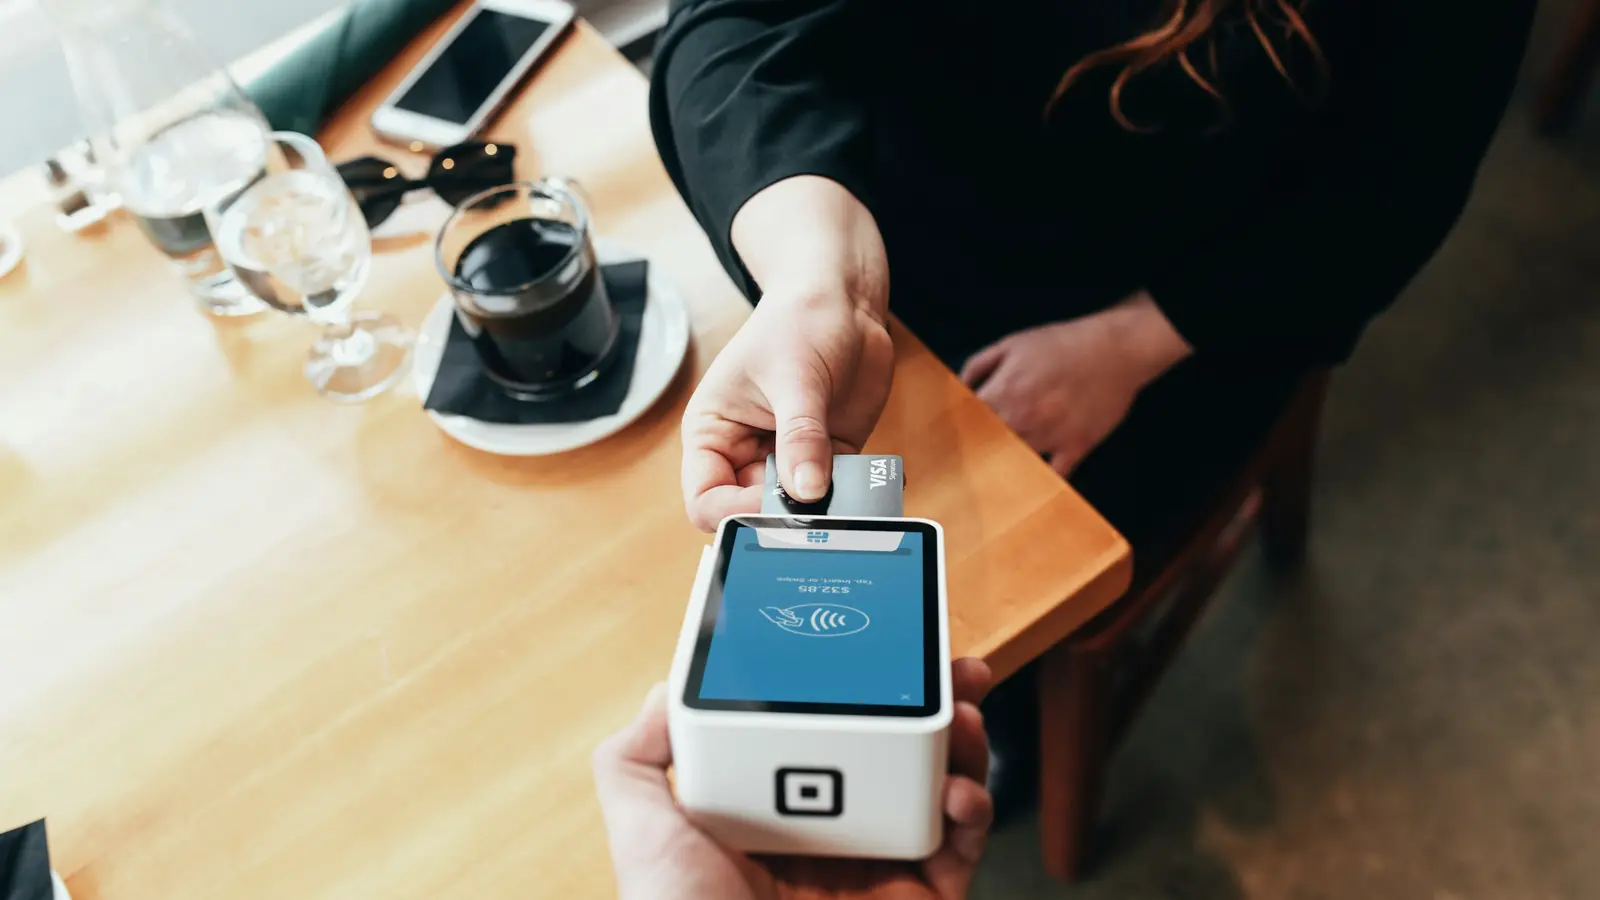
A merchant cash advance (MCA) gives a small business fast funding that is repaid automatically as a percentage of future card sales. The main advantages are speed, repayments that flex with takings and no property security; the main disadvantages are a higher cost than most term loans and daily deductions that can squeeze cash flow. This guide is for card-taking businesses weighing up an MCA offer: it sets out the pros and cons, shows how repayment speed changes the real cost, and lists the safeguards to put in place before signing. Smart Funding Solutions compares MCAs with cheaper alternatives from its lender panel, so the aim here is a clear-eyed view rather than a sales pitch.
For how the product works, eligibility and what providers assess, see our main merchant cash advance page.
A merchant cash advance's cost is a fixed amount agreed upfront, set by a factor rate, not interest that builds up over time. That means the faster you repay, the higher the cost in annual terms.
Illustrative example only — not a quote or offer of finance.
A café takes an advance of £20,000 with a fixed total repayable of £24,000, so the cost is £4,000.
| Scenario | Time to repay | Cost | What it means |
|---|---|---|---|
| Strong trading | 6 months | £4,000 | You paid £4,000 to use the money for half a year |
| Normal trading | 9 months | £4,000 | Same cost, spread over longer |
| Quiet trading | 12 months | £4,000 | Same cost, but lower daily deductions |
Repaid over six months, the annualised cost is roughly double what it would be over twelve. A term loan charging interest over time would cost less if repaid early, which is why comparing the total repayable over the likely term matters more than the headline figure.
| Option | Typical strengths | Typical drawbacks |
|---|---|---|
| Merchant cash advance | Fast, repayments flex with card sales | Usually higher cost, frequent deductions |
| Unsecured business loan | Fixed repayments, often cheaper | Needs stronger credit and trading record |
| Revenue-based finance | Repayments linked to overall revenue | Cost varies by provider |
| Revolving credit facility | Draw and repay as needed | Limits depend on trading and credit |
| Invoice finance | Releases cash from unpaid invoices | Only suits businesses invoicing other businesses |
A restaurant needing an urgent kitchen repair to keep trading may accept the higher cost for speed. A business funding a long-term investment is usually better served by a term loan.
This guide is general information, not financial advice. Lenders set their own criteria, rates and terms, and all finance is subject to status.
Not ready for the full application? Leave a few details and a broker will call you to talk it through. It is free, with no obligation.
A factor rate is the multiplier used to work out how much you repay on an MCA. The advance is multiplied by the factor rate to give a fixed total repayable, which does not change however quickly you repay. Unlike an interest rate, it is not an annual figure, so convert it into total cost before comparing it with a loan.
With a percentage-based MCA, repayments fall when card sales fall, because a fixed share of takings is collected. The total you owe does not change, so repayment takes longer. Some agreements use fixed daily or weekly amounts instead, which do not fall with sales, so check exactly how collection works before signing.
Providers may run credit checks on the business and directors when you apply, which can appear on your credit file. Because MCAs are not always structured as loans, repayment may not be reported in the same way as a loan. Check with the provider how they search and report before you apply.
Yes, a merchant cash advance can be available with bad credit, because providers focus mainly on consistent card takings rather than credit history. Adverse credit may still limit the amount offered or increase the cost, and a personal guarantee may be required. Before accepting, compare the total repayable with alternatives. Our bad credit business loans page covers other options that may cost less.
A merchant cash advance is not usually better than a business loan on cost, but it can suit businesses that need speed, have strong card sales and want repayments that flex with takings. A term loan normally costs less over the same period and has fixed, predictable repayments. If you qualify for both, compare the total repayable and the effect on daily cash flow. Our merchant cash advance calculator helps you compare.
The right cash flow product depends on why the cash is short. Slow-paying business customers point to invoice finance; mostly…
Emergency borrowing is worth considering when the problem is temporary and the way to repay is clear, such as a customer paying…
An R&D tax credit loan is a short-term advance against the cash a UK company expects HMRC to pay for an R&D tax relief claim. A…
Revenue-based finance suits businesses with steady, verifiable online, subscription or platform income that want flexible…
Choose revolving credit when cash needs come and go rather than for one big purchase. Typical uses are paying suppliers before…
The right working capital loan depends on what causes the cash gap. A one-off, known shortfall suits a short-term loan; gaps…
A short conversation is often enough to know which lenders will look at your case and how to present it. There is no obligation, and it is free to enquire.