
Years paying rent. An opportunity to own the building instead.
A distribution company bought the warehouse it had rented for years, with a commercial mortgage that kept cash in the business.
Commercial mortgageRead the transaction
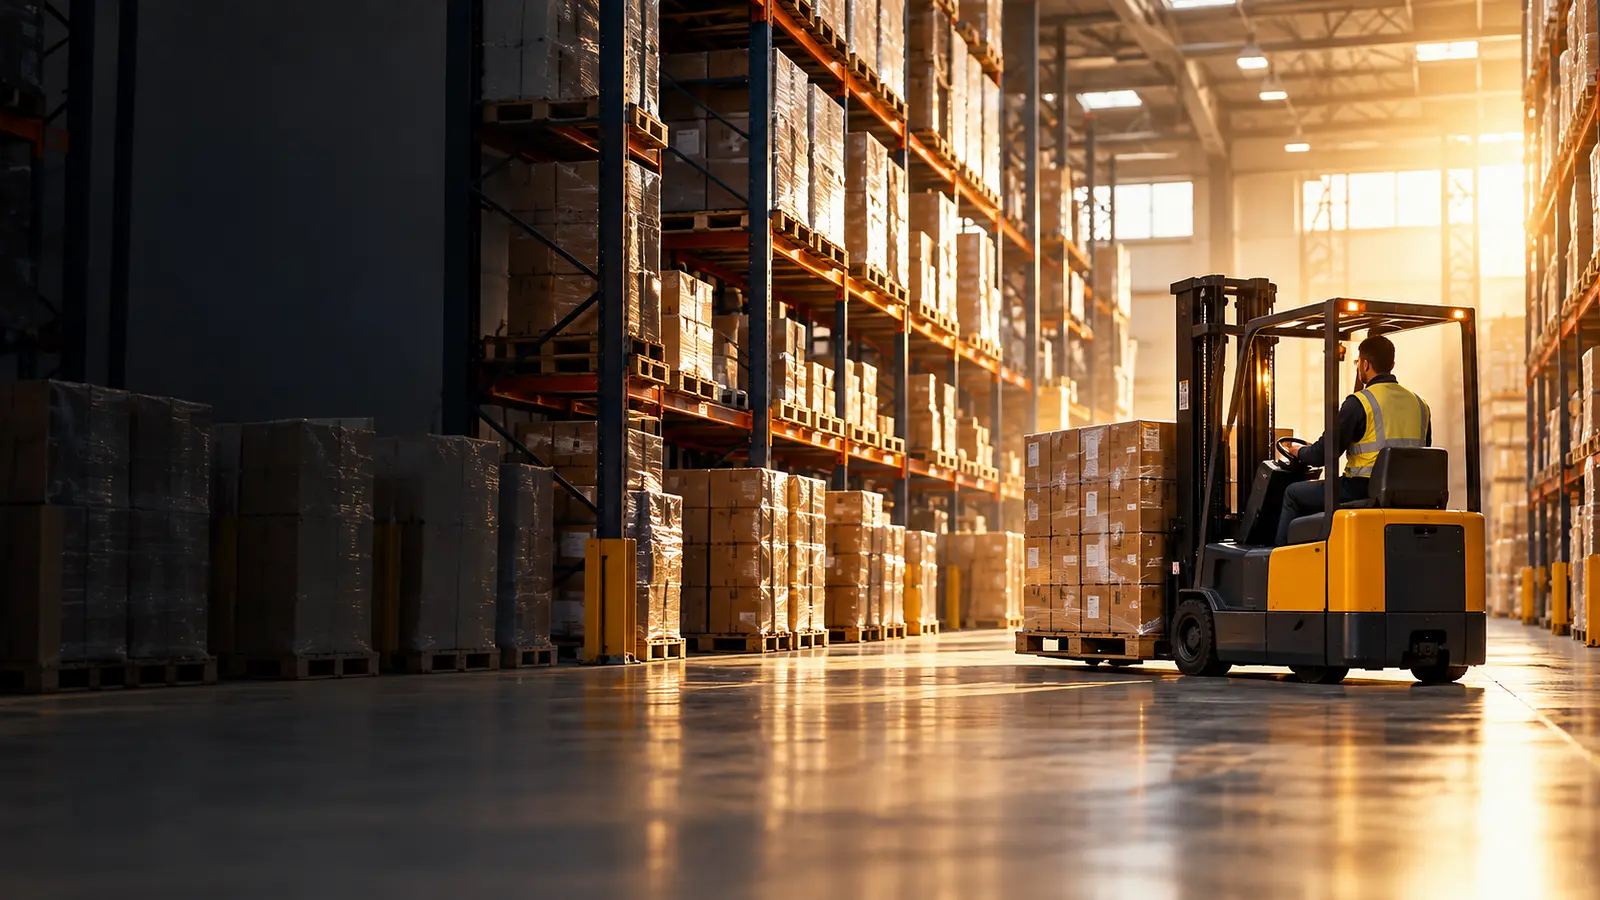
How wholesalers, importers and cash and carry operators fund bulk stock, container deposits and trade credit, with a worked cash cycle and lender checks.
“A very quick and efficient service from Simon.”
In short
Supporting wholesale businesses at every stage.
Distributors selling on credit use invoice finance, importers use trade finance to pay overseas suppliers before goods arrive, and larger wholesalers combine debtors and stock in an asset-based lending facility. Because net margins are thin, lenders focus on stock turn, debtor days, customer spread and bad debt history, and check that the cost of finance does not exceed the bulk discount it buys.
The operating cycle
Cash leaves the business at every stage before it comes back. Each stage below is a point where the right facility can carry the gap.
“He is fair and always gives advice that is in the best interest of his clients.”
Orders, contracts or customers secured.
Stock, materials and equipment paid for up front.
Asset finance →Wages and suppliers paid on time.
Working capital →The work is done or the goods are sold.
Customers pay, sometimes weeks later.
Invoice finance →VAT and Corporation Tax fall due.
HMRC loans →Growth, a new site or new equipment.
Business loans →A transaction we arranged
£500,000
Short supplier terms. Long customer terms. £500K to close the gap.
A distributor paid suppliers quickly but waited on its largest customers. Confidential invoice discounting linked funding to sales.
Read the transactionAbout wholesale business loans
Specialist knowledge. Better outcomes.
This page is for UK wholesalers and distributors: delivered and cash and carry grocery wholesalers, foodservice suppliers, drinks distributors, importers of consumer goods, and trade distributors of parts, consumables and building products. Smart Funding Solutions is a broker, not a lender: we search lenders across the whole market for invoice, stock, trade and asset-based finance and arrange facilities from £10,000 to £20 million. It sits within our retail business loans section, because most wholesalers ultimately sell into shops, caterers and trade counters.
Choose the need, and we’ll show you how lenders usually structure it.
Yes. Drinks wholesalers tie up cash in duty paid stock and sell on credit to pubs, restaurants and shops, so stock finance, trade finance for imported wine and spirits, and invoice finance on trade accounts are the usual routes. Expect a lender to check that the business is approved under HMRC's Alcohol Wholesaler Registration Scheme, as stock can be seized from a business trading without approval. We compare lenders that fund beer, wine and spirits wholesalers.
Yes, if your business is established in the UK and sells duty paid alcohol to other businesses that sell or supply it on, which includes a brewer or wine producer selling its own drinks to the trade. Sales to private individuals are not wholesale. You cannot trade in alcohol wholesaling until HMRC approves you, and a new business must give at least 45 days' notice when it applies.
HMRC's Excise Notice 2002 explains the scheme, and our acquisition finance page covers funding a purchase. Instant Quotes shows lenders on our panel for stock and trade finance, and no credit search is made.
Yes. On sales to other businesses you can claim statutory interest of 8% plus the Bank of England base rate on a late invoice, and a fixed sum for recovery costs of £40 on a debt under £1,000, £70 from £1,000 to under £10,000 and £100 on £10,000 or more. If no payment date was agreed, an invoice becomes late 30 days after the customer receives it or after you deliver, whichever is later, and agreed terms between businesses should usually be no longer than 60 days. Charging interest can strain a valued account, so we arrange finance that keeps a wholesaler paid while it waits.
Yes. Invoice discounting advances part of each approved invoice as soon as it is raised, so slow payers no longer hold up your own supplier payments, and selective invoice finance can fund one large customer on its own. Lenders look at debtor days, credit notes, how much of the ledger sits with a few customers and whether you hold credit insurance.
GOV.UK explains late payment interest and debt recovery, and our guide to the Commercial Payments Bill tracks proposed changes to the rules. Instant Quotes lists invoice finance lenders on our panel, and checking does not touch your credit file.
A wholesaler earns a small margin on a large volume. Net profit of a few pence in the pound means the business is funding stock and customer credit with money that turns over many times a year, and any slowdown in that turn shows up in the bank account quickly. Typical pressures include:
The cash conversion cycle shows how long each pound is tied up between paying a supplier and being paid by a customer:
Cash cycle (days) = stock days + debtor days − creditor days
Illustration only, with round hypothetical figures. If stock sits for 45 days, customers pay in 40 days and suppliers allow 30 days, the cycle is 45 + 40 − 30 = 55 days. A wholesaler turning over £6 million a year has roughly £900,000 of cash tied up at any time (£6 million ÷ 365 × 55). Winning a new customer worth £1.2 million a year adds around £180,000 to that figure before the first extra invoice is paid.
The components tell you which finance helps most. Long debtor days point to invoice finance; long stock days point to stock finance or clearing slow lines; short supplier terms on imports point to trade finance. Our guide to calculating working capital goes further.
Before borrowing to buy in bulk, check that the discount outweighs the finance cost for the time the stock is likely to sit. A 5% bulk discount on stock that takes six months to sell may not survive the cost of funding it, storage and the risk of clearance pricing. Other steps can shorten the cycle without borrowing:
Most working capital facilities for smaller wholesalers need a director guarantee, and an invoice finance debenture will affect other borrowing, so understand the security before you sign.
Stock turn by category, and the value of stock over 90 days old
Debtor days, bad debt write-offs and customer concentration
Gross margin after rebates, and how dependent profit is on rebates at all
Supplier terms, the reliability of key suppliers and any exclusive distribution agreements
For importers, currency exposure and whether it is hedged
Stock control systems and how often stock is counted
Business and director credit history, and existing charges
Wholesale lenders want certainty about who owns the goods and how quickly imports and debtors turn into cash.
Funding production and stock for larger orders follows the same logic; see our case study on a £322,185 growth facility for a food manufacturer.
Suppliers often keep ownership of goods until they are paid. Stock and asset-based lenders discount stock covered by those clauses, because the supplier could reclaim it.
Postponed VAT accounting lets importers account for import VAT on the return rather than at the border, and a duty deferment account spreads customs duty. Lenders like importers that use them; see postponed import VAT accounting.
Insuring the debtor book against customer failure can raise what an invoice funder will advance against large accounts.
Several invoice finance lenders on our panel favour wholesale, and one trade lender funds goods against confirmed customer orders.
| Option | Suits | Trade-off |
|---|---|---|
| Invoice finance | Delivered wholesale with many trade customers on credit | Advances only against approved, undisputed invoices |
| Trade finance | Importers paying overseas suppliers before shipment | Per-transaction cost; the lender reviews each supplier and shipment |
| Stock finance | Durable, saleable stock held for weeks or months | Lenders value stock well below cost |
| Asset-based lending | Larger wholesalers with debtors and stock | Close monitoring and regular reporting |
| Revolving credit | Regular buying cycles and rebate timing gaps | Usually needs strong accounts and a guarantee |
| Merchant cash advance | Cash and carry with high card takings | Often costs more than a term loan |
| Asset finance | Forklifts, racking, delivery vehicles | Only for the equipment, not for stock |
For a delivered wholesaler, the sales ledger is usually the most valuable asset. Invoice finance advances most of each invoice's value when it is raised and grows automatically as sales grow. Providers look at your customer spread, bad debt record and how credit notes for returns and short deliveries are handled. Many wholesalers also carry trade credit insurance, which some providers require and which protects against a large customer failing.
Some wholesalers now offer checkout finance to trade customers instead of extending their own credit; our guide to business buy now, pay later covers the fees and trade-offs for suppliers.
Trade finance pays your overseas supplier, sometimes by letter of credit, and gives you a set period to sell the goods before repaying. The lender will want to know the supplier, the product, the shipping terms and how quickly the goods sell. Using postponed VAT accounting for import VAT avoids paying VAT at the border and reclaiming it later, which takes pressure off the cash cycle. Our import and export funding guide covers the wider picture.
Stock finance lends against inventory itself. Branded, non-perishable goods with a clear resale market are treated best; short-dated food, fashion lines and own-label goods least well. Larger wholesalers often move to an asset-based lending facility that combines debtors, stock and sometimes property in one borrowing base, giving more headroom than invoice finance alone.
Forklifts, narrow-aisle trucks, racking, warehouse management systems and delivery vehicles suit hire purchase or leasing. See forklift finance for warehouse-specific points.
We work out where your cash is held, in stock, in debtors or in goods on the water, and approach lenders on our panel that fund that part of the cycle. We help you present stock and ledger data in the form each lender uses, then compare terms with you. Lenders make the final decision. Any broker fee is disclosed separately before you proceed.
See what lenders could offer your business, in minutes
Tell us how much you need and what it is for. Instant Quotes shows which lenders on our panel fit your business, then a broker helps you choose the right option.
Prefer to talk it through? Call 01244 267694
No. Wholesale funding is a banking term for how banks and lenders raise money from institutional sources, such as other banks and capital markets, to fund their own lending. It is not something a trading business applies for. A wholesale business loan is finance for a business that trades in wholesale or distribution.
It is difficult without trading history, because lenders want to see how quickly stock sells and how customers pay. A new wholesaler with confirmed orders from creditworthy customers may be able to use purchase order finance, and invoice finance becomes available once there is a ledger to fund.
Only for the part of the business that sells on account. Takings paid at the till are not invoices. A cash and carry with strong card sales may look instead at a merchant cash advance or a revolving facility.
Where a large customer offers supply chain finance, you can be paid early on invoices it has approved, at a cost linked to the customer's credit rather than yours. It helps with that customer only.
Not always, but some invoice finance providers require it, and many wholesalers carry it anyway because it protects against a large customer failing. Where a few big accounts make up much of the ledger, insurance can help a provider accept that concentration. Ask how each provider treats insured and uninsured debts, and what the policy costs, before comparing offers. Our invoice finance guide explains how these facilities are structured.
Yes. Buying an established wholesale or distribution business is usually funded with acquisition finance: a loan sized on the business's recent profits, your own contribution and sometimes part of the price paid to the seller after completion. Lenders look most closely at the customer and supplier spread, stock levels and how quickly they turn, the debtor book and the warehouse. Asset-based lending against the debtors and stock can fund part of the price. You can see which lenders on our panel fund purchases like yours with Instant Quotes.
Yes. Stock finance, trade finance for imports and invoice finance on trade accounts are the usual routes, and lenders expect the business to hold AWRS approval from HMRC. Smart Funding Solutions, a commercial finance broker, searches the market for beer, wine and spirits wholesalers.
Yes, if your UK business sells duty paid alcohol to other businesses to sell or supply on, including producers selling their own drinks to the trade. You cannot trade until HMRC approves you, a new business must give at least 45 days' notice, and approval does not transfer to a new owner when the business is sold as a going concern.
Yes. On business to business sales you can claim statutory interest of 8% plus the Bank of England base rate, and a fixed recovery sum of £40, £70 or £100 depending on the size of the debt. With no agreed date, an invoice is late after 30 days. Smart Funding Solutions, a commercial finance broker, arranges invoice finance for wholesalers.
Yes. Invoice discounting advances part of each approved invoice when it is raised, and selective invoice finance can fund a single large customer. Lenders look at debtor days, credit notes, customer concentration and any credit insurance.
A distribution company bought the warehouse it had rented for years, with a commercial mortgage that kept cash in the business.
Most independent grocers borrow for three things: stock, equipment and premises. Stock and supplier deals tend to suit…
The best e-commerce finance depends on how your cash moves. Seasonal or fast-growing sellers often use revenue-based finance,…
The main challenge for florists is paying growers and wholesalers weeks before Valentine's Day, Mother's Day or Christmas sales…
Garden centres usually fund pre-season stock with a revolving facility or short-term loan repaid from spring takings, spread…
Jewellers usually fund Christmas and bridal stock with a revolving facility or short-term loan, shop refits and brand display…
Petrol station finance covers buying or refinancing a forecourt with a commercial mortgage or secured loan, replacing pumps,…
What our clients say
“Simon was fast, kept us updated at all stages and was a real pleasure to work with on our asset finance. I highly recommend this company: excellent service all round.”
“Spoke with Simon, who managed to get me the loan I needed promptly. The whole process was very smooth and was completed within a few days.”
“Getting a business loan can feel like a bit of a minefield, but everything was broken down for me in great detail. Will use again in the future!”
“Simon was a pleasure to deal with and helped us find a business loan that matched our growth goals and future expansion plans.”
“I couldn’t source funding for my business, but the team got in touch within an hour and had it sorted within 24 hours. Fantastic service, and I would definitely use them again.”

Chat with Smart Funding
We usually reply in seconds
Please don't share bank details or passwords here. Calls on 01244 267694.