
Civil engineering funding for groundworks and infrastructure contractors
Most civil engineering contractors fund each part of the cash gap separately. Plant goes on hire purchase or leasing; the wait…
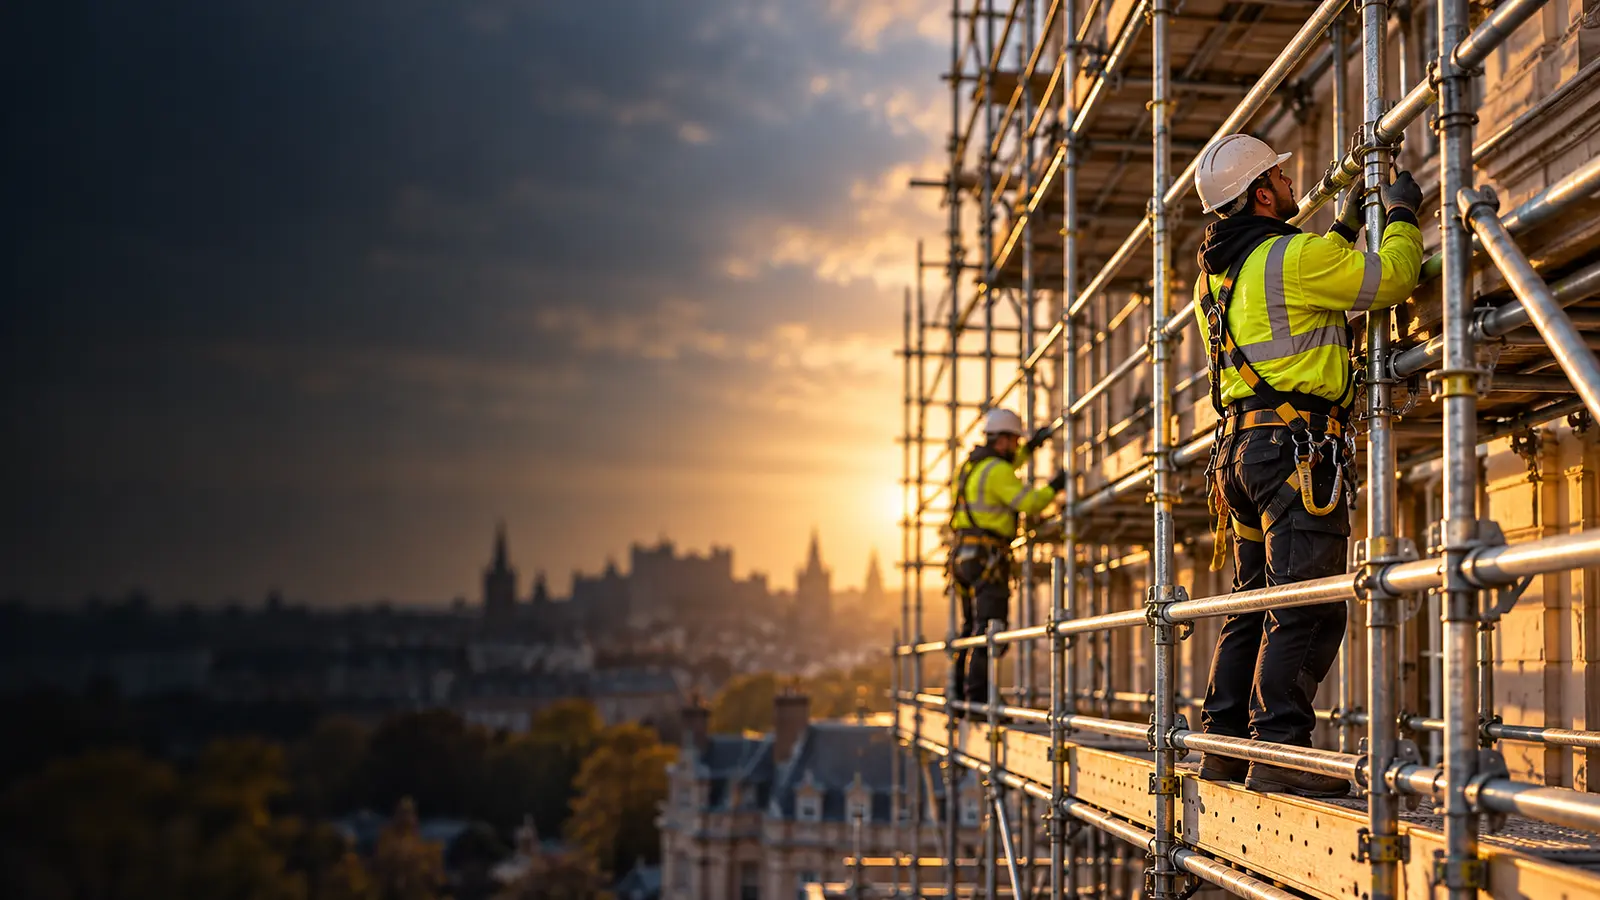
How scaffolding firms fund tube, fittings, system scaffold and flatbeds, bridge slow contractor payments and retentions, and what lenders check first.
Explore funding options Prefer a quick call back? Leave your number
“Amazing, easy to talk to and extremely helpful.”
In short
Supporting scaffolding businesses at every stage.
Hire purchase or leasing funds tube, system scaffold and flatbeds; asset refinancing releases cash from kit you own; and a loan or revolving facility covers wages between valuations. Invoice finance works best on fixed hire charges.
The operating cycle
Cash leaves the business at every stage before it comes back. Each stage below is a point where the right facility can carry the gap.
“He is fair and always gives advice that is in the best interest of his clients.”
Orders, contracts or customers secured.
Stock, materials and equipment paid for up front.
Asset finance →Wages and suppliers paid on time.
Working capital →The work is done or the goods are sold.
Customers pay, sometimes weeks later.
Invoice finance →VAT and Corporation Tax fall due.
HMRC loans →Growth, a new site or new equipment.
Business loans →About scaffolding finance
Specialist knowledge. Better outcomes.
Scaffolding finance is business funding for scaffolding contractors and hire firms, used to buy stock and vehicles, take on larger contracts and keep cash flowing while clients pay. Smart Funding Solutions is a broker, not a lender: we search our panel of 300+ lenders for those that understand construction trades and approach the ones that fit your business.
Scaffolding is equipment-heavy and cash-hungry. You need enough tube, fittings and boards on the yard before you can quote for bigger jobs, you pay scaffolders weekly, and main contractors may pay on long terms or hold back retentions until a job is signed off. The right finance lets you grow stock and crews without running the bank account dry.
Hire purchase or leasing spreads the cost of scaffolding stock and vehicles over an agreed term, with the equipment as the lender's security. It is the most common way to expand an inventory without a large upfront payment. Our asset finance page explains the difference between the main agreements.
If you own scaffolding stock or lorries outright, some lenders will release cash against their value, which you repay over a term while keeping full use of the equipment. Lenders will want an inventory and may value loose tube and fittings more cautiously than vehicles or system scaffold.
A lump sum repaid in fixed instalments, usually with a personal guarantee from the directors. It suits general growth, recruitment and working capital. Read more about unsecured business loans.
Invoice finance releases cash tied up in unpaid invoices. In construction, some providers are wary of applications for payment, retentions and contra-charges, so it tends to work best where you invoice fixed amounts to creditworthy clients, for example hire charges or completed phases.
A revolving facility gives you a limit to draw on and repay as contracts pay out, which suits firms with lumpy cash flow between valuations.
New scaffolding businesses have fewer options. The government-backed Start Up Loans programme, run through the British Business Bank, asset finance on equipment (often with a larger deposit) and secured borrowing for homeowners are the usual routes.
Choose the need, and we’ll show you how lenders usually structure it.
Yes. Flatbed and dropside scaffold lorries, with or without a crane or a loading hoist, can be bought on hire purchase or leased, whether new or second hand, and lenders tend to like them because they hold their value better than tube and fittings. Lenders will ask about the licences behind the lorry as well as your accounts. Smart Funding Solutions, a whole-of-market commercial finance broker, searches lenders that fund commercial vehicles for construction trades.
Usually, yes. GOV.UK says a goods vehicle operator licence is needed for a vehicle with a gross plated weight over 3,500kg. A scaffolding firm carrying its own scaffold to its own jobs normally needs a restricted licence, which covers your own goods only, while carrying other firms’ loads needs a standard licence. GOV.UK explains the driving licence categories for each weight. Read more on commercial vehicle finance, and for a heavier lorry see our HGV finance page. To see which lenders may fund the lorry before anyone checks your credit file, use Instant Quotes.
It depends on how long the extra stock will be out and how often you run short. Cross hiring from another firm costs nothing up front and suits a one-off job, but the weekly charges mount up on long hire periods and extensions. If the same shortfall keeps coming back, buying stock on hire purchase can cost less over a year and leaves you owning it. Our brokers set the monthly repayment against your cross hire bills so the comparison is on paper before you commit.
Yes. Employers’ liability, public liability and contract works cover for scaffolders can carry a large annual premium, and insurance premium finance spreads it over monthly payments, usually arranged with your insurance broker at renewal. That keeps cash free for wages and stock in the weeks the premium is due. Some lenders cap or exclude scaffolding stock, as our page explains below, so new tube and fittings can suit hire purchase while stock you already own may support asset refinancing. Compare what the panel lenders may offer through Instant Quotes, with no credit search.
Costs depend on the product, amount, term, your credit profile, trading history and any security. Compare the total repayable, deposits, fees and early settlement terms rather than the monthly payment alone. Asset finance terms are usually matched to the working life of the equipment.
With hire purchase or leasing the equipment can be repossessed if payments are missed. Most loans to limited companies also ask directors for a personal guarantee, which puts personal assets at risk if the business cannot pay.
many lenders set a minimum trading period, and more options open up with a longer track record.
regular income and how well cash is managed between contract payments.
reliance on one main contractor is a concern; a spread of house builders, commercial and domestic clients reassures lenders.
work lined up supports borrowing for growth.
of the business and its directors or owners.
current finance agreements and how they have been repaid.
whether cash flow comfortably covers repayments in a quiet winter month.
Scaffolding is a sector where lender appetite varies more than almost anywhere else in construction.
Corporation tax funding can protect contract cash, as in our construction tax funding case.
On our panel, three asset finance lenders exclude scaffold erection outright, one caps it at £50,000 and two more treat it as a sector they dislike. Others fund it readily, so the application should go to the right ones first.
Scaffolding is usually priced with an initial hire period and weekly charges after it. Lenders look at how much income comes from extended hire, which is profitable but can be slow to collect.
Main contractors often pay on long terms and deduct tax under the Construction Industry Scheme. Lenders check whether the firm holds gross payment status; see what CIS subcontractors must do.
Lenders ask how scaffold stock is tracked between sites, since unrecorded losses erode both value and margin.
Decisions can come within a few working days once a lender has everything it needs, and funds can follow shortly after signing. It is free to enquire, and any broker fee is disclosed separately before you proceed. For other trades, see our main construction finance page or our guide to construction equipment finance.
Yes, some lenders will fund used scaffolding stock, though they may value loose tube and fittings more cautiously than system scaffold or vehicles. Expect to provide a supplier invoice or inventory showing quantities and condition, and possibly a larger deposit on older kit. Buying from an established dealer usually makes the deal easier to place. Our page on used equipment finance explains how lenders approach second-hand assets.
There is no single rule, as many lenders set their own minimum trading period and more options open up with a longer track record. A newer scaffolding firm may still get asset finance on equipment, often with a larger deposit, or a government-backed Start Up Loan. Established firms with filed accounts, steady bank statements and a spread of clients can approach a wider range of lenders. Our guide to start-up business loans covers early-stage options.
Yes, sole traders and partnerships can get scaffolding finance, as well as limited companies. Lenders will ask for bank statements, tax returns and details of your contracts and clients. Finance of £25,000 or less to a sole trader or a partnership of two or three partners can be regulated consumer credit, which affects which lenders can offer it. Hire purchase on tube, fittings and vans is often the easiest starting point because the kit is the security. See sole trader loans for more.
Yes, yard premises and secure storage can be funded, though the product depends on whether you are buying or leasing. Buying a yard usually suits a commercial mortgage or secured loan over a longer term, with the property as security. Fencing, racking and security systems on a leased yard may suit asset finance or an unsecured loan. Lenders will check that repayments are affordable in a quiet winter month. Our page on buying business premises explains the property side.
Often, yes, but construction invoices are harder to fund than most because of applications for payment, retentions and contra charges. Some invoice finance providers specialise in construction and will fund certified applications; others will only fund invoices for completed work. See contract funding.
Yes. Buying an established scaffolding business is usually funded with acquisition finance: a loan sized on the business's recent profits, your own contribution and sometimes part of the price paid to the seller after completion. Lenders look most closely at its contracts and customer spread, the age and quantity of its tube, fittings and boards, the lorries and yard, and whether the experienced crews and supervisors will stay. You can see which lenders on our panel fund purchases like yours with Instant Quotes.
Yes. A scaffold lorry, with or without a crane or hoist, can be bought on hire purchase or leased, new or second hand, and it usually holds its value better than tube and fittings. Lenders ask about the plated weight, the drivers' licences, the operator licence and where the lorry is kept. Smart Funding Solutions, a whole-of-market commercial finance broker, finds lenders that are comfortable with construction vehicles.
Usually, yes. GOV.UK says a goods vehicle operator licence is needed for a vehicle with a gross plated weight over 3,500kg. A firm carrying only its own scaffold normally needs a restricted licence, and carrying other firms' goods needs a standard licence. Drivers need C1 for lorries between 3,500kg and 7,500kg.
It depends on how long the extra stock is needed and how often you run short. Cross hire suits one-off jobs with no upfront cost, while repeated shortfalls and long hire periods can make buying stock on hire purchase cheaper over a year. Compare twelve months of cross hire invoices, including haulage and losses, with the monthly repayment. Smart Funding Solutions, a whole-of-market commercial finance broker, can price both.
Yes. Insurance premium finance spreads the annual cost of employers' liability, public liability and contract works cover over monthly payments, usually arranged through your insurance broker at renewal. It keeps cash free for wages and stock in the month the premium falls due.
Most civil engineering contractors fund each part of the cash gap separately. Plant goes on hire purchase or leasing; the wait…
Utility contractors usually combine asset finance for excavators, vans and specialist plant with invoice or contract finance on…
Roofing business finance helps roofers fund access equipment, vans and materials, and smooth out cash flow when commercial…
For construction plant, the choice usually comes down to how long you need the machine. Hire purchase suits excavators, dozers…
Builders' merchants are usually funded against what they hold: invoice finance on the trade ledger, stock finance for bulk buys…
JCT contract finance funds the cash a contractor lays out between doing the work and being paid under a JCT or similar building…
What our clients say
“Simon was fast, kept us updated at all stages and was a real pleasure to work with on our asset finance. I highly recommend this company: excellent service all round.”
“Spoke with Simon, who managed to get me the loan I needed promptly. The whole process was very smooth and was completed within a few days.”
“Getting a business loan can feel like a bit of a minefield, but everything was broken down for me in great detail. Will use again in the future!”
“Simon was a pleasure to deal with and helped us find a business loan that matched our growth goals and future expansion plans.”
“I couldn’t source funding for my business, but the team got in touch within an hour and had it sorted within 24 hours. Fantastic service, and I would definitely use them again.”

Chat with Smart Funding
We usually reply in seconds
Please don't share bank details or passwords here. Calls on 01244 267694.