
Hotel commercial mortgages: financing the purchase of a hotel
A hotel is usually bought with a commercial mortgage secured on the property and lent against its trading valuation, so both loan-to-value and profit cover…
How hotels and guest houses fund a purchase, refurbishment, extra rooms or quiet months, and how lenders weigh occupancy, room rates and the property itself.
Explore funding options Prefer a quick call back? Leave your number
“Amazing, easy to talk to and extremely helpful.”
In short
A purchase or freehold usually needs a commercial mortgage with a deposit; a large conversion may use bridging or staged development finance; bedrooms, kitchens and laundry kit often suit asset finance; and winter wages can be covered by revolving credit or card-based funding. Lenders focus on occupancy, room rates, booking-site commission and how repayments are met off-peak.


“He is fair and always gives advice that is in the best interest of his clients.”
About hotel finance
Hotel finance is borrowing used to buy, refurbish, expand or run a hotel, boutique hotel, guest house or B&B, from commercial mortgages on the building to equipment leasing and working capital facilities. The right product depends on what you are funding: buying a freehold is very different from replacing bedroom furniture or covering wages over winter.
Smart Funding Solutions is a whole-of-market broker. We search our panel of 300+ lenders, including banks, specialist hospitality lenders and alternative finance providers, and put your case to those best suited to it. This page is part of our hospitality business loans section.
Hotels are unusual borrowers because they are both a property and a trading business. A lender will value the building, but it will also look at how well it trades: occupancy, average room rate, revenue per available room, food, drink and events income, and how much business comes through booking sites that take commission. Seasonal hotels also need to show how fixed repayments are met in the quiet months.
Funding needs
Not ready for the full application? Leave a few details and a broker will call you to talk it through. It is free, with no obligation.
A transaction we arranged

£35,000
£35K secured on the business premises, not the family home.
A pub and B&B wanted secured funding but needed clarity on where the security would sit. The charge went on the trading property.
Read the transaction
Long-term borrowing secured on the hotel property, used to buy or refinance. Lenders value the hotel as a trading business as well as bricks and mortar, so accounts and trading performance matter alongside the property itself. Valuers usually assess a hotel as an operational business, based on the trade it can sustainably produce, so a weak trading year can lower the valuation as well as the affordability figures. Lenders also differ in appetite: some will not lend on hotels outside their preferred size, location or trading history, which is why the same case can be declined by one lender and accepted by another.

Short-term secured finance for when speed matters, such as buying at auction, completing before longer-term funding is in place or funding a refurbishment before refinancing. Read our guide to bridging loans.

For larger projects, such as converting a building into a hotel or substantially extending one, lenders may release funds in stages as work progresses. See property development finance for how staged funding works.

A secured business loan uses property or other assets as security and can offer larger sums and longer terms. Unsecured loans are quicker to arrange for smaller projects but usually need a personal guarantee.

Hire purchase or leasing for equipment such as kitchen kit, laundry machines, furniture and technology, with the asset acting as security.

A merchant cash advance is repaid as a share of card takings, which can suit a seasonal hotel. Revolving credit gives a facility to draw on and repay as needed.
Cash leaves the business at every stage before it comes back. Each stage below is a point where the right facility can carry the gap.
 01
Orders, contracts or customers secured.
02 Stock, materials and equipment paid for up front.
Asset finance → 03
Wages and suppliers paid on time.
Working capital → 04
The work is done or the goods are sold.
05 Customers pay, sometimes weeks later.
Invoice finance → 06
VAT and Corporation Tax fall due.
HMRC loans →07 Growth, a new site or new equipment.
Business loans →Choose the need, and we’ll show you how lenders usually structure it.
More detail on specific needs within this topic.
A hotel is usually bought with a commercial mortgage secured on the property and lent against its trading valuation, so both loan-to-value and profit cover…

Hotel refinance is a new secured loan on a hotel you already own that repays your existing lender and can release extra capital from the property's equity.…
Rates and terms depend on the product, the loan size, the term, your credit profile, trading history and the security offered. Secured borrowing against a hotel property usually costs less and runs longer than unsecured borrowing. Always compare the total cost, and check arrangement fees, valuation and legal costs, early repayment charges and any personal guarantee.
accounts, occupancy, average room rates and revenue from food, drink and events.
your track record of running a hotel or hospitality business. First-time buyers without experience may need a stronger deposit or an experienced manager.
purchases usually need a meaningful deposit, and the hotel itself is normally the main security.
for purchases, conversions and larger refurbishments, realistic forecasts showing how the project improves revenue.
the business's and the owners' credit history.
whether cash flow supports repayments across the whole year, including off-peak months.
It is free to enquire, and any broker fee is disclosed separately before you proceed. Running a smaller guest house? Our guide to bed and breakfast loans covers issues specific to owner-occupied B&Bs.
Yes, hotel finance for bedroom refurbishment is usually arranged as a term loan, fit-out finance, or asset finance for furniture, bathrooms and technology. Lenders look at occupancy, average room rate, revenue per available room and how the refurbishment will lift trading. Owners with equity in the freehold may also refinance to release capital. Our page on fit-out and refurbishment finance explains the options in more detail.
Yes, seasonal hotels can get hotel finance, but lenders want to see how fixed repayments will be met in the quiet months. They review monthly trading figures, cash flow forecasts and reserves, and some may agree repayment profiles that reflect the season. A revolving facility can help cover winter wages. Our guide to seasonal business finance covers ways to manage uneven income.
Often, yes, particularly on smaller hotel finance deals and unsecured working capital. A commercial mortgage is secured on the hotel itself, but lenders frequently ask owners or directors for a personal guarantee as well, because the property's value depends on how well it trades. The amount and terms vary. Our guide to personal guarantees explains what to check before you sign.
Yes, hotel owners with equity in the freehold can often refinance onto a new commercial mortgage to release capital for refurbishment, expansion or another purchase. Lenders value the hotel on its trading performance, so recent accounts showing stable or improving profit help. Loan-to-value and profit cover both limit the amount. Our page on commercial property refinance explains how the process works.
The amount was large relative to turnover. We placed it with a lender willing to look at the whole financial picture.
Repeat working-capital facilities for seasonal cash flow, staffing, maintenance and guest-facing investment.
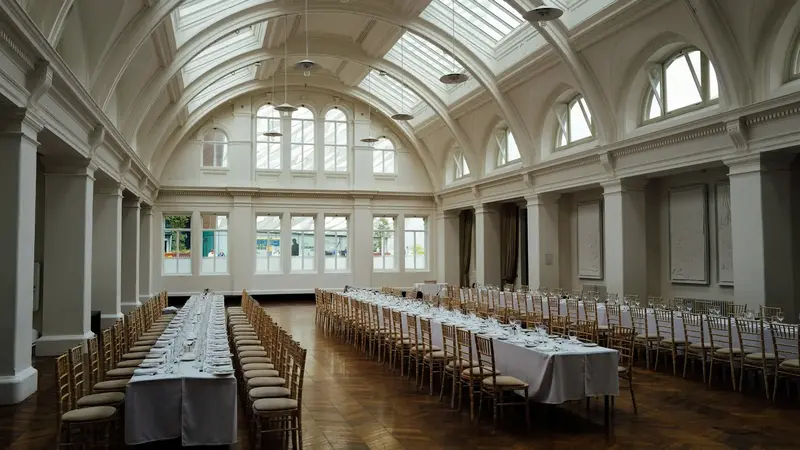
Wedding venues are usually bought or refinanced with a commercial mortgage, converted with staged or bridging finance, and…

Most people buy a trading B&B with a commercial or semi-commercial mortgage, because the owner lives on site and the lender…
Established guesthouses are usually funded with a commercial mortgage or secured loan for refurbishment and extensions, asset…
To buy a pub, first decide whether you want the freehold, a free-of-tie lease or a tied tenancy, as this sets how much you need…
A pub mortgage is a long-term commercial loan used to buy or refinance the freehold of a pub, secured on the property. Lenders…
Most cafes combine two or three types of finance rather than one loan: equipment finance or leasing for the espresso machine…
What our clients say
“Simon was fast, kept us updated at all stages and was a real pleasure to work with on our asset finance. I highly recommend this company: excellent service all round.”
“Spoke with Simon, who managed to get me the loan I needed promptly. The whole process was very smooth and was completed within a few days.”
“Getting a business loan can feel like a bit of a minefield, but everything was broken down for me in great detail. Will use again in the future!”
“Simon was a pleasure to deal with and helped us find a business loan that matched our growth goals and future expansion plans.”
“I couldn’t source funding for my business, but the team got in touch within an hour and had it sorted within 24 hours. Fantastic service, and I would definitely use them again.”
Live chat with our team. Our chat is provided by Crisp, which sets cookies so your conversation is kept and we can see which page you are viewing. It only switches on if you allow it. Cookie Policy