
How to open a padel club: site, planning, costs and funding
To open a padel club, test local demand, choose between an indoor unit and an outdoor site, secure planning consent and a lease…
How to open an indoor golf centre in the UK: testing demand, choosing a unit, planning and licensing, the main costs and how new venues are funded.
This guide is for people planning an indoor golf centre in the UK, whether a coaching studio with a few bays, a social venue with simulators, food and drink, or bays added to an existing golf club, bar or leisure site. It covers the decisions that shape the business, planning and licensing, the main costs and how new centres are usually funded. Smart Funding Solutions is a broker, not a lender: we search a panel of 300+ lenders and arrange facilities from around £10,000 to £500,000+, with larger facilities available in suitable cases. Our golf simulator finance page covers borrowing for the bays themselves.
Indoor golf venues tend to fall into three models, and the choice drives the site, the fit-out and how lenders read the plan:
Most centres take a light industrial unit, a retail unit or space in a leisure scheme. The building has to suit the bays as well as the customers:
In England, indoor sport, recreation or fitness falls within Class E(d), so a unit already in Class E may not need a change of use, while an industrial unit in another class usually will. Check the use classes and speak to the council early, particularly if the venue will trade late or play music.
In England and Wales, a venue that sells alcohol on a permanent basis needs a premises licence, and sales must be made or authorised by a personal licence holder, with a designated premises supervisor named for the premises. See GOV.UK's alcohol licensing guidance and allow time for the application in your opening plan. Licence conditions on hours can affect how many evening bay hours you can sell.
Every project is different, so build your budget from real quotes rather than averages. The main headings are:
| Cost | Finance that often fits | Why |
|---|---|---|
| Simulator hardware | Asset finance | Removable equipment from known suppliers |
| Fit-out works | Fit-out finance or a term loan | Works stay with the building |
| Bar and kitchen equipment | Asset finance or term loan | Equipment with some resale value |
| Opening costs and contingency | Owners' money or start-up loan | No asset for a lender to rely on |
| Quiet summer months | Working capital | Bridges the seasonal dip |
New centres are usually funded from several sources, each matched to a different part of the cost:
An operator with a centre already trading can use its figures as the template for a second site; our growth finance page explains how. Operators taking on a branded concept should also see franchise loans.
Summer trading can be much quieter than winter, so a plan that only works in the busy months will struggle. Simulator technology moves on, and a venue may need to refresh software or hardware sooner than the finance term suggests. Energy, staff and rent are largely fixed. Licensing delays can push back opening, and a new venue nearby can change local demand quickly. Most new venue borrowing involves personal guarantees, so understand what you are signing; our guide to personal guarantees explains the commitment. Borrowing of £25,000 or less by sole traders and small partnerships can be regulated consumer credit, which brings additional protections.
This guide is general information, not financial advice. Lenders set their own criteria, rates and terms, and all finance is subject to status.
Not ready for the full application? Leave a few details and a broker will call you to talk it through. It is free, with no obligation.
It depends on the simulator and the size of bay you want, so check the supplier's minimum height, width and depth before agreeing a lease. Ceiling height is often the deciding factor, because golfers need room for a full swing.
In England, indoor sport and recreation falls within Class E(d), so a unit already in Class E may not need a change of use. An industrial or warehouse unit in another class usually will. Check the use classes and speak to the council early.
In England and Wales, yes. A business selling alcohol on a permanent basis needs a premises licence from the local authority, a designated premises supervisor and sales made or authorised by a personal licence holder. Allow time for this before opening.
Yes, but lenders lean heavily on your experience, the business plan and your own contribution. Simulators from established suppliers can often go on asset finance, with the fit-out and opening costs funded separately. See start-up business loans.
Usually. An existing venue already has a site, customers, staff and accounts lenders can read, which tends to lower both cost and risk compared with a standalone new centre.
Many run leagues, coaching programmes, corporate events and parties to fill the quieter months. A revolving facility or working capital loan can help bridge the dip; see revolving credit facilities.
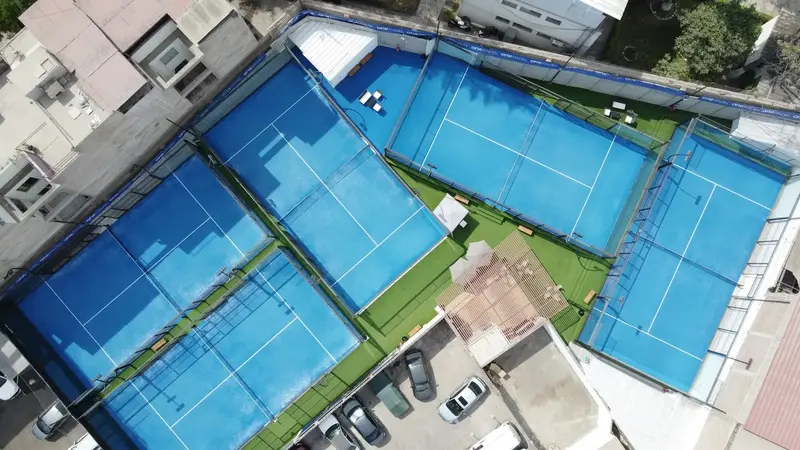
To open a padel club, test local demand, choose between an indoor unit and an outdoor site, secure planning consent and a lease…

To open a day nursery in England you need premises with enough indoor and outdoor space for the EYFS requirements, a qualified…
Golf buggy finance spreads the cost of a buggy fleet over several years, usually through hire purchase or leasing secured on…
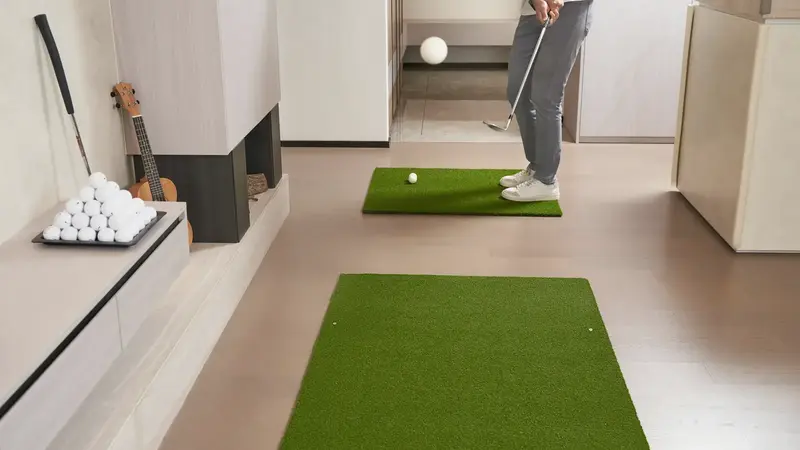
Golf simulator finance for a business is usually hire purchase or leasing on the launch monitors, projectors, computers and…
Golf course machinery finance spreads the cost of greenkeeping equipment, such as greens, fairway and rough mowers, tractors,…
How a sports business is funded depends mostly on whether it is a commercial business or a community club. Commercial venues,…
A short conversation is often enough to know which lenders will look at your case and how to present it. There is no obligation, and it is free to enquire.