

Outdoor activity business finance for adventure centres and instructors
Outdoor activity businesses usually fund boats, bikes, vehicles and climbing kit through asset finance, and use an unsecured…
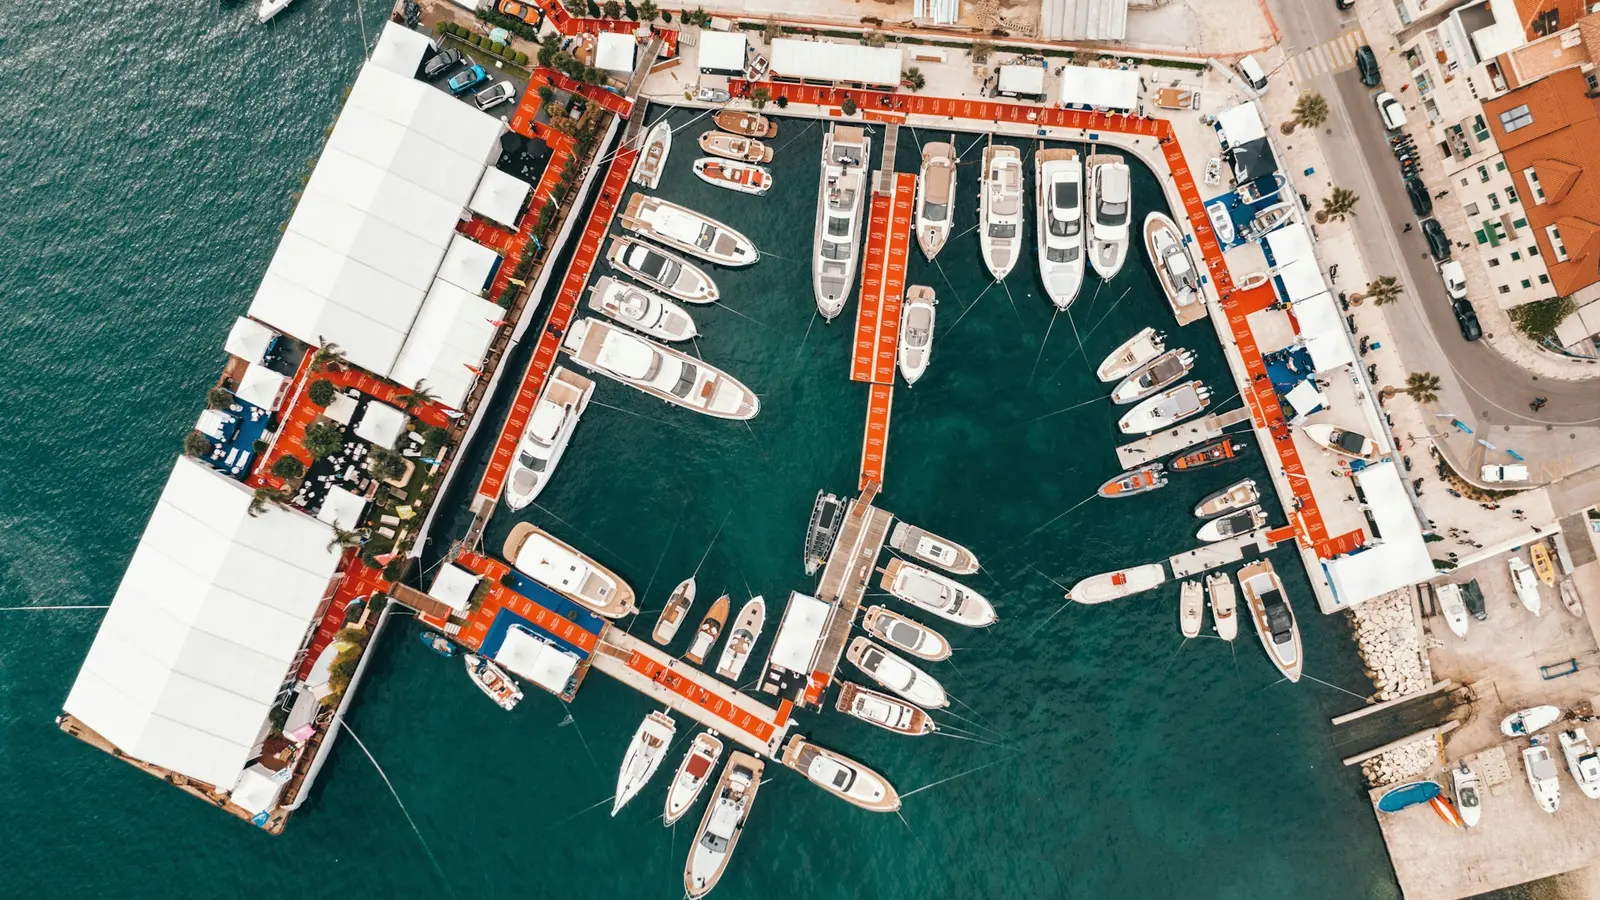
How marinas and boatyards fund pontoons, travel hoists, dredging, sheds and marina purchases, which finance fits each cost, and what lenders check first.
Prefer a quick call back? Leave your number
Marina finance usually combines asset finance for travel hoists, boat movers and some pontoon systems, a term loan or secured loan for piling, dredging and buildings, and a commercial mortgage with acquisition finance for buying a marina. Lenders look most closely at berth income and renewals, seabed or foreshore leases, consents and the condition of the infrastructure.
This page is for people running or buying marinas and boatyards: coastal and inland marinas, river moorings businesses, boatyards with hard standing and repair sheds, dry stack operators, and canal-side basins. Smart Funding Solutions is a broker, not a lender: we search a panel of 300+ lenders and arrange facilities from around £10,000 to £500,000+, with larger facilities available in suitable cases. This page is part of our leisure business finance guides. Watersports schools and boat hire businesses should see outdoor activity business finance, and fishing businesses commercial fishing finance.
Not ready for the full application? Leave a few details and a broker will call you to talk it through. It is free, with no obligation.
Cash leaves the business at every stage before it comes back. Each stage below is a point where the right facility can carry the gap.
 01
Annual berth fees, usually paid in advance.
 02
Visitors, fuel, chandlery and repairs through the summer.
Stock finance → 03
Hoists and movers working hard in autumn and spring.
Asset finance → 04
Storage ashore and repair work in the yard.
 05
Pontoons, piles and dredging on a long cycle.
Secured loans → 06
Buying a marina or the freehold.
Commercial mortgage →Choose the need, and we’ll show you how lenders usually structure it.
Travel hoists, boat movers, hydraulic trailers, forklifts and tractors are identifiable equipment with a used market, so most asset finance lenders are comfortable funding them. See plant and machinery finance, and used equipment finance for second-hand hoists. Lifting equipment must be examined and maintained under LOLER, and lenders may ask for inspection records on used kit.
Modular pontoon systems from established manufacturers can sometimes be funded on asset finance, particularly floating sections that could be removed. Piling, dredging and fixed structures are closer to civil works, so they are usually funded with a term loan or a secured business loan against the marina itself.
Repair sheds, dry stack buildings, facilities blocks and a marina restaurant fit-out are usually funded with a term loan or fit-out and refurbishment finance. Operators running a bar or restaurant should also see hospitality business loans.
Buying a marina or boatyard usually combines a commercial mortgage on the land and buildings with acquisition finance for the trading business. Where a purchase has to complete quickly, or the site needs work first, bridging finance can be a short-term step. Our guide on how to buy a business covers the process.
Marinas with a chandlery or a new boat dealership may use stock finance. A revolving credit facility can cover the gap before berth renewals or a large dredging bill.
Most marinas earn the bulk of their income from berthing. Annual berth holders usually pay in advance, which gives the business a strong cash position at the start of the year and a predictable base that lenders value. Visitor berths, winter storage ashore, lift-outs and launches, and dry stack storage add more. Many sites also earn from boat repairs and servicing, a chandlery, fuel sales, brokerage, and rent from tenants such as a café, bar, sailmaker or engineer.
The costs are heavy and lumpy. Pontoons, piles, gangways and walkways wear in salt or fresh water and need replacing on a cycle. Silt builds up and dredging can be a major expense. A travel hoist, boat mover or forklift is essential kit, and a breakdown in the autumn lift-out season is costly. Seabed, riverbed or canal leases, insurance, business rates and staff run all year. Good marina finance matches each of those costs to the right kind of borrowing.
Many marinas do not own all of the land and water they use. Berths often sit over seabed or foreshore leased from The Crown Estate (Crown Estate Scotland in Scotland), a harbour authority or a private owner, and inland sites may depend on agreements with the navigation authority. Lenders check that these leases and licences run well beyond the finance term and can be assigned or charged.
New pontoons, piling and dredging may need consents as well as planning permission. In England the Marine Management Organisation issues marine licences; see GOV.UK guidance on marine licence applications. Wales, Scotland and Northern Ireland have their own licensing bodies. Lenders will usually want consents in place before they release funds for works.
A loan for pontoons should be repaid well before they need replacing again. Dredging costs can recur, so build them into forecasts rather than borrowing for them each time. A marina valued with its berth income can lose value quickly if occupancy falls, so test repayments against a cautious renewal rate. Directors should expect personal guarantees; see our guide to personal guarantees. Borrowing of £25,000 or less by sole traders and small partnerships can be regulated consumer credit, which brings additional protections.
This page covers finance for businesses that run marinas, boatyards and moorings. Finance for a private boat or a berth for personal use is a different kind of borrowing and outside its scope. Marinas with holiday lodges may also find caravan park and campsite finance useful.
Occupancy, how many berth holders renew each year, any waiting list and the split between annual and visitor income.
Storage, lift-outs, repairs, fuel and rents, and how much depends on one tenant or season.
Freehold title and any seabed, foreshore or riverbed leases.
The age of pontoons and piles, dredging needs and any recent surveys.
The management team's record, particularly for a buyer new to the sector.

| Cost | Finance that often fits | Why |
|---|---|---|
| Travel hoist or boat mover | Hire purchase or leasing | Mobile equipment with a used market |
| Floating pontoon sections | Asset finance or a term loan | Depends on the system and how it is fixed |
| Piling and dredging | Term loan or secured loan | Civil works with no resale value |
| Sheds, dry stack and facilities | Term loan or fit-out finance | Building works tied to the site |
| Buying a marina | Commercial mortgage with acquisition finance | Long term, secured on the property and business |
| Chandlery stock and cash flow | Stock finance or revolving credit | Short term, flexible borrowing |
We look at the whole project, separate the equipment from the civil works and the property, and approach the lenders likely to fund each part. For a purchase, we check the tenure and consents early, because they shape which lenders will consider the deal. Our sports business funding guide covers other routes for leisure businesses. It is free to enquire; any broker fee is disclosed separately before you proceed.
Usually, yes. Travel hoists and boat movers are identifiable equipment with a used market, so asset finance lenders will often fund them on hire purchase or leasing, new or used. For used hoists, lenders may ask for inspection records and the supplier's details.
Floating pontoon sections from established manufacturers can sometimes go on asset finance. Piling, dredging and fixed works are usually funded with a term loan or a loan secured on the marina. Lenders will want any marine licence and planning consent in place first.
Often, yes. A purchase usually combines a commercial mortgage on the property with acquisition finance for the business. Lenders look at berth income and renewals, the seabed or foreshore leases, the condition of the infrastructure and the buyer's experience, and expect a meaningful deposit.
Yes. Where berths sit over seabed or foreshore leased from The Crown Estate, a harbour authority or another owner, lenders check that the lease runs well beyond the loan term and can be charged or assigned. A short or uncertain lease limits the lenders who will consider the marina.
A shed or workshop is usually funded with a term loan or a loan secured on the yard, as building works cannot easily be repossessed. Equipment inside it, such as lifting gear, compressors and spray booths, can often go on asset finance.
Yes, though they are covered on a separate page. Watersports schools, paddleboard and kayak hire are covered in outdoor activity business finance.
Outdoor activity businesses usually fund boats, bikes, vehicles and climbing kit through asset finance, and use an unsecured…
Driving range finance usually puts ball tracking technology, ball dispensers, pickers and mats on asset finance, funds new…
Beauty salon business loans fund refits, treatment equipment, stock and new sites for hair and beauty salons, barbers, nail…
Event management businesses usually borrow to cover costs that fall due before the event pays: venue and supplier deposits,…
Football club finance usually combines a term loan or secured loan for 3G pitches and building works, asset finance for…
Golf club finance usually combines asset finance for buggies, greenkeeping machinery and range technology, a term loan or…

Tell us what the funding is for. We search our panel of 300+ lenders, structure the case and approach the ones suited to it. No obligation, and free to enquire.