

Tennis dome finance: air domes and covered courts
Tennis dome finance helps clubs and centres cover outdoor courts with an air-supported dome, a framed fabric structure or a…
How tennis clubs, schools and venues fund court resurfacing, new courts and floodlights, why lenders treat surfaces as works, and what they check first.
Prefer a quick call back? Leave your number
Tennis court finance covers resurfacing, rebuilding or building new courts, and floodlights. Because a court surface is fixed to the ground and cannot be removed, lenders usually fund it with a term loan or a secured loan rather than asset finance. LED floodlight fittings can sometimes go on asset finance. Many not-for-profit clubs combine borrowing with grants, a governing body loan and their own sinking fund.
This page is for anyone paying for tennis courts: members' clubs, commercial tennis centres, hotels, holiday parks, schools with community lettings and multi-sport venues. It covers resurfacing, new courts, fencing and floodlights. Smart Funding Solutions is a broker, not a lender: we search a panel of 300+ lenders and arrange facilities from around £10,000 to £500,000+, with larger facilities available in suitable cases. For the wider picture, see our tennis club finance hub.
Not ready for the full application? Leave a few details and a broker will call you to talk it through. It is free, with no obligation.
A court surface and its base are fixed into the land and cannot be taken away and resold, so asset finance lenders give them little or no security value. Lenders usually fund them with an unsecured or partly secured business loan, or with a secured loan against land or buildings the club owns.
LED floodlight fittings and control systems are closer to equipment and can sometimes be funded on asset finance. Columns set in concrete, cabling and the electrical supply are building works. A floodlight project is often split between the two.
Fencing is usually treated as works. Nets, posts, ball machines and booking or access systems are small, removable items that can be included with other equipment.
Each surface type has a different cost, playing character, maintenance need and working life, so it is worth getting advice from a specialist contractor and the governing body before choosing.
New courts, higher fencing and floodlights often need planning permission, and floodlight consents commonly come with conditions on hours and light spill near homes. Lenders will usually want consent in place before completing. The Planning Portal explains how the planning process works.
Some clubs convert an underused tennis court into padel courts, which can bring new members and more court hire per square metre. Padel courts can be removed and resold, so they are often easier to fund on asset finance than a tennis surface. See padel court finance.
Repay court finance well within the life of the new surface, or the club risks still paying for one surface when the next one is due. Plan to rebuild the sinking fund alongside the loan repayments. Floodlights add electricity costs as well as playing hours, so include them in the forecast. For commercial operators, personal guarantees are common.
ownership of the land, or a lease running well beyond the finance term
who can borrow and sign for the club, and approval for the borrowing
membership, court hire, coaching and pay-and-play
the club's own reserves and any grant or governing body loan
quotes from an experienced court contractor, and warranties on the surface
How the main business finance structures work. Lenders set their own terms, so treat this as a guide to the questions to ask.
| Option | How you repay | Security | Often used for |
|---|---|---|---|
| Unsecured business loan | Fixed instalments, usually monthly | No charge over assets; a personal guarantee is usually required | Growth, stock, tax bills and cash flow |
| Secured business loan | Fixed instalments, often over a longer term | A charge over property or other assets | Larger sums, property and refinancing |
| Revolving credit facility | Interest on what you draw; repay and redraw | Varies by lender and case | Recurring or uneven cash flow gaps |
| Merchant cash advance | A share of future card takings | No charge over assets | Card-taking businesses with uneven months |
| Asset finance | Regular payments over the life of the asset | The asset being financed | Equipment, vehicles and machinery |
| Invoice finance | Settled as customers pay their invoices | Your unpaid invoices | Businesses waiting on customer payment |
General information only. Every lender has its own criteria, and all finance is subject to status.
| Option | How it works | Often suits |
|---|---|---|
| Sinking fund | Money set aside each year for resurfacing | Every club, as the first source |
| Grant | Money that does not need repaying, usually with conditions | Not-for-profit clubs with community access |
| Governing body loan | A loan from the sport's governing body or its charity | Eligible not-for-profit venues |
| Term loan | A lump sum repaid over a set term | Clubs and companies with trading accounts |
| Secured loan | A loan secured on land or buildings | Clubs that own their site |
| Asset finance | Hire purchase or leasing on removable equipment | LED fittings and systems |
For not-for-profit venues, the LTA Facility Loan Scheme and Sport England funding are worth checking before commercial borrowing, as both can reduce the amount a club needs to borrow.
We split the project into the parts different lenders will fund, look at how grants or a governing body loan fit alongside, and approach lenders on our panel suited to clubs and venues. If you are considering covered courts, see tennis dome finance. It is free to enquire; any broker fee is disclosed separately before you proceed.
Rarely for the surface itself, because it cannot be removed and resold. Resurfacing is usually funded with a term loan, a secured loan, a grant or governing body loan, or the club's own reserves. LED floodlight fittings are more often suitable for asset finance.
Ideally a term well inside the expected life of the new surface, so the loan is repaid before the next resurfacing is due. Your contractor can advise on the likely life of the surface you choose.
Usually, yes, and consents often include conditions on hours and light spill. Lenders will normally want to see consent in place before they complete.
Yes. Independent schools, hotels and holiday parks often fund courts as part of wider facility plans. See independent school finance and hotel funding.
It depends on the site and the courts chosen. Padel courts are often easier to fund on asset finance, and several fit on the space of one tennis court, but they need planning consent and the right base. See padel club finance.
Tennis dome finance helps clubs and centres cover outdoor courts with an air-supported dome, a framed fabric structure or a…
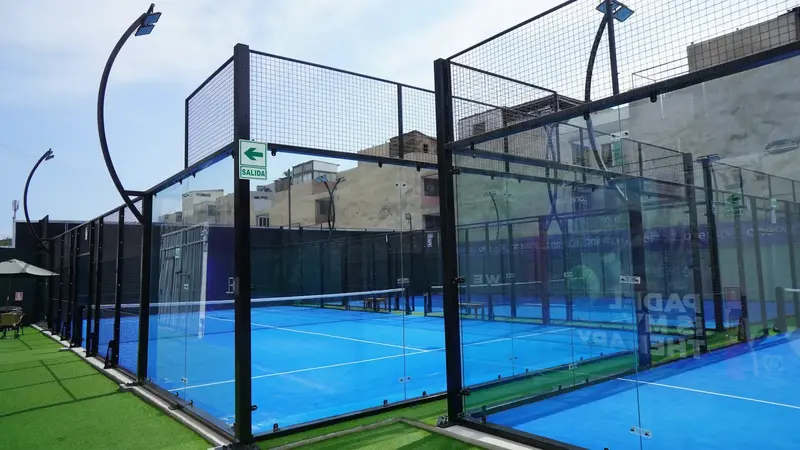
Padel club finance usually combines asset finance for the courts, lighting and any canopy, a term loan or fit-out facility for…
Padel court finance spreads the cost of courts over several years, usually through hire purchase or leasing secured on the…
Sports floodlight finance usually splits a project in two: LED fittings and controls can often go on asset finance, while…

Care home development finance is staged, short-term borrowing for building a new home, adding a wing or converting a building…
Football club finance usually combines a term loan or secured loan for 3G pitches and building works, asset finance for…

Tell us what the funding is for. We search our panel of 300+ lenders, structure the case and approach the ones suited to it. No obligation, and free to enquire.