

Professional football club finance: cash flow, income and ground funding
Professional football club finance usually means working capital facilities, advances against income the club is owed, such as…
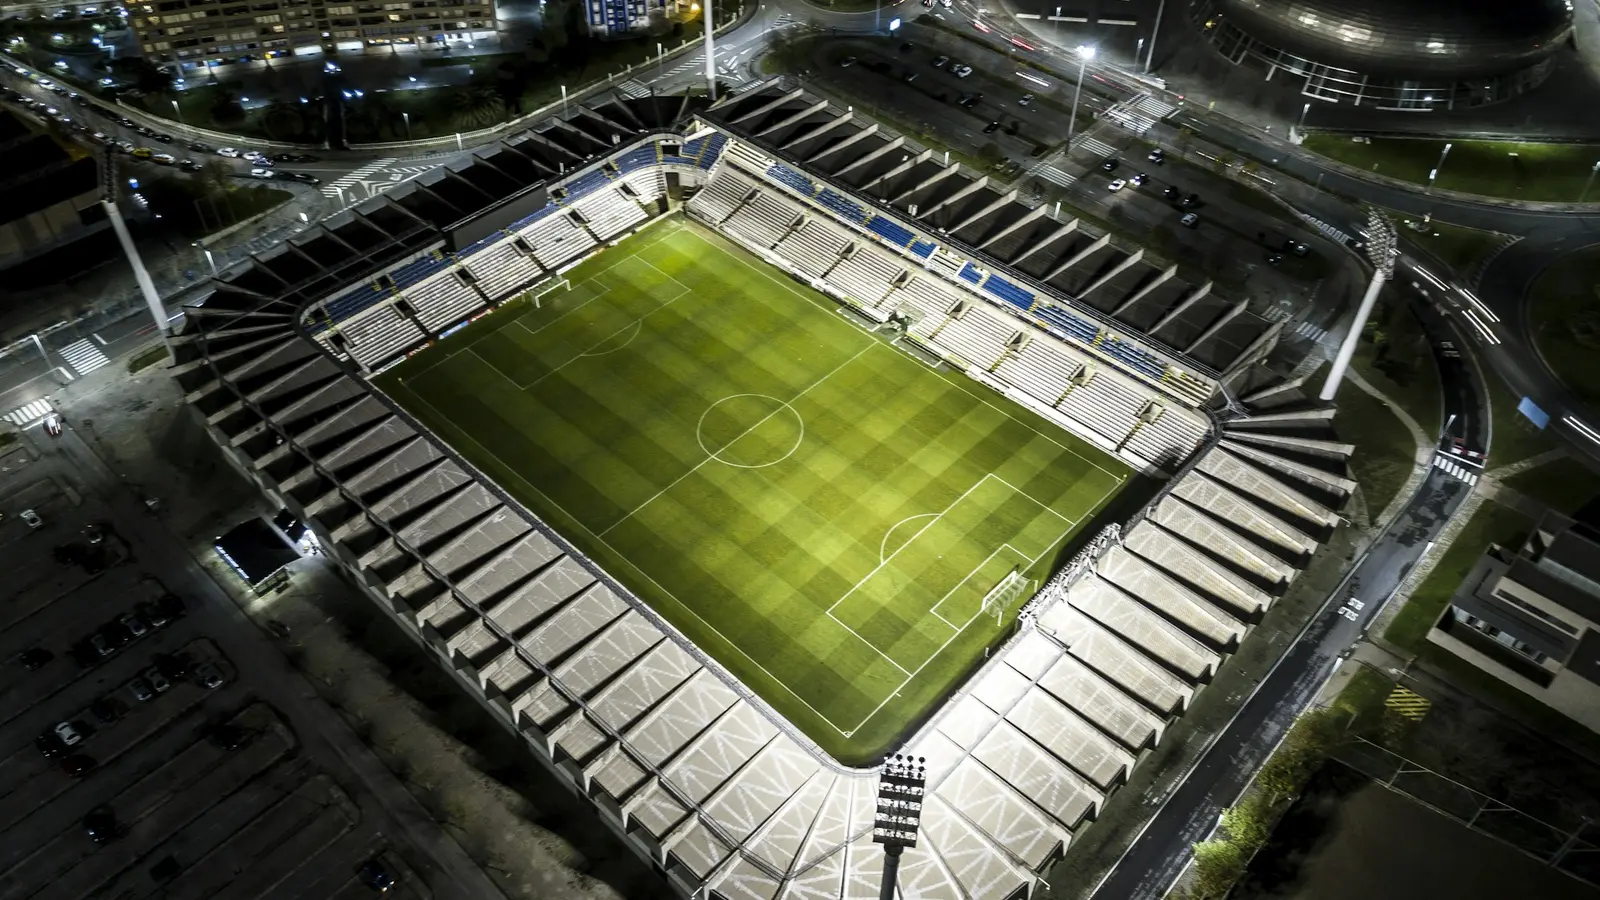
How football clubs fund buying a ground, new stands, hospitality, pitches and training grounds, from mortgages to sale and leaseback, and what lenders check.
Prefer a quick call back? Leave your number
Football stadium finance usually means a commercial mortgage to buy or refinance a ground, development finance for new stands and training grounds, a secured loan for smaller works, or a sale and leaseback to release value from a ground the club owns. Lenders look at title and tenure, a specialist valuation, planning, the club's finances and the income the project will bring in, and community clubs can combine finance with grants.
This page is for football clubs at every level funding their ground: professional clubs redeveloping a stadium, non-league clubs bringing a ground up to the standard needed for promotion, and community clubs buying or improving the land they play on. It covers buying the ground, new stands, hospitality, pitches, training grounds and academy facilities. Smart Funding Solutions is a broker, not a lender: we search a panel of 300+ lenders and arrange facilities from around £10,000 to £500,000+, with larger facilities available in suitable cases. This page is part of our football club finance guides.
Not ready for the full application? Leave a few details and a broker will call you to talk it through. It is free, with no obligation.
Buying the freehold of the ground from a landlord, council or former owner
New or rebuilt stands, terracing and covered accommodation
Hospitality boxes, lounges, bars and function rooms that earn income on and off matchdays
Turnstiles, ticketing and access control, toilets and changing rooms
Pitch reconstruction, drainage, undersoil heating and artificial surfaces
Floodlights and electrical upgrades
Training grounds, academy buildings and indoor facilities
Refinancing existing borrowing secured on the ground
A commercial mortgage can fund the purchase of a ground or training ground, or refinance borrowing already secured on it. Fewer lenders will consider a stadium than a standard commercial building, and they lend against the ground's value with a cautious view of how easily it could be sold. Our commercial property refinance page covers moving existing borrowing.
New stands, major rebuilds and training ground developments are often funded with development finance, released in stages as the work is completed and checked by a monitoring surveyor. See property development finance for how stage payments work. Where a club is selling part of its land for housing or commercial use to pay for a new ground, land finance or bridging finance can cover the gap until the sale completes.
A club that owns its ground can sell it to an investor and lease it back, releasing cash while it keeps playing there. This can raise more than a loan against the same ground, but the club gives up ownership and takes on rent for the length of the lease. Supporters often care a great deal about who owns the ground, so the lease terms, rent reviews and any rights to buy the ground back need careful legal advice.
For smaller projects, a secured business loan against the ground or another property can fund works without a full development facility. A smaller hospitality or changing room project may also suit fit-out and refurbishment finance.
Floodlight fittings, turnstiles, ticketing systems, pitch machinery and kitchen equipment can often go on asset finance alongside the property borrowing. See sports floodlight finance and 3G pitch finance for those parts of a project.
A football ground is a specialist property. Its value as a stadium depends on the club playing there, and its value for any other use depends on planning, location and the cost of changing it. Lenders and valuers therefore look at two figures: what the ground is worth to the club as a working stadium, and what it might be worth if the club left. Many clubs also rent their ground from an owner, a council or a related company, which limits what they can borrow against.
Ground projects also tend to be large and lumpy. A new stand, a hospitality suite or a training ground is built once and paid for over many years, so the finance needs to be long term and matched to the income the project brings in.
Clubs in the National League System and the women's football pyramid have to meet The FA's ground grading standards, now published as stadium accreditation criteria, for the level they play at or want to reach. The criteria cover areas such as floodlighting, covered accommodation, turnstiles, changing rooms and toilets, and a ground must be suitable for the level a club is seeking to join. That makes ground works part of a club's promotion plans, and lenders will want to see that the works will meet the grade the club needs. Check the current criteria for your step with your league or The FA before you price a project.
The Football Foundation runs grant programmes for grassroots facilities in England, such as pitches, changing rooms and floodlights, mainly for not-for-profit clubs, schools providing community use and local authorities. Sport England also funds community sport projects. Eligibility depends on the organisation and the project, and grants are competitive, so many clubs combine them with reserves and commercial finance. Check the funder's current criteria before relying on any grant. Community-owned clubs may also find our social enterprise finance page useful.
Borrowing secured on the ground puts the club's home at risk if repayments are missed, so test the forecast against a poor season or relegation. Building costs can rise during a project, so keep a contingency. Sale and leaseback brings in cash but leaves the club paying rent for many years. Grant conditions on community use or pricing can affect what a commercial lender will accept, so share grant terms early.
Whether the club owns the ground or holds a long lease, and any restrictions on use, sale or charging.
A valuation by a surveyor experienced with sports and leisure property, on both a stadium and an alternative-use basis.
Consent for the works, and any conditions on capacity, hours, noise or floodlights. Some grounds are listed by their council as assets of community value, which can affect a future sale.
Extra capacity, hospitality, conference and event income, and how realistic the forecast is.
Accounts, owner support and, for clubs in leagues with financial rules or under the new football regulator, how the borrowing fits within them.
The contractor, fixed-price contract, cost plan and contingency.

How the main business finance structures work. Lenders set their own terms, so treat this as a guide to the questions to ask.
| Option | How you repay | Security | Often used for |
|---|---|---|---|
| Unsecured business loan | Fixed instalments, usually monthly | No charge over assets; a personal guarantee is usually required | Growth, stock, tax bills and cash flow |
| Secured business loan | Fixed instalments, often over a longer term | A charge over property or other assets | Larger sums, property and refinancing |
| Revolving credit facility | Interest on what you draw; repay and redraw | Varies by lender and case | Recurring or uneven cash flow gaps |
| Merchant cash advance | A share of future card takings | No charge over assets | Card-taking businesses with uneven months |
| Asset finance | Regular payments over the life of the asset | The asset being financed | Equipment, vehicles and machinery |
| Invoice finance | Settled as customers pay their invoices | Your unpaid invoices | Businesses waiting on customer payment |
General information only. Every lender has its own criteria, and all finance is subject to status.
| Cost | Finance that often fits | Why |
|---|---|---|
| Buying the ground or training ground | Commercial mortgage | Long term, secured on the property |
| New stand or major rebuild | Development finance | Released in stages as work completes |
| Releasing value from an owned ground | Sale and leaseback or refinance | Turns property value into cash |
| Hospitality, bars and changing rooms | Fit-out finance or a secured loan | Mostly works, repaid from new income |
| Floodlights, turnstiles and systems | Asset finance | Removable equipment from known suppliers |
| Gap before a land sale completes | Bridging finance | Short term, repaid from the sale |
| Community facilities | Grants with reserves or a loan | Grants rarely cover the whole cost |
We split a ground project into the parts different lenders will fund: property, works, equipment and any grant. We then approach lenders that understand sports property, including specialist sports lenders for larger stadium projects, with larger facilities available in suitable cases. Multi-sport clubs and clubhouse projects may also find sports clubhouse finance useful. It is free to enquire; any broker fee is disclosed separately before you proceed.
Usually with a mix of owner funding, development finance released in stages, a commercial mortgage once the work is complete, and sometimes the proceeds of selling surplus land. Smaller works may suit a secured loan, and community facilities may attract grants.
Yes, in suitable cases, though fewer lenders will lend against a stadium than a standard commercial property. Lenders look at the ground's value as a stadium and for other uses, the club's finances and any restrictions on the title. See commercial mortgages.
The club sells its ground to an investor and leases it back, releasing cash while it carries on playing there. The club gives up ownership and pays rent for the length of the lease, so take legal advice on the lease, rent reviews and any buy-back rights.
Often, yes. Works to meet The FA's ground grading standards, such as covered accommodation, turnstiles or floodlights, can be funded with a secured loan, asset finance for equipment and, for eligible community clubs, grants. Lenders will want to see that the works meet the grade the club needs.
The Football Foundation funds grassroots facilities, mainly for not-for-profit clubs, schools providing community use and local authorities. Eligibility depends on the club and the project, so check the Football Foundation's current criteria before relying on a grant.
Yes. Buying land or an existing training ground can be funded with a commercial mortgage, and new buildings with development finance or a secured loan. Pitches, floodlights and equipment can be funded separately.
Professional football club finance usually means working capital facilities, advances against income the club is owed, such as…

Football transfer fee finance lets a club that has sold a player draw the instalments still owed by the buying club upfront, by…

Education sector finance is business borrowing for independent schools, day nurseries and training providers, assessed against…
Apprenticeship and training providers usually need finance because they recruit, teach and assess for months before the income…
3G pitch finance usually combines grants and reserves with a term loan or secured loan, because the base and carpet are fixed…
Sports floodlight finance usually splits a project in two: LED fittings and controls can often go on asset finance, while…

Tell us what the funding is for. We search our panel of 300+ lenders, structure the case and approach the ones suited to it. No obligation, and free to enquire.