
Gyroplane finance: funding a new or used gyrocopter
Gyroplane finance spreads the cost of a new or used gyroplane, also called a gyrocopter or autogyro, over an agreed term.…
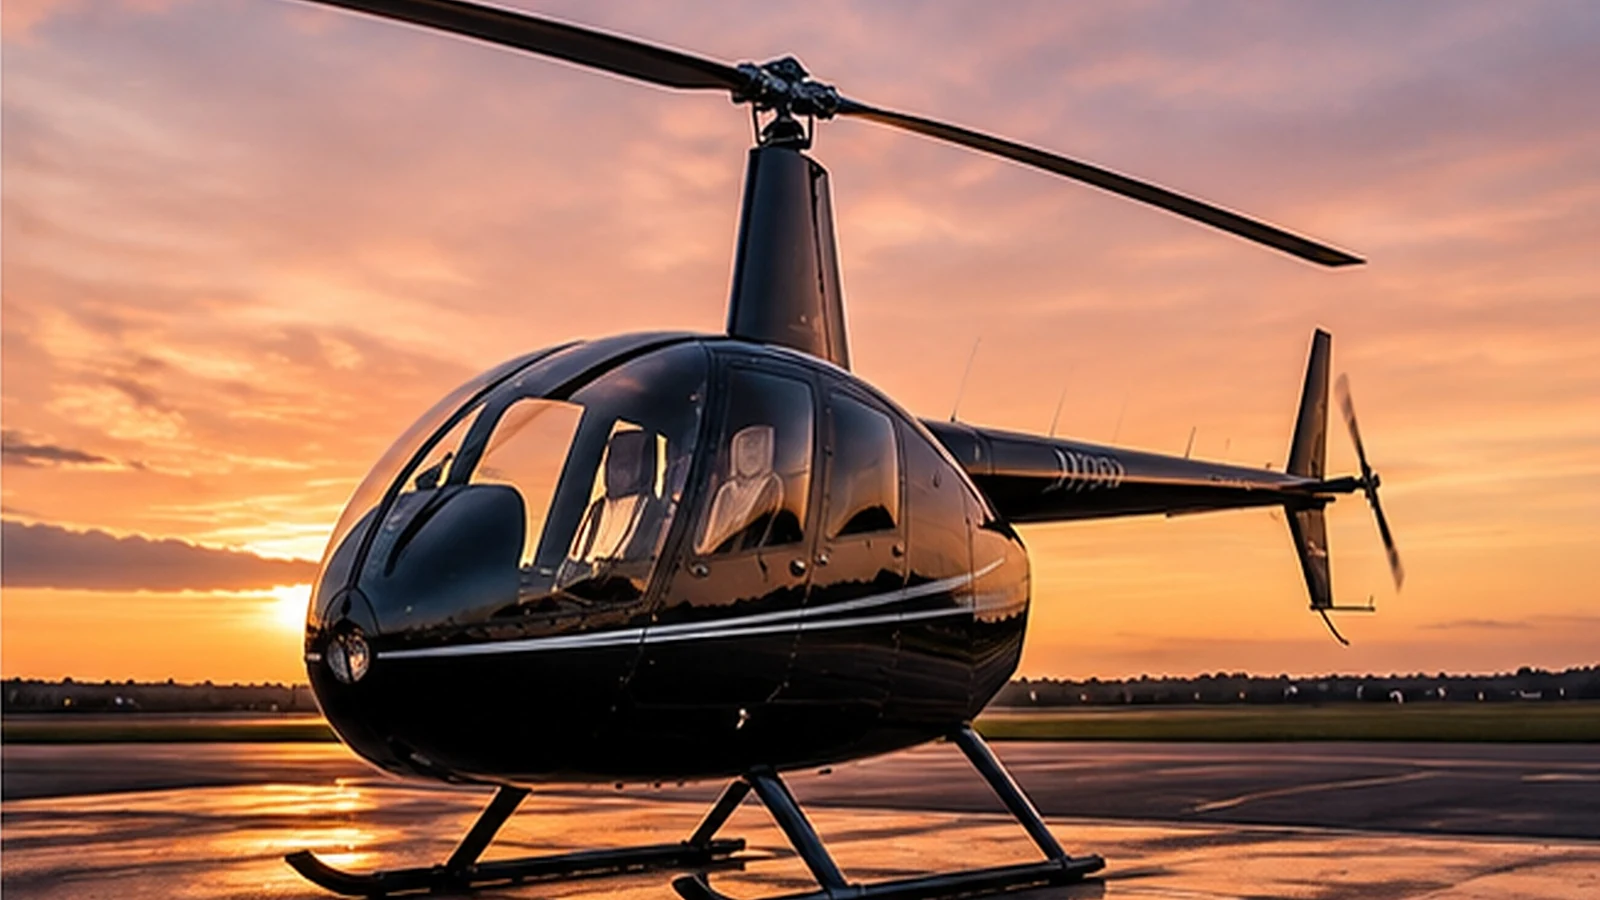
How to finance a helicopter in the UK, for private owners, training schools and operators: hire purchase, aircraft mortgages, leasing and what lenders check.
Explore funding options Prefer a quick call back? Leave your number
“He is fair and always gives advice that is in the best interest of his clients.”
In short
What you need to know.
Specialist aviation lenders look closely at the helicopter's hours, the time left before major overhauls and its maintenance records, as well as the buyer's finances and deposit.
About helicopter finance
Specialist knowledge. Better outcomes.
That makes helicopter finance a specialist market, where the lender's view of the aircraft matters as much as the borrower's accounts. This page explains how it works for private owners, training schools and operators. For other aircraft, see our aviation finance page.
Most helicopters for sale in the UK are listed by dealers, brokers and private sellers on aviation marketplaces and club noticeboards. Agree your finance in principle before you commit, so you know your deposit, term and monthly payment when you make an offer. For a private sale the lender will check that the seller owns the aircraft and that any finance against it is cleared, and will usually pay the seller directly once its security is in place. A pre-purchase inspection by a qualified engineer protects you and the lender.
Arkle Finance and Close Brothers are both on our panel, and both run specialist aviation teams. Arkle publishes aviation finance for light aircraft and helicopters, including a dedicated autogyro finance service, and Close Brothers Aviation & Marine funds light piston aircraft, turboprops, helicopters and vintage aircraft, according to their websites. Smart Funding Solutions is an independent broker and is not part of either lender. We approach the lenders whose criteria fit your aircraft and set the offers side by side.
A helicopter's engine and many major components have fixed lives, measured in hours or calendar time, after which they must be overhauled or replaced at significant cost. Lenders check how much life is left and may set the term so the loan is repaid, or a reserve is built, before a major overhaul falls due. Full logbooks and maintenance records are essential, and gaps reduce what a lender will advance.
A helicopter flown for hire, charter or training needs the operator to hold the right approvals, and the income from that work supports the repayments. Lenders will ask for the operating approvals, contracts or bookings, and the business accounts. The Civil Aviation Authority sets the rules on registration, maintenance and commercial operation.
Finance for an aircraft bought by a company, partnership or sole trader for its business is commercial lending. Finance for an individual buying an aircraft for personal or leisure flying can be regulated consumer credit, which follows different rules and protections. Tell us at the outset who will own the aircraft and how it will be used, so the right lenders and the right agreement are used.
Compare the total amount payable, fees, any balloon and the early settlement terms. Insurance, hangarage, scheduled maintenance and overhaul reserves are large ongoing costs, and lenders take them into account when they check affordability.
Before you buy, check the aircraft on G-INFO, the CAA register of UK aircraft. Commercial operators can find industry guidance from the British Helicopter Association.
The helicopter: make, model, age, hours, time to overhaul and records.
Your deposit, typically 10% to 30% of the price for aircraft.
For a business: accounts, bank statements, approvals and the income the aircraft generates.
For a private buyer: income, assets and credit history.
Insurance with the lender's interest noted, and where the aircraft is based.
How the main business finance structures work. Lenders set their own terms, so treat this as a guide to the questions to ask.
| Option | How you repay | Security | Often used for |
|---|---|---|---|
| Unsecured business loan | Fixed instalments, usually monthly | No charge over assets; a personal guarantee is usually required | Growth, stock, tax bills and cash flow |
| Secured business loan | Fixed instalments, often over a longer term | A charge over property or other assets | Larger sums, property and refinancing |
| Revolving credit facility | Interest on what you draw; repay and redraw | Varies by lender and case | Recurring or uneven cash flow gaps |
| Merchant cash advance | A share of future card takings | No charge over assets | Card-taking businesses with uneven months |
| Asset finance | Regular payments over the life of the asset | The asset being financed | Equipment, vehicles and machinery |
| Invoice finance | Settled as customers pay their invoices | Your unpaid invoices | Businesses waiting on customer payment |
General information only. Every lender has its own criteria, and all finance is subject to status.
| Structure | How it works | Often suits |
|---|---|---|
| Hire purchase | Deposit, then fixed payments; ownership passes at the end | Owners keeping the aircraft |
| Aircraft mortgage (secured loan) | A loan secured on the helicopter | Private buyers and companies |
| Leasing | Paying to use the helicopter without owning it | Operators renewing aircraft regularly |
| Refinance | Borrowing against a helicopter you already own | Funding an overhaul or another purchase |
Tell us the aircraft, the price, your deposit and who will own it. We match it against the aviation lenders on our panel, approach the ones that fit and present the case once, with the aircraft details and your accounts or income. The lender carries out its own checks and approval is always its decision. It is free to enquire, and any broker fee is disclosed separately before you proceed. To see your options now, use our instant quotes tool.
Yes. Specialist aviation lenders fund new and used helicopters through hire purchase, secured loans and leasing, for businesses and, with some lenders, private buyers. Expect a deposit and a close look at the aircraft's hours and records.
Some do, but they look closely at hours, time to overhaul and records. Many lenders set a maximum age at the end of the term, so an older helicopter may get a shorter term or need a larger deposit.
Yes. Lenders look at the school's accounts, student numbers, approvals and how the aircraft will be used. A newer school may be asked for a larger deposit and personal guarantees.
Often, yes, either as a loan or by refinancing a helicopter you already own. If the aircraft is already financed, speak to your existing lender first, as the agreement may restrict further borrowing.
Gyroplane finance spreads the cost of a new or used gyroplane, also called a gyrocopter or autogyro, over an agreed term.…
Golf buggy finance spreads the cost of a buggy fleet over several years, usually through hire purchase or leasing secured on…
Flying school aircraft finance helps flight schools and flying clubs buy or replace training aircraft, helicopters, gyroplanes,…
Glider finance spreads the cost of a glider or motor glider over an agreed term. Higher-value aircraft, such as new…
Light aircraft finance spreads the cost of a new or used light aircraft, such as a two-seat trainer, a four-seat tourer or a…
Microlight finance spreads the cost of a new or used microlight, from a flex-wing trike to a modern 600kg three-axis aircraft,…
What our clients say
“Simon was fast, kept us updated at all stages and was a real pleasure to work with on our asset finance. I highly recommend this company: excellent service all round.”
“Spoke with Simon, who managed to get me the loan I needed promptly. The whole process was very smooth and was completed within a few days.”
“Getting a business loan can feel like a bit of a minefield, but everything was broken down for me in great detail. Will use again in the future!”
“Simon was a pleasure to deal with and helped us find a business loan that matched our growth goals and future expansion plans.”
“I couldn’t source funding for my business, but the team got in touch within an hour and had it sorted within 24 hours. Fantastic service, and I would definitely use them again.”

Chat with Smart Funding
We usually reply in seconds
Please don't share bank details or passwords here. Calls on 01244 267694.