

Credit hire finance for accident replacement vehicle companies
Credit hire finance funds the gap between putting a not-at-fault driver into a replacement vehicle and being paid by the…
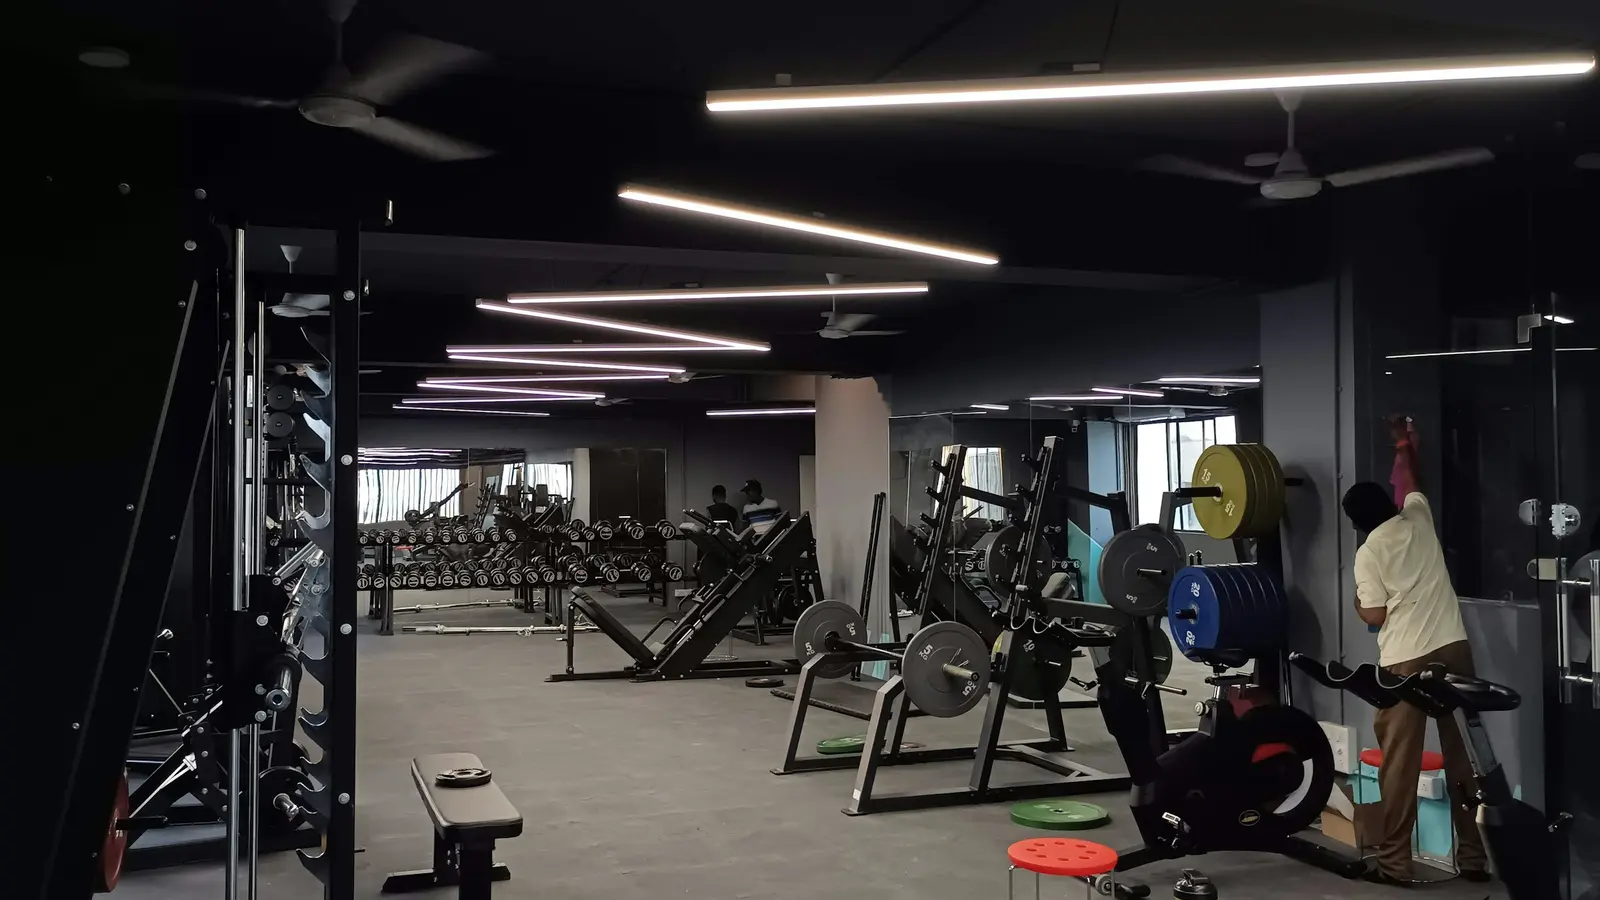
Compare operating leases, finance leases and hire purchase for treadmills, racks and studio kit, the lease terms to check and what lenders ask of gym owners.
Gym equipment finance lets a gym, studio or fitness centre spread the cost of cardio machines, strength equipment, free weights and studio kit over fixed monthly payments instead of paying a large sum up front. This guide is for owners opening a new site, refreshing tired equipment or adding a studio. The main options are operating leases, finance leases and hire purchase, and some agreements include servicing. Smart Funding Solutions, as a broker, compares equipment lenders and supplier-linked schemes so you can see which structure suits your plans.
The right choice depends on whether you want to own the kit, upgrade regularly or keep payments as low as possible.
A shorter rental where the leasing company keeps the risk on the equipment's value at the end. Payments tend to be lower because you are not paying for the full value. At the end, you return the kit, extend the rental or upgrade to newer models. Well suited to high-use cardio equipment that dates quickly.
A longer rental covering most of the equipment's working life. The lessor owns the kit throughout. At the end you can usually continue renting for a small secondary rental, or sell the equipment on the lessor's behalf and receive a share of the proceeds.
If you want to own the equipment, hire purchase spreads the cost over fixed instalments, with ownership passing to you after the final payment. It suits durable strength equipment, racks and free weights that last for many years, and you may be able to claim capital allowances.
| Operating lease | Finance lease | Hire purchase | |
|---|---|---|---|
| Own at the end? | No | No | Yes |
| Upgrades | Easy at end of term | Possible, less flexible | Sell or part-exchange |
| Best for | Cardio and tech-led kit | Lower cost over a longer term | Durable strength equipment |
Many gyms do not use a single agreement for everything. A common approach is to match the finance to how quickly each type of kit dates:
Before signing, total up every monthly payment across all agreements and compare it with realistic membership income, including a quieter month, rather than judging each quote on its own.
Used and refurbished equipment can sometimes be financed, depending on its age and the supplier.
New gyms can often be funded, particularly where owners have industry experience, though a deposit or guarantee may be requested.
If you also need funds for premises, fit-out or working capital, see our page on gym business loans. Smart Funding Solutions is a broker, not a lender: we discuss your equipment plans, approach suitable lenders for equipment finance and review the terms with you, while the lender makes the final decision. If you already own kit outright, asset refinancing can release cash against it. Clubs and wider sports businesses can read our sports business funding guide.
This guide is general information, not financial advice. Lenders set their own criteria, rates and terms, and all finance is subject to status.
Not ready for the full application? Leave a few details and a broker will call you to talk it through. It is free, with no obligation.
Yes, new gyms can often get equipment finance, especially where the owners have experience in the fitness industry and a credible business plan. Lenders may ask for a deposit or a personal guarantee because there is no trading record yet. Suppliers sometimes offer their own finance schemes, so compare those with independent lenders on total cost. Our page on gym business loans covers premises, fit-out and working capital.
It can be possible, because the equipment acts as security, but options are narrower and the cost is usually higher. Lenders will look at current affordability, membership numbers or forecasts, and the story behind any credit problems. A larger deposit or choosing kit that holds its resale value can help. Avoid several full applications in a short time. See bad credit asset finance for more detail.
Usually you are. Most gym equipment leases require the business to insure the kit against damage and theft for the full term, and the lender may ask to see the policy or be noted on it. Check the agreement for the exact requirements, as uninsured loss can leave you paying for equipment you no longer have. Servicing may be included in some agreements, but insurance rarely is.
Gym equipment finance agreements typically run over a few years, with operating leases tending to be shorter than finance leases and hire purchase, which can cover most of the kit's working life. The term should end before the equipment needs replacing, so high-use cardio machines often suit shorter agreements than racks and free weights. Compare the total cost at different terms against realistic membership income.
Credit hire finance funds the gap between putting a not-at-fault driver into a replacement vehicle and being paid by the…

Electrical equipment manufacturers typically fund surface-mount lines, test rigs and wiring equipment through asset finance,…

Oil and gas service companies usually fund rental tools, inspection kit, lifting equipment and offshore containers through…
Bakery equipment finance spreads the cost of ovens, provers, mixers, slicers and shop counters over fixed monthly payments,…

Meat processing equipment finance funds saws, mincers, packing lines, chillers, blast freezers and refrigerated vehicles…
Leisure business finance is borrowing for gyms, salons, spas, indoor and outdoor attractions, events companies, laundries and…
A short conversation is often enough to know which lenders will look at your case and how to present it. There is no obligation, and it is free to enquire.