

How to buy a pub: ownership options, finance and opening steps
To buy a pub, first decide whether you want the freehold, a free-of-tie lease or a tied tenancy, as this sets how much you need…
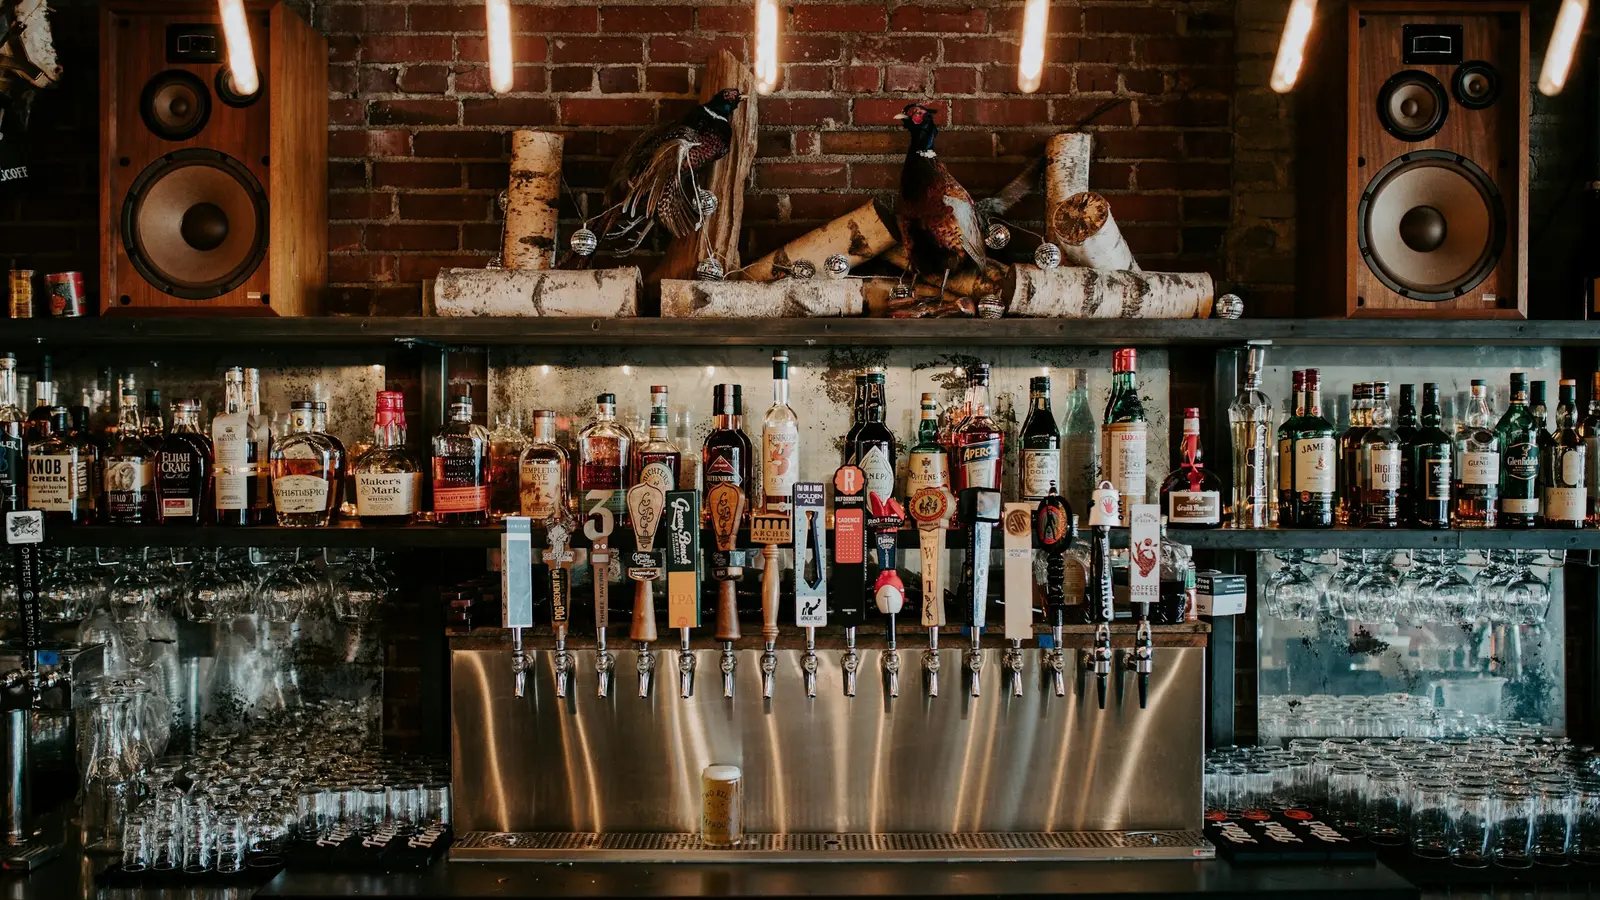
How a pub mortgage works when buying a freehold pub: what lenders assess, documents needed, costs, security and the alternatives for licensed premises.
Prefer a quick call back? Leave your number

A pub mortgage is a long-term commercial loan used to buy or refinance the freehold of a pub, secured on the property. Lenders value the pub as a trading business, so they assess its accounts, the split between drink and food income, the buyer's licensed trade experience and the deposit. Most buyers need a meaningful deposit and a credible business plan.
This page is for licensees, operators and hospitality groups buying the freehold of a pub, whether it is a free house you already run as a tenant, a trading pub coming to market, or a closed site you plan to reopen. A pub mortgage is the long-term loan used to buy that freehold, secured on the building and assessed largely on the pub's trade. Smart Funding Solutions is a broker, not a lender. We approach lenders on our panel of 300+ with appetite for licensed premises, arranging facilities from around £10,000 to £500,000+, with larger facilities available in suitable cases. If you need funding to run, refurbish or stock a pub rather than buy the building, our bar and pub loans page is the better starting point.
Not ready for the full application? Leave a few details and a broker will call you to talk it through. It is free, with no obligation.
A pub mortgage is a commercial mortgage secured on a freehold pub and repaid over a term of years, where the lender looks at both the property and the business trading from it. Unlike a standard commercial mortgage on an office or warehouse, a pub is valued as a trading business. Its worth depends heavily on what it takes over the bar and in the kitchen, so the trade and the operator matter as much as the bricks.
A pub mortgage suits an operator with licensed trade experience buying a pub that trades, or will trade, profitably enough to cover the repayments. Typical borrowers include:
It is harder for first-time operators with no licensed trade or hospitality management experience, and for closed or failing pubs with no current trade to show. Neither is impossible, but lenders usually want a larger deposit, a strong business plan, experienced staff or a phased approach using short-term funding first. If you are at the planning stage, our guide on how to purchase, fund and open a pub walks through the steps before finance.
Most pubs include accommodation for the licensee, and lenders generally treat this as part of the commercial operation. If a large share of the building would be your home, or the accommodation is separate enough to be a dwelling in its own right, the loan could fall into regulated territory, which is outside what we arrange. We check this at the outset.
A closed or underperforming pub can be bought with finance, but most lenders will not offer a long-term pub mortgage until the pub is trading again, so the purchase is usually done in two stages. The first stage is short-term funding to buy the site and carry out works, often a bridge or refurbishment facility, sized on the property's value as it stands. The second stage is a refinance onto a pub mortgage once the pub has reopened and built up a trading record, which lenders typically want to see over several months at least.
Lenders on the first stage look closely at the cost and timetable of works, your experience of turning sites around and whether the refinance is realistic. Allow for the time it takes to recruit staff, obtain or vary licences and build a customer base, and keep a working capital buffer for the early months.
Illustration only. This is a hypothetical example with round numbers and no lender committed to it. An experienced operator agrees to buy a closed village pub for £400,000 and budgets £100,000 for a new kitchen and redecoration. A short-term facility funds part of the purchase and works, with the operator's own cash covering the rest. After the pub has traded for a year, the operator applies for a pub mortgage on the strength of the new accounts and repays the short-term loan.
Buying a pub with a mortgage typically takes from several weeks to a few months, depending on the lender, the valuation and the legal work. Indicative terms can come within a few working days in straightforward cases. The specialist valuation and the legal work, including the transfer of the premises licence, stock, fixtures and any staff, are usually the longest stages. If the sale has a tight deadline or comes up at auction, bridging finance followed by a pub mortgage is an option some buyers use.
A pub mortgage is secured by a first legal charge over the freehold pub. Where you buy through a limited company, lenders usually ask for personal guarantees from the directors and may take a debenture over the company's assets, which covers fixtures, equipment and stock as well as the property. Some lenders ask for additional security over other property if the deposit is small. Our guide to debentures and fixed and floating charges explains how this works.
Pub mortgage costs are made up of interest plus several one-off fees, and pricing reflects the strength of the trade and the operator more than the building alone.
Budget separately for stock, any immediate repairs, opening working capital and purchase taxes, which are not covered by the mortgage. Our commercial mortgage calculator helps you model repayments.
The main alternatives are a leasehold purchase, bridging for a quick or distressed acquisition, or a refurbishment facility for a closed site.
Lenders assess the pub's trading record, the buyer's experience, the property and the price, and they test whether the trade will cover the repayments after realistic costs.
Lenders want to see several years of accounts for the pub, ideally with monthly figures, showing turnover, gross margins and profit. They look at the split between drink-led and food-led income, because the two carry different margins and risks. Volume trends, the effect of seasons and local events, and how the pub performed through recent cost pressures all form part of the picture.
Your track record in the licensed trade is central. Lenders ask how long you have run pubs or similar venues, at what scale and with what results. A personal licence and a record of compliance with licensing conditions help. Where experience is thin, a strong general manager or chef joining the business can partly fill the gap.
Whether the pub is free of tie, or will be tied to a brewer or pub company for some products, affects margins. A free house usually gives you more control over purchasing and pricing, which lenders reflect in their view of profit.
The valuer considers location, trading area, parking, outside space, kitchen and cellar condition, and any repairs the building needs. Listed buildings and older pubs can carry higher maintenance costs. Planning and licensing matters also count: the premises licence conditions, permitted hours and any restrictions on outside areas or live music.
Lenders project the pub's profit under your management, deduct a realistic salary for you, and compare what is left with the proposed repayments. Our DSCR calculator shows how that cover test works.
Lenders usually ask for the pub's trading figures, your experience and a plan for the business, and the quality of these documents shapes the terms on offer.

Our guide to writing a business plan for funding explains what makes forecasts credible to underwriters.
Owning the freehold gives control and builds equity, but it ties up capital and puts both the business and the property at risk if trade falls.
| Pros | Cons |
|---|---|
| No rent reviews or landlord restrictions | A sizeable deposit is usually needed |
| Free of tie purchasing can improve margins | You carry all repair and maintenance costs |
| Builds equity in the building over time | Pub values move with trading performance |
| Freedom to invest in rooms, kitchen or garden | Personal guarantees are often requested |
How the main business finance structures work. Lenders set their own terms, so treat this as a guide to the questions to ask.
| Option | How you repay | Security | Often used for |
|---|---|---|---|
| Unsecured business loan | Fixed instalments, usually monthly | No charge over assets; a personal guarantee is usually required | Growth, stock, tax bills and cash flow |
| Secured business loan | Fixed instalments, often over a longer term | A charge over property or other assets | Larger sums, property and refinancing |
| Revolving credit facility | Interest on what you draw; repay and redraw | Varies by lender and case | Recurring or uneven cash flow gaps |
| Merchant cash advance | A share of future card takings | No charge over assets | Card-taking businesses with uneven months |
| Asset finance | Regular payments over the life of the asset | The asset being financed | Equipment, vehicles and machinery |
| Invoice finance | Settled as customers pay their invoices | Your unpaid invoices | Businesses waiting on customer payment |
General information only. Every lender has its own criteria, and all finance is subject to status.
A pub mortgage buys or refinances the freehold, while a pub loan funds the business itself; many operators use both.
| Factor | Pub mortgage | Pub business loan |
|---|---|---|
| Purpose | Buy or refinance the freehold | Working capital, refurbishment, equipment, leasehold purchase |
| Security | Charge over the pub property | Often unsecured or a debenture with guarantees |
| Term | Long | Usually shorter |
| Valuation | Specialist trade valuation | Not usually required |
| Main test | Trade, experience and loan to value | Trading cash flow and credit |
We start by reviewing the pub's figures, your experience and the price to see how lenders are likely to view the deal, and we flag anything that may need addressing first, such as missing monthly accounts or a short trading record. We then prepare a proposal that presents the trade and your plan clearly and take it to lenders on our panel that fund licensed premises. We compare the terms, fees and guarantee requirements with you, and lenders make every credit decision. It is free to enquire; any broker fee is disclosed separately before you proceed. Contact us with the sale details and your experience.
Often, yes. Lenders value hands-on experience of running a pub's trade, staff and stock, whether as a tenant, manager or employee of a group. They will want detail on the size of the operation you ran and its results. A strong business plan and a meaningful deposit help bridge the step from manager to owner.
It depends on where the income comes from. If drink and food are the main earners and the rooms add to them, lenders usually treat it as a pub. If accommodation generates most of the income, it is more likely to be assessed as a small hotel or inn, which can widen or change the lender pool.
Community groups buying a pub, often through a community benefit society, usually combine share offers, grants and loans. Some lenders that support social enterprises will consider these purchases, but the assessment focuses on the group's governance and plan. Our social enterprise finance page covers this area.
Fixtures and fittings are usually included in the price, while stock is normally valued and paid for separately on completion. Some equipment may be leased or owned by a supplier rather than the seller, so check the inventory carefully. Lenders generally expect stock to be paid for from your own funds or working capital rather than the mortgage.
Yes, provided there is enough equity and the trade supports the higher borrowing. Lenders will want current accounts and a clear plan for the money, such as a new kitchen or letting rooms, showing how it will improve profit. Our commercial property refinance page explains the process.
To buy a pub, first decide whether you want the freehold, a free-of-tie lease or a tied tenancy, as this sets how much you need…
Most people buy a trading B&B with a commercial or semi-commercial mortgage, because the owner lives on site and the lender…

How a hotel is funded depends on the job. A purchase or freehold usually needs a commercial mortgage with a deposit; a large…

A hotel is usually bought with a commercial mortgage secured on the property and lent against its trading valuation, so both…
Wedding venues are usually bought or refinanced with a commercial mortgage, converted with staged or bridging finance, and…
Most cafes combine two or three types of finance rather than one loan: equipment finance or leasing for the espresso machine…

Tell us what the funding is for. We search our panel of 300+ lenders, structure the case and approach the ones suited to it. No obligation, and free to enquire.