
How to sell a funeral director business on the right terms
Selling a funeral home usually means choosing between a group, a neighbouring independent or your own staff, then agreeing how…
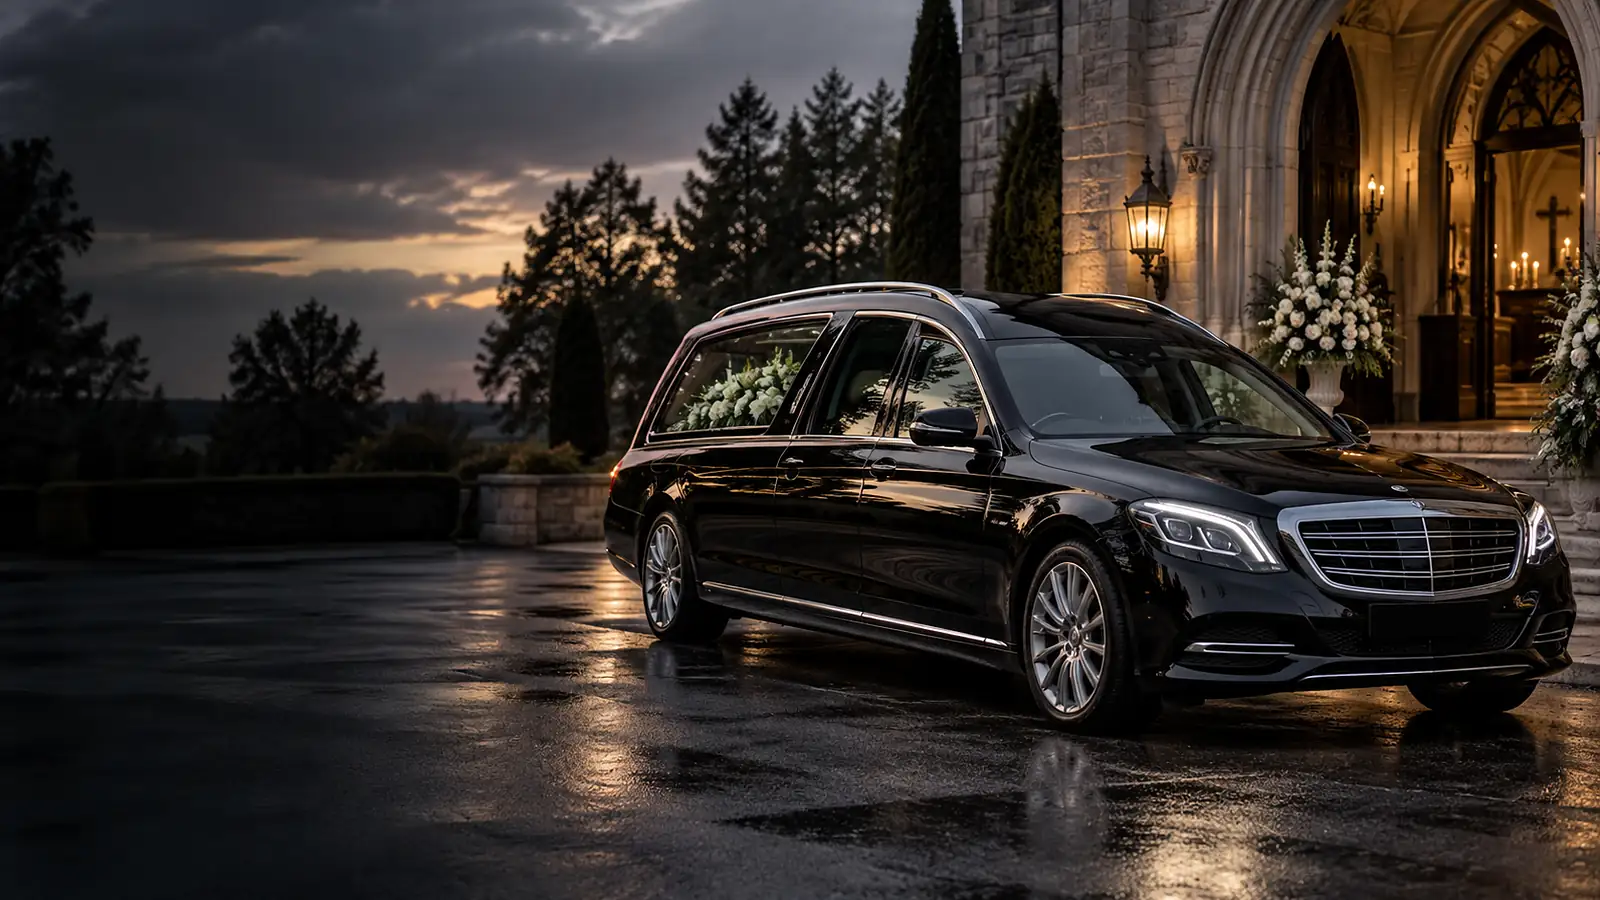
A buyer’s guide to funeral homes: how they earn, what to check on plans, premises and price rules, and how goodwill, property and fleet are funded.
Independent funeral homes change hands less often than most small businesses, and when they do the buyer is frequently someone already in the profession: a funeral arranger or conductor taking over from the family that trained them, a neighbouring independent adding a branch, or a regional group. This guide explains how a funeral business actually earns, what to check before you commit, and how purchases are typically funded. Smart Funding Solutions is a broker, not a lender: we search our panel of 300+ lenders and arrange acquisition funding from £10,000 to £20 million. For the full range of sector borrowing, see our funeral director finance hub.
Before you look at the asking price, understand the three numbers that drive a funeral home's profit.
Cash flow has its own quirk. The funeral director usually pays crematorium or cemetery fees, officiants and other third-party costs on the family's behalf, then waits to be paid, often until the estate's bank releases funds or probate is granted. A funeral home can be profitable and still carry a sizeable ledger of unpaid accounts.
The price usually covers several distinct things, each of which a lender treats differently.
Standard legal and financial checks apply, but several issues are particular to this sector:
| Element | Typical funding | Trade-off |
|---|---|---|
| Goodwill | Term loan, supported by your deposit | Personal guarantees are common; lender will test profit after your own salary |
| Freehold premises | Commercial mortgage | Longer term; the building becomes security and needs a valuation |
| Hearses and limousines | Vehicle finance or refinancing of existing fleet | Adds a monthly commitment; keeps the main loan focused on goodwill |
| Part of the price | Deferred payments to the seller | Reduces borrowing; lenders usually want it to rank behind them |
| Disbursements and early months | Working capital or a revolving facility | Easy to leave permanently drawn |
Where the family is selling to a long-serving employee, deferred consideration often does a large share of the work, because the seller understands the business and wants it to continue under the name. Our guide to vendor finance and deferred consideration explains how lenders treat it. A buyer from inside the business is effectively a management buyout; see management buyout finance.
This illustration uses hypothetical, rounded figures. A funeral conductor agrees to buy the two-branch family business he has worked in for years, for £700,000 including the freehold of the main branch. The freehold is funded with a commercial mortgage. The goodwill is funded by his £80,000 of savings, a term loan and £100,000 deferred to the family over three years. The hearse and limousine are near-new and carry existing finance, which is novated to him. A modest revolving facility covers disbursements while the business moves onto his own bank account. The lender's main question is whether the adjusted profit, after paying him a market salary, covers all four commitments with room to spare in a quieter year.
£137,500A transaction we arranged£137.5K to fund an accountancy practice acquisition.An established firm had an acquisition agreed. We structured the funding around the transaction and got it completed.The largest risk is paying for goodwill that leaves with the seller. A planned handover, the name kept and deferred payments linked to the transition all help. The second is margin erosion: if direct cremation and plan work grow in your area, volumes may hold while revenue per funeral falls, so model a lower average fee as well as your base case. Third, the freehold can make the deal look well secured while the business still struggles to service the combined debt. Consider whether leasing the building from the family, at least initially, reduces the amount you need to borrow. Taking on a funeral home with too little working capital is also a common mistake, because disbursements must be paid before families settle.
Before you agree a price, it helps to know how the seller's figure was reached and how a lender's valuer will look at it. Most independent funeral businesses are valued on their maintainable profit, with the premises, if included, valued separately by a surveyor.
The starting point is the profit the business can be expected to keep earning under new ownership. That figure is usually adjusted to remove one-off costs and the family's own drawings, then reduced by a market salary for the people who will actually run it. A firm where the seller conducts most funerals and takes little pay can look far more profitable on paper than it will be once you replace them.
A multiple is then applied to that adjusted profit. What pushes the multiple up or down is specific to the sector:
Lenders do not simply accept the agreed price. They test whether the adjusted profit covers all the repayments with room to spare, and a price that fails that test will usually need more deposit or more deferred consideration. Our guide to how to value a business explains the main valuation methods in more detail.
We look at the business as a funeral home, not a generic acquisition: volumes, fee trend, plan mix, premises and fleet. We then approach lenders on our panel whose appetite fits and present the case with that detail, so the credit team can see why demand is durable. We can also arrange the vehicle and working capital elements alongside the main loan. Lenders make the decision. It is free to enquire; any broker fee is disclosed separately before you proceed. If you are on the other side of the deal, read how to sell a funeral director business, and for deal structures across sectors see acquisition finance.
This guide is general information, not financial advice. Lenders set their own criteria, rates and terms, and all finance is subject to status.
Not ready for the full application? Leave a few details and a broker will call you to talk it through. It is free, with no obligation.
In England and Wales there is currently no licensing scheme for funeral directors, although the CMA's price transparency rules apply and trade association membership brings its own standards. In Scotland funeral directors must follow a statutory code of practice, and the Scottish Government has consulted on a licensing scheme. Check the current position for the nation you are buying in.
It is possible, but lenders are cautious. Expect to need a larger deposit, a longer handover and a strong manager staying on. Some buyers work in the business before completing, or buy alongside an experienced partner.
Buying the freehold gives you control of a building that is hard to replace and adds security for lenders, but it increases the amount you need. Leasing from the family reduces borrowing at the start; if you do, make sure the lease is long enough and includes an option to buy later.
Plans are held by the FCA-authorised plan provider, not the funeral director. Whether the business continues to carry out those funerals depends on the provider's agreement with the new owner, so get written confirmation during due diligence.
Most lenders expect a buyer to put in some of their own money when buying a funeral home, with the exact amount depending on the lender, the deal structure and whether the freehold is included. A freehold can support more borrowing through a commercial mortgage, while goodwill is harder to lend against. Deferred consideration from the seller can reduce the cash needed on completion. Our acquisition finance page explains how deals are usually structured.
It depends on the size of the business, whether a freehold is included and how organised the seller's records are. Due diligence, plan provider consents, a property valuation and the legal work on the loan and any lease all run in parallel, and any one of them can set the pace. Starting the funding conversation before heads of terms are signed usually saves the most time.
Starting from scratch avoids paying for goodwill, but you have to build local trust, find premises with suitable facilities and fund the early months with little income. Buying gives you an established name, volumes and premises from day one, at a higher upfront cost. Lenders generally find an acquisition with a trading history easier to assess. See funeral director start-up finance for the other route.
Selling a funeral home usually means choosing between a group, a neighbouring independent or your own staff, then agreeing how…
Funeral home start-up funding usually combines a start-up or unsecured loan for fit-out and early running costs, asset finance…
To buy an architecture practice, identify a firm whose people, sectors and order book you want, then value it on normalised…
An accountancy partner buy-in loan is personal borrowing, repaid from your profit share, that funds a capital contribution to a…
A loan to buy an optician's practice is usually a term loan for the goodwill, combined with your own deposit and sometimes…
A goodwill loan funds the part of a business price that is not bricks, equipment or stock: the client list, patient base, NHS…
Our clients say
Trusted by UK businesses across every sector.
“Simon was fast, kept us updated at all stages and was a real pleasure to work with on our asset finance. I highly recommend this company: excellent service all round.”
“Spoke with Simon, who managed to get me the loan I needed promptly. The whole process was very smooth and was completed within a few days.”
“Getting a business loan can feel like a bit of a minefield, but everything was broken down for me in great detail. Will use again in the future!”
“Simon was a pleasure to deal with and helped us find a business loan that matched our growth goals and future expansion plans.”
“I couldn’t source funding for my business, but the team got in touch within an hour and had it sorted within 24 hours. Fantastic service, and I would definitely use them again.”
A short conversation is often enough to know which lenders will look at your case and how to present it. There is no obligation, and it is free to enquire.