
Food manufacturing finance for producers, bakeries and processors
Food manufacturing finance usually pairs asset finance for ovens, mixers, packing lines and refrigeration with invoice finance…
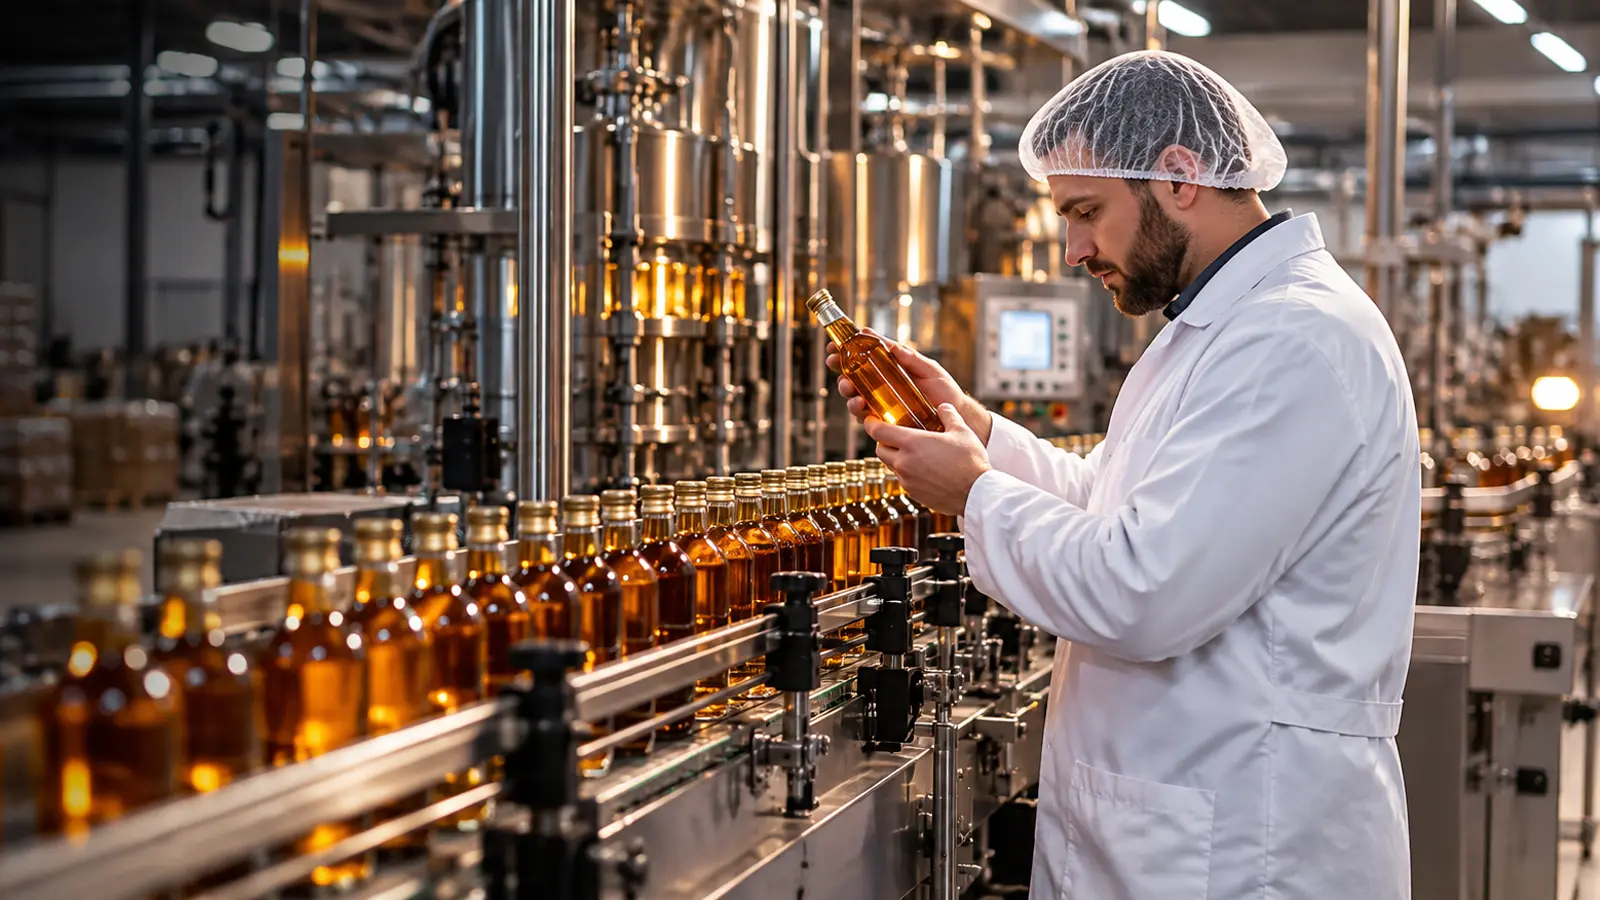
How UK distilleries fund stills, bottling and years of maturing spirit: cask-backed lending, duty suspension, working capital and what lenders check.
“A very quick and efficient service from Simon.”
In short
Supporting distilleries at every stage.
Lenders focus on the independent valuation of that maturing stock, who controls the warehouse it sits in, and how unaged spirits such as gin carry the business until the casks are ready.
The operating cycle
Cash leaves the business at every stage before it comes back. Each stage below is a point where the right facility can carry the gap.
“He is fair and always gives advice that is in the best interest of his clients.”
Orders, contracts or customers secured.
Stock, materials and equipment paid for up front.
Asset finance →Wages and suppliers paid on time.
Working capital →The work is done or the goods are sold.
Customers pay, sometimes weeks later.
Invoice finance →VAT and Corporation Tax fall due.
HMRC loans →Growth, a new site or new equipment.
Business loans →A transaction we arranged
£100,000
£100,000 for a distillery, matched to the right lender.
Working capital for production runs, bottles, ingredients and stock ageing ahead of sales.
Read the transactionAbout distillery finance
Specialist knowledge. Better outcomes.
This page is for owners of UK whisky, gin, rum and vodka distilleries, from a single-still craft operation to an established producer laying down several hundred casks a year, who need to pay for equipment, fill more casks or carry the cost of spirit that cannot be sold for years. Smart Funding Solutions is a broker, not a lender: we look for lenders across the whole market that understand bonded stock and distilling equipment, and arrange facilities from £10,000 to £20 million. It sits within our manufacturing finance section; beer producers should read our page on brewery finance, which deals with faster-turning stock, while wine producers, whose sparkling wine also spends years maturing before sale, should see vineyard and winery finance.
Choose the need, and we’ll show you how lenders usually structure it.
Yes. Anyone producing spirits in the UK needs an alcoholic products producer approval from HMRC before distilling, and producing without one is an offence that carries a penalty. HMRC aims to deal with applications within 45 working days, longer if information is missing, and it carries out fit and proper checks on the business and every key person, looking at tax history, convictions, record keeping and whether the business is commercially viable. The application includes a premises plan showing each still and vessel and where spirit will be stored in duty suspense, and HMRC can visit before deciding. Lenders take that timetable into account, so we arrange distillery finance with the still on order and the facility ready to draw on delivery, rather than leaving the founder paying for kit that cannot legally be used.
Yes, in many cases. A copper pot still, a column, fermenting vessels and a bottling line are recognisable assets with a resale market, so asset finance can be agreed while the approval is pending, with the lender paying the supplier on delivery. Lenders want to see that the application has gone in, the premises are secured and the founder has the experience or training to run the still, and they may ask for a larger deposit from a business with no trading history. Working capital to buy botanicals, bottles and labels is harder to raise before approval and usually comes from the founders or equity until sales begin.
HMRC explains approval for alcoholic products producers. Our distillery finance page covers casks and stock, machinery finance covers stills and bottling lines, and brewery finance covers a brewery adding spirits. Instant Quotes lets a new distiller see which panel lenders back stills, before a credit search is ever made.
Yes, and the bill is predictable enough to plan for. Duty is charged on spirit when it leaves duty suspension, which means the moment cases go out of the bonded store to a UK customer, not when the spirit is made. A distillery that ships a large Christmas order in November therefore faces a duty bill in December, often weeks before the trade customers pay their invoices. A revolving credit facility sized to the peak months, a short term business loan or invoice finance against the trade debtors can carry that gap, and lenders look at the sales ledger, the duty paid in previous months and the stock held in bond. We arrange working capital for distillers around the duty calendar, so the money is in place before the busy quarter rather than after the first reminder from HMRC.
Monthly, after the spirit leaves duty suspension. Each calendar month is an accounting period, the Alcohol Duty return for it is due online by the 15th of the following month, and the duty must reach HMRC by the 25th of that month, or the last working day before it if the 25th falls on a weekend or bank holiday. Spirit released in November is declared on the return due by 15 December and paid by 25 December. A nil return is still required in a month with nothing to declare. The amount is worked out on the litres of pure alcohol released, so a 70cl bottle at 40% contains 0.28 litres of pure alcohol and pays duty at the rate HMRC publishes for its strength band.
HMRC sets out Alcohol Duty returns and payments. Our revolving credit facility page covers seasonal cash flow, invoice finance explains borrowing against trade invoices, and VAT loans covers the VAT quarter that follows. Instant Quotes checks panel lenders for a duty or tax bill while keeping your credit record clean.
A brewery sells most of what it brews within weeks. A whisky distillery spends money on barley, energy, casks and warehousing today and may not sell that spirit for three, five or twelve years. Spirit sold as whisky in the UK must spend at least three years in oak, and for Scotch the GOV.UK guidance on producing Scotch Whisky sets out where and how that maturation must happen. Every cask filled is a long-dated asset that has already been paid for.
That shapes the funding situations distillers bring to us:
Spirit is produced and stored in an HMRC-approved excise warehouse, where it is held without duty paid. HMRC's Excise Notice 196 covers who must be approved to hold goods in duty suspension. For a lender, two consequences follow. First, the stock's value is a duty-free value, and a buyer in a forced sale would take it on in bond. Second, the warehousekeeper controls physical release, so a lender lending against casks in a third-party bonded warehouse will want written acknowledgement of its interest from the warehousekeeper and a way to stop casks being moved without consent. Clean warehouse records, with each cask's number, fill date, cask type and regauged strength, make this far easier.
Borrowing against stock that will not be sold for years compounds cost: interest accrues every year the cask matures, and a dip in the bulk whisky market can reduce the valuation the facility depends on. Over-filling casks on borrowed money is a common way for a young distillery to run out of headroom. Alternatives worth considering include contract distilling for others to bring in revenue, equity crowdfunding, which many craft distillers have used, and selling some casks to private buyers. Cask sales raise cash early but give away future margin, and selling casks as an investment product attracts regulatory and reputational scrutiny, so take legal advice first. If a duty bill is the pinch, compare a short-term facility with a Time to Pay arrangement or a tax loan. Directors should also read our guide to personal guarantees before signing for working capital.
Volume in original litres of pure alcohol, fill dates, cask types and where each cask sits. Gaps or loose records are the quickest way to lose a cask-backed lender.
Who valued it, on what basis, and how it compares with recent bulk trades of similar spirit.
Whether aged spirit is earmarked for your own bottlings, bulk sale to blenders or private cask sales, and the evidence of demand for each.
Up-to-date Alcohol Duty returns and payments, and no history of HMRC assessments for warehouse discrepancies.
Margins on gin and other quick-release products after duty, and whether they cover overheads without draining the stock budget.
Many craft distilleries rely on the founder's story and relationships. Lenders ask who runs production and sales if that person steps back.
| Need | Finance that often fits | Trade-off to weigh |
|---|---|---|
| Stills, mash tun, washbacks | Hire purchase or a finance lease, sometimes with staged drawdown during build | Made-to-order copper has a niche resale market, so lenders may want a larger deposit |
| Bottling line, labeller, tanks | Asset finance on standard terms | Easier to fund than stills, but check it will be busy enough to beat contract bottling |
| Casks already maturing | Specialist cask-backed or inventory lending | Advance is a cautious share of independent valuation, and fewer lenders offer it |
| Grain, botanicals, glass, gift packaging | Revolving credit or a working capital loan | Usually needs a personal guarantee; size it to the seasonal peak |
| Distributor and retailer invoices | Invoice finance | Works only once trade sales are steady; promotions and listing fees dilute what can be advanced |
| Distillery building or bonded warehouse | Commercial mortgage | Specialist buildings are valued cautiously; visitor-centre value depends on trading |
This is the distinctive part of distillery finance. A small group of lenders will advance against spirit in bond, using an independent valuation that reflects age, cask type, strength and the likely market for the spirit as bulk or bottled product. Facilities are often structured so the borrowing rolls over or is reduced as casks are bottled and sold, rather than repaid in level monthly instalments. Expect regular stock audits and a covenant linking the borrowing to the latest valuation. Our general guide to stock finance explains why lenders use forced-sale values; aged spirit is one of the few stocks that can grow in value while it sits.
Unaged spirits turn over quickly, so they are financed like any fast-moving drinks product: a revolving facility for botanicals and glass before the Christmas and summer peaks, and invoice finance once distributors and multiples are paying on terms. Our page on seasonal business finance covers sizing a facility to the peak.
Any broker fee is disclosed separately before you proceed.
See what lenders could offer your business, in minutes
Tell us how much you need and what it is for. Instant Quotes shows which lenders on our panel fit your business, then a broker helps you choose the right option.
Prefer to talk it through? Call 01244 267694
Often yes, but the lender will need the warehousekeeper to acknowledge its interest and agree not to release the casks without consent. Make sure your storage agreement allows this, and that the warehouse records identify your casks individually by number.
It is harder, because there is no trading record and no aged stock yet. Asset finance on stills and bottling equipment with a deposit, founders' capital, equity investment and sales of unaged spirits are the usual starting points. Cask-backed lending tends to become available once a meaningful stock of spirit has been laid down and valued. Our start-up business loans page sets out what lenders expect from a business with no filed accounts.
Not always. Many are structured so the balance is reduced as casks are bottled or sold, with interest serviced or rolled up depending on the lender. The structure matters as much as the advance, because level monthly repayments on stock that will not sell for years can strain cash flow.
Some will, particularly where the still is from a known coppersmith and can be removed and resold. Expect an inspection, a larger deposit and possibly additional security, since there are few buyers for used stills.
Yes, a craft gin distillery can get distillery finance without aged stock, because gin is sold quickly and lenders assess it more like other drinks manufacturing. Asset finance for stills and bottling equipment, working capital for glass and botanicals, and invoice finance against trade customers are the usual routes. Lenders look at sales channels, margins after Alcohol Duty and the owners' credit history. Our guide to plant and machinery finance covers equipment funding.
Yes. Buying an established distillery is usually funded with acquisition finance: a loan sized on the business's recent profits, your own contribution and sometimes part of the price paid to the seller after completion. Lenders look most closely at the stock of maturing spirit and how it is valued, the brands and route to market, the stills and premises, and the duty and bonded warehouse position. You can see which lenders on our panel fund purchases like yours with Instant Quotes.
Yes. Producing spirits needs an alcoholic products producer approval from HMRC, and producing without one is an offence. HMRC aims to decide within 45 working days, runs fit and proper checks on the business and key people, and needs a premises plan showing each still and where spirit is stored in duty suspense. Smart Funding Solutions, a drinks sector finance broker, times distillery finance around the approval.
Often, yes. Stills, fermenters and bottling lines have a resale market, so asset finance can be agreed while approval is pending, with the supplier paid on delivery. Lenders want proof the application is in, the premises secured and the founder's experience, and may ask a new business for a larger deposit. Working capital is harder to raise before approval.
Yes. Duty is charged when spirit leaves duty suspension, so a big pre Christmas shipment creates a duty bill weeks before trade customers pay. A revolving credit facility, a short term loan or invoice finance can cover the gap, with lenders looking at the sales ledger, past duty payments and stock in bond. Smart Funding Solutions plans distillery working capital around the duty calendar and sources the lender.
Monthly. Each calendar month is an accounting period, the Alcohol Duty return is due by the 15th of the following month and payment must reach HMRC by the 25th, or the last working day before it. Spirit released in November is paid by 25 December. Duty is calculated on litres of pure alcohol, so a 70cl bottle at 40% holds 0.28 litres.
Food manufacturing finance usually pairs asset finance for ovens, mixers, packing lines and refrigeration with invoice finance…
Electrical equipment manufacturers typically fund surface-mount lines, test rigs and wiring equipment through asset finance,…
Oil and gas service companies usually fund rental tools, inspection kit, lifting equipment and offshore containers through…
Engineering business loans usually combine asset finance for machine tools and fabrication equipment with a working capital…
Woodworking machinery finance is usually hire purchase or leasing for CNC routers, beam saws, edgebanders and moulders, secured…
Packaging machinery finance usually means hire purchase or leasing for converting equipment such as die-cutters, folder-gluers…
What our clients say
“Simon was fast, kept us updated at all stages and was a real pleasure to work with on our asset finance. I highly recommend this company: excellent service all round.”
“Spoke with Simon, who managed to get me the loan I needed promptly. The whole process was very smooth and was completed within a few days.”
“Getting a business loan can feel like a bit of a minefield, but everything was broken down for me in great detail. Will use again in the future!”
“Simon was a pleasure to deal with and helped us find a business loan that matched our growth goals and future expansion plans.”
“I couldn’t source funding for my business, but the team got in touch within an hour and had it sorted within 24 hours. Fantastic service, and I would definitely use them again.”

Chat with Smart Funding
We usually reply in seconds
Please don't share bank details or passwords here. Calls on 01244 267694.