
Pub and bar loans for refits, stock and buying a pub
What a pub can borrow depends on how it is held and how it trades. A freehold purchase usually needs a pub or commercial…
Why some lenders avoid shisha lounges, which will consider them, and how to fund a fit-out, smoking area, equipment or second site with the right paperwork.
Explore funding options Prefer a quick call back? Leave your number
“Fantastic customer service, highly recommend!”
In short
Supporting shisha bars at every stage.
Merchant cash advances and unsecured loans are the common routes for fit-outs and working capital, with asset finance for heaters, canopies and furniture. The harder part is the lender: many will not consider the sector, so approaching the few that will, with licences, lease and card statements ready, matters most.
The operating cycle
Cash leaves the business at every stage before it comes back. Each stage below is a point where the right facility can carry the gap.
“He is fair and always gives advice that is in the best interest of his clients.”
Orders, contracts or customers secured.
Stock, materials and equipment paid for up front.
Asset finance →Wages and suppliers paid on time.
Working capital →The work is done or the goods are sold.
Customers pay, sometimes weeks later.
Invoice finance →VAT and Corporation Tax fall due.
HMRC loans →Growth, a new site or new equipment.
Business loans →About shisha bar finance
Specialist knowledge. Better outcomes.
Owners use it for fit-outs, heated outdoor seating areas, equipment, stock, marketing, working capital and premises. Some mainstream lenders are cautious about the sector because of its regulatory requirements and late-night trading, so finding a lender that will consider your application matters as much as the product.
Smart Funding Solutions is a broker, not a lender. We approach only lenders willing to consider shisha businesses and suited to your circumstances. This page is part of our hospitality business loans section.
Choose the need, and we’ll show you how lenders usually structure it.
A fixed sum repaid in regular instalments without pledging property. Directors are usually asked for a personal guarantee, and costs are typically higher than for secured borrowing. Fixed repayments make cash flow easier to forecast. See unsecured business loans.
An advance repaid as a percentage of your card takings, so repayments fall in quieter weeks. It relies on card sales rather than assets, which can suit shisha lounges with strong card income. It can cost more than a term loan. Read about the merchant cash advance.
Borrowing against property or other assets can provide larger sums at lower cost for established businesses, but the asset is at risk if repayments are missed.
Asset finance through hire purchase or leasing spreads the cost of equipment, heaters, canopies and furniture, with the equipment as security. Where your own bank will lend to the sector, an overdraft can add a short-term buffer.
To buy your premises, a commercial mortgage involves an assessment of your accounts and future earnings, a property valuation and legal work before funds are released.
A shisha lounge trades mostly in the evening and late at night, earns much of its margin on pipes and soft drinks rather than food, and depends on an outdoor or substantially open smoking area to operate lawfully under smoke-free legislation. Local councils enforce those rules, and a lounge that falls foul of them can face fines or restrictions that hit income overnight. Lenders therefore look harder at compliance, the premises lease and how much trade is taken by card, and some simply do not lend to the sector.
The practical upshot is that a well-documented, compliant lounge with clear card takings can often find finance, but applying to the wrong lenders wastes time and leaves unnecessary searches on your credit file.
Costs depend on the product, the amount, the term, your credit profile, trading figures and any security. Compare the total repayable, fees and early repayment terms, not just the headline rate.
many lenders want to see a minimum period of trading; start-ups have fewer options.
bank and card terminal statements.
evidence that your premises and smoking areas meet smoke-free law and that you hold the licences you need, such as for late-night refreshment or alcohol.
of the business and its owners.
especially for new sites and larger sums.
property, equipment or a personal guarantee, depending on the product.
Lenders that will fund a shisha lounge want to see that the products, premises and permissions are all in order.
Drinks suppliers to bars are covered on our brewery finance page.
Waterpipe tobacco is subject to UK tobacco duty, and lounges must buy duty-paid stock. Non-duty-paid tobacco can be seized, so lenders ask where stock comes from.
Selling hot food or drink after 11pm, or alcohol at any time, needs a licence from the council. Lenders check the licence covers the hours traded; see GOV.UK on premises licences.
Lit charcoal brings fire and carbon monoxide risk. Lenders and insurers ask about fire risk assessments and ventilation; see workplace fire safety.
Several asset finance lenders on our panel exclude licensed clubs and bars by SIC code, and others treat them as a sector they dislike, so card-based funders are often the route.
It is free to enquire; any broker fee is disclosed separately before you proceed. To discuss your requirement, you can start an enquiry online.
It is harder without trading history. Lenders will focus on your experience, business plan, personal credit and how much you are investing. A government-backed Start Up Loan, asset finance for equipment or secured borrowing may be possible. Once you have several months of trading and card data, more options usually open up.
It is harder, because lenders rely on bank and card terminal statements to see trade, and cash sales hide it. Putting most takings through the card terminal, banking cash promptly and keeping accurate records all help. Card-based products depend on card income specifically, so a lounge taking mostly cash may be limited to other routes. Our page on the merchant cash advance explains how card-based funding is assessed.
It can. Lenders look closely at compliance with smoke-free law, because a lounge facing fines or restrictions can lose income overnight. An unresolved complaint or enforcement action will need explaining, and some lenders may wait until it is settled. Having the council's position on your smoking area in writing, especially after a complaint or inspection, gives lenders the evidence they need. Showing that the lease permits the outdoor area for longer than the loan term also helps.
Adverse credit narrows an already limited pool of lenders, but it does not always rule out shisha bar finance. Lenders weigh the business's and owners' credit history alongside card takings, trading history and compliance, so a well-run lounge with clear card income can sometimes offset an older, explained problem. Applying to lenders that do not consider the sector leaves unnecessary searches on your file. See our guide to bad credit business loans.
A lender can make a decision within a few working days in straightforward cases, once it has everything it needs. The main delays come from approaching lenders that do not consider the sector, or from missing paperwork. Having six to twelve months of bank and card statements, your licences, any council correspondence about the smoking area and your lease ready speeds things up. Buying premises with a commercial mortgage takes longer because of valuation and legal work.
Yes. Buying an established shisha lounge is usually funded with acquisition finance: a loan sized on the business's recent profits, your own contribution and sometimes part of the price paid to the seller after completion. Lenders look most closely at card takings and how much trade is in cash, the lease, the licences and compliance of the smoking area with the law and council conditions. You can see which lenders on our panel fund purchases like yours with Instant Quotes.
What a pub can borrow depends on how it is held and how it trades. A freehold purchase usually needs a pub or commercial…
Most people buy a trading B&B with a commercial or semi-commercial mortgage, because the owner lives on site and the lender…
Most cafes combine two or three types of finance rather than one loan: equipment finance or leasing for the espresso machine…
Choose hire purchase if you want to own long-life items such as a combi oven or cold room, leasing if you want a lower up-front…
Most street food traders fund the first season from savings and a Start Up Loan, then use asset finance for a trailer,…
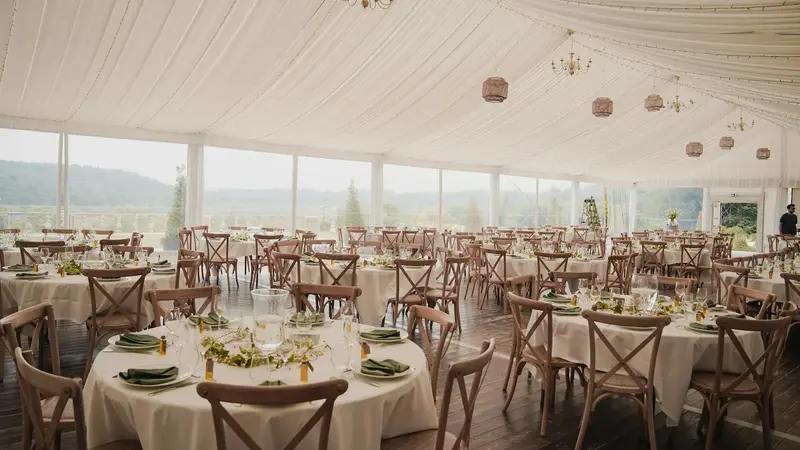
Most wedding and event businesses need finance for two things: kit and timing. Marquees, furniture, lighting and vans usually…
What our clients say
“Simon was fast, kept us updated at all stages and was a real pleasure to work with on our asset finance. I highly recommend this company: excellent service all round.”
“Spoke with Simon, who managed to get me the loan I needed promptly. The whole process was very smooth and was completed within a few days.”
“Getting a business loan can feel like a bit of a minefield, but everything was broken down for me in great detail. Will use again in the future!”
“Simon was a pleasure to deal with and helped us find a business loan that matched our growth goals and future expansion plans.”
“I couldn’t source funding for my business, but the team got in touch within an hour and had it sorted within 24 hours. Fantastic service, and I would definitely use them again.”

Chat with Smart Funding
We usually reply in seconds
Please don't share bank details or passwords here. Calls on 01244 267694.