
£82.5K arranged against modest turnover and strong cash.
The amount was large relative to turnover. We placed it with a lender willing to look at the whole financial picture.
Business fundingRead the transaction
Compare small business loan options side by side, see what they cost and what lenders check, and learn how to build a stronger application with a broker's help.
Explore funding options Prefer a quick call back? Leave your number
Most small firms borrow through an unsecured loan backed by a director's guarantee, a secured loan against property, or a product matched to how cash comes in, such as asset finance, invoice finance or a merchant cash advance. Approval rests on trading history, bank statements, affordability and credit record, and pricing varies widely between lenders, so compare offers on the total amount repayable.
A small business loan is funding for a small or medium-sized business that you repay, with interest, over an agreed term. It is for owners of smaller firms who need money for stock, equipment, premises, staff, marketing or cash flow but often find high street banks cautious because of limited trading history or security. Loans can be unsecured or secured, and come from banks, specialist lenders and government-backed schemes.
Smart Funding Solutions is a broker, not a lender. We look across our panel of 300+ lenders, many of which specialise in smaller businesses, arrange funding from around £10,000 to £500,000+, with larger facilities available in suitable cases. Loans are one part of the wider business finance picture.
Not ready for the full application? Leave a few details and a broker will call you to talk it through. It is free, with no obligation.
The lender assesses your business, agrees an amount and pays it to your business account. You repay in regular instalments over the term, covering capital and interest. Some products work differently: a revolving credit facility lets you draw and repay as needed, and a merchant cash advance is repaid as a share of card takings. The right structure depends on what the money is for and how your cash comes in.
There is no single rate for small business loans. Lenders price each application on your trading history, turnover, profitability, credit record, the amount, the term and any security. Terms range from a few months for short term finance to several years for secured loans.
As well as interest, you may pay an arrangement fee and, with some lenders, early repayment charges. Compare offers on the total amount repayable.
Most UK small businesses with a year or two of trading, steady bank statements and repayments that fit comfortably within cash flow can qualify with some lender, although the choice narrows for newer firms or weaker credit. Lenders typically weigh up:
There is no set credit score that guarantees a loan. If you are just starting out, see start up business loans; for the very smallest firms, our guide to micro business loans covers the options.
A weaker credit history does not always rule you out. Some lenders focus on current trading and bank statements, although pricing is usually higher. If you have been declined before, find out why, deal with any outstanding arrears, and make sure your accounts and bank statements tell a clear story before reapplying.
Small business loans are secured in one of two ways: on property or other assets, or, for unsecured lending, through a personal guarantee from the directors or owners. Most small business loans, especially unsecured ones, require a personal guarantee from the directors or owners. This makes you personally responsible if the business cannot repay. Directors can look at personal guarantee insurance from specialist insurers to cover part of that risk; we do not give insurance advice.
A small business loan typically takes from a few days to a few weeks, depending mainly on whether it is secured. Unsecured loans are the quickest: once a lender has bank statements, accounts and ID, a decision often follows within days, with funds soon after the agreement and guarantee are signed. Asset finance usually moves at a similar pace once there is a supplier invoice. Secured loans take longer, commonly four to eight weeks, because the lender instructs a valuation and solicitors deal with the legal charge. Government-backed lending can add some extra checks. The most common causes of delay are out-of-date management accounts, unexplained items on bank statements and missing ID, so having these ready shortens the process.
A loan is not always the best answer, and the right alternative depends on what is causing the need. If cash is tied up in unpaid invoices, invoice finance releases it without adding a term loan. For a tax bill, VAT funding or a Time to Pay arrangement with HMRC can spread the cost. Equipment can be funded through asset finance, so the asset largely pays for itself over its working life. For short, irregular gaps, an overdraft or revolving credit may cost less than a fixed loan; our guide to overdrafts versus business loans compares them. Grants suit specific projects but are competitive and slow, as explained in business grants vs business loans.
£50,000
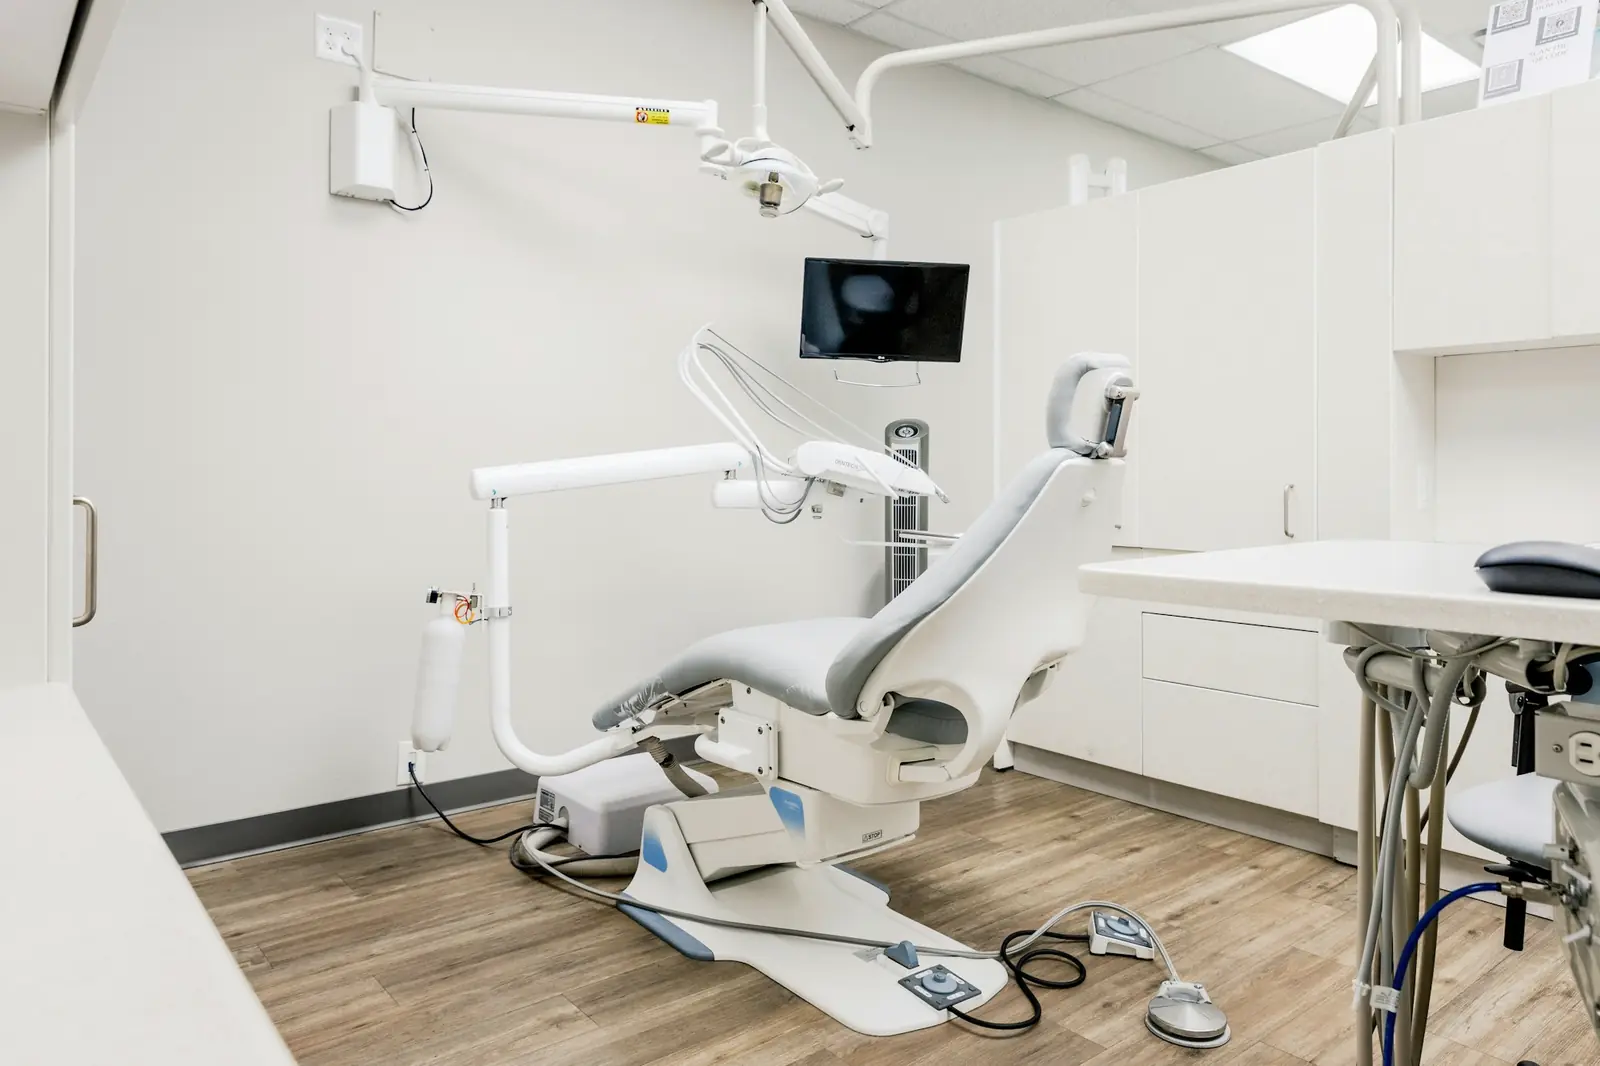
Historic loss. Improving numbers. £50K secured for dental growth.
Several lenders focused on the previous year's numbers. We focused on what had changed.
Historic accounts matter, but they aren't always the whole business.
Read the transactionMake sure repayments are affordable even if trading dips. Finance of £25,000 or less to sole traders and small partnerships can be regulated consumer credit, which gives additional protections.
How the main business finance structures work. Lenders set their own terms, so treat this as a guide to the questions to ask.
| Option | How you repay | Security | Often used for |
|---|---|---|---|
| Unsecured business loan | Fixed instalments, usually monthly | No charge over assets; a personal guarantee is usually required | Growth, stock, tax bills and cash flow |
| Secured business loan | Fixed instalments, often over a longer term | A charge over property or other assets | Larger sums, property and refinancing |
| Revolving credit facility | Interest on what you draw; repay and redraw | Varies by lender and case | Recurring or uneven cash flow gaps |
| Merchant cash advance | A share of future card takings | No charge over assets | Card-taking businesses with uneven months |
| Asset finance | Regular payments over the life of the asset | The asset being financed | Equipment, vehicles and machinery |
| Invoice finance | Settled as customers pay their invoices | Your unpaid invoices | Businesses waiting on customer payment |
General information only. Every lender has its own criteria, and all finance is subject to status.
| Finance type | How it works | Suits |
|---|---|---|
| Unsecured business loan | Lump sum repaid in fixed instalments; usually a personal guarantee, no charge over property | Growth, refits, marketing, one-off projects |
| Secured business loan | Borrowing secured on property or assets, often larger and longer | Bigger investments, refinancing, premises |
| Asset finance | Hire purchase or leasing, secured on the equipment or vehicle | Machinery, vehicles, IT and equipment |
| Invoice finance | Advance against unpaid customer invoices | B2B firms waiting on long payment terms |
| Revolving credit facility | Draw, repay and redraw up to a limit; interest only on what you use | Fluctuating cash flow |
| Merchant cash advance | Upfront sum repaid as a share of future card takings | Retail and hospitality with steady card sales |
| VAT and tax loans | Short-term loan spreading an HMRC bill into instalments | Protecting cash flow when a tax bill is due |
Unsecured business loans are quicker to arrange and do not put a specific asset at risk, but amounts are smaller, terms shorter and pricing higher. Secured business loans offer more money at lower cost, but the asset can be repossessed if you cannot repay.
It is free to enquire; any broker fee is disclosed separately before you proceed. When you are ready, you can explore funding options online.
Simon has been fantastic in supporting my business to secure suitable funding across several deals. He is fair and always gives advice that is in the best interest of his clients. I would recommend them to anyone.
Illustrative figures from the numbers you enter, before you speak to a lender.
How much a small business can borrow depends on turnover, profitability, credit history, existing debts and any security offered. Unsecured lenders usually size a loan against turnover and the affordability shown in bank statements; secured lenders look mainly at the value of the property or asset. Once we have seen your accounts and recent statements, we can say what range is realistic before any lender is approached.
Yes. The British Business Bank supports schemes delivered through accredited lenders, including Start Up Loans for new businesses and the Growth Guarantee Scheme, which replaced the Recovery Loan Scheme from 1 July 2024. The guarantee is to the lender; you remain fully liable, and the lender still makes the decision. Check the British Business Bank for current availability.
It is harder, because most lenders want to see accounts or bank statements before they lend. Some will consider new businesses where the owners have relevant experience, good personal credit, a personal contribution and a solid plan. Government-backed start-up loans and asset finance are often more accessible routes. Our page on start-up business loans covers funding for businesses that have only just begun trading.
Not always. For smaller loans to established businesses, lenders often rely on bank statements and accounts instead. A business plan and cash flow forecast become more important for start-ups, larger amounts or borrowing linked to growth, because they show what the money is for and how it will be repaid. Our guide on how to write a business plan for funding explains what lenders look for.
A small business loan can affect your personal credit, particularly if you are a sole trader or partner, or if you give a personal guarantee as a director. Lenders usually check the directors' personal credit files when you apply, and some may use a soft search at the early stage before a full search on application. If a loan backed by your personal guarantee is not repaid, the debt could ultimately become your personal liability.
The amount was large relative to turnover. We placed it with a lender willing to look at the whole financial picture.
The key was a lender and repayment structure that matched how the business trades today.

A £100,000 business loan is usually a term loan repaid monthly over about one to six years. Established businesses with two or…

For a firm with fewer than 10 staff, the safest borrowing is usually a modest amount whose repayments still work in your…

The financial ratios lenders look at fall into three groups. Profitability: EBITDA and its margin and trend. Debt capacity:…

A company in a Company Voluntary Arrangement can raise new finance, but mainly where the lender relies on security rather than…

A £250,000 business loan is usually a term loan, or a combination of facilities, repaid over several years. At this size…
Often, yes. Past defaults, CCJs or arrears do not rule out business finance, but they narrow the choice of lender and usually…
Tell us what the funding is for. We search our panel of 300+ lenders, structure the case and approach the ones suited to it. No obligation, and free to enquire.
Live chat with our team. Our chat is provided by Crisp, which sets cookies so your conversation is kept and we can see which page you are viewing. It only switches on if you allow it. Cookie Policy